To those saying that we don’t “pay in” to a state pension, and that it is a benefit, why is there an online government State Pension forecast based on…what you’ve paid in?
On top of which, if you haven’t paid in enough, you can top it up before retirement to increase what you receive in your state pension.
Payments in = Pension. Fact.
The gaslighting by the Left is getting tedious now.
https://t.co/Q8bsFBmqLZ
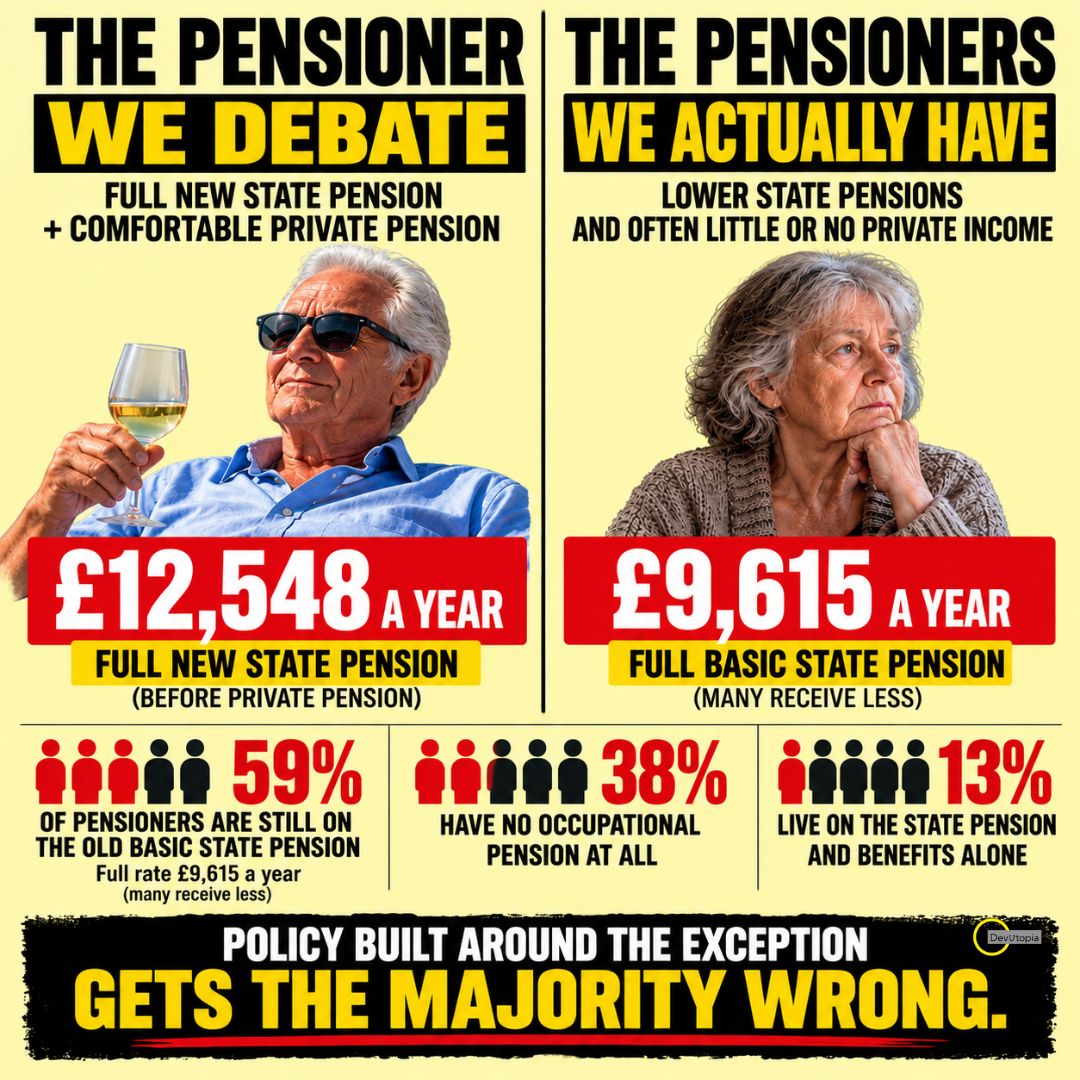
The triple lock debate is built around a pensioner who mostly doesn't exist.
The perception: the full new State Pension of £12,548 a year, topped up by a comfortable private pension.
The data: 59% of pensioners are still on the old basic State Pension, where the full rate is £9,615 a year. 38% have no occupational pension at all. 13% live on the State Pension and benefits alone.
And the next generation has less. Final salary schemes are closing. The median pension pot accessed last year was around £20k. Turned into an annuity, a guaranteed pension for life bought with the pot, pays roughly £1,500 a year.
Burnham's pension change is being debated for the pensioner in the headlines. It lands on the one in the data.
(sources ⬇️ )
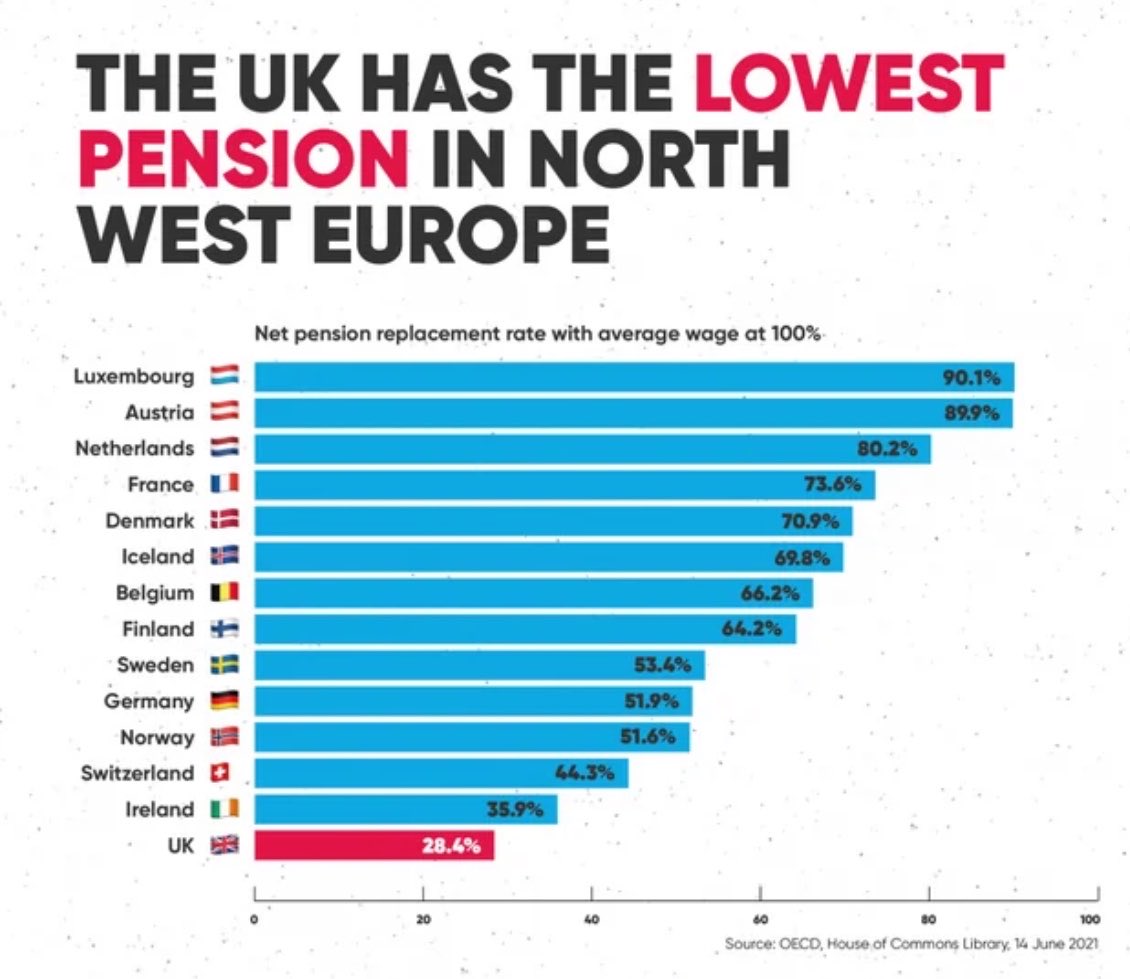
The UK state pension replaces roughly 22% of an average worker's pre-retirement earnings, ranking lowest among G7 countries. In contrast, countries like France replace over 50% and Italy over 75%.
We should be aiming to be like France & Italy not making pensioners poorer.
Excuse me saying but I worked for 40 years for my pension. It’s not a benefit, I paid into it expecting a comfortable retirement. I had to wait another extra 6 years without much warning
When I was young I paid happily for pensioners then. I actually expect the same in return.
UK spends 5.1% GDP on state pensions vs an OECD average of 8.1% and an EU average of 12.9%. UK pensions are just 25% of salary replacement vs 76% in Italy and 58% in France - So even with the Triple Lock UK pensioners are lagging behind!
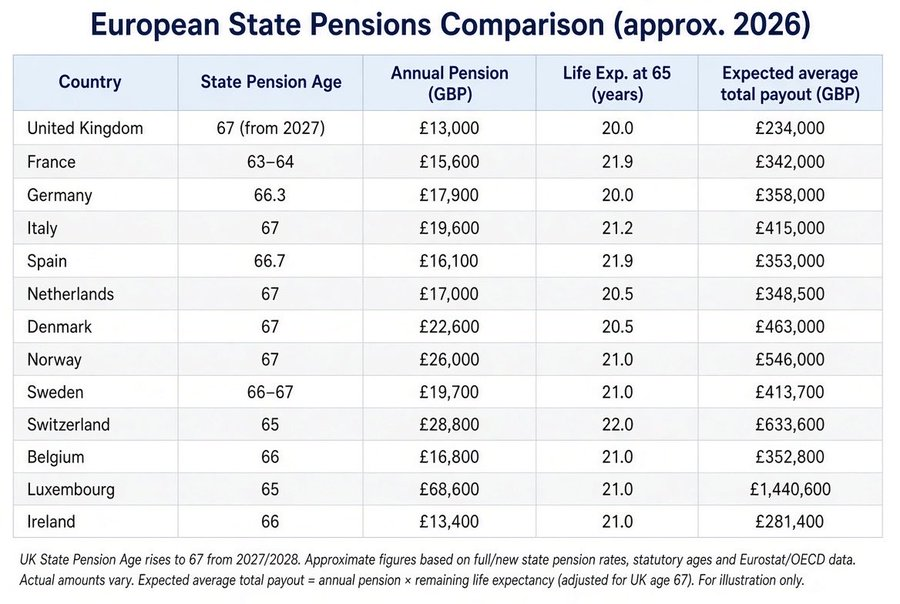
The UK has the lowest state pensions in Europe.
They are being further attacked to increase weapons spending. The non-existent national care system is smoke and mirrors.
Just for clarity, the pension triple lock is not three increases. It is one increase based on three factors.
1. A minimum of 2.5%
2. The average annual wage growth
3. Or annual inflation
Despite a lock the payment remains a comparative pittance.
Don’t let @andyburnham con you.
Burnham didn't mention screwing pensioners when posing as man of the people.
Britain's £12,547 state pension is less than half the minimum wage and well below the EU average. Many rely entirely on it.
If Burnham scraps the triple lock, young people face poverty in retirement.
Thatcher broke link between earnings & pensions forcing millions of pensioners to live in poverty for decades to come. Triple lock helped reverse some of the damage. With 2 million pensioners still in poverty no Labour government would go near scrapping it & risk next election.
State pension is not a “benefit”.
It’s not free money or charity.
You pay into the system your entire working life.
It’s deferred wages you earned.
Stop treating it like a handout.
Those who argue that the State Pension is a benefit, are correct, however they fail to point out that it is a contributory benefit.
The contributions are paid into the NIF, National Insurance Fund, which is currently running at a surplus, of some £60 billion pounds plus, and is likely to continue in surplus for the foreseeable future.
What the NIF is
The National Insurance Fund (NIF) is the ring‑fenced pot that holds National Insurance contributions (NICs) paid by employees, employers, and the self‑employed. It is legally separate from general taxation. Its purpose is to pay contributory benefits, mainly:
State Pension
New‑style Jobseeker’s Allowance
Employment and Support Allowance
Maternity Allowance
Other contributory benefits
This definition is confirmed in the official NIF accounts:
The NIF “holds National Insurance Contributions… and is mainly used to pay social security benefits such as contributory benefits and the State Pension.”
Is the NIF in surplus?
Yes. The latest official accounts (Great Britain NIF Account for the year ended 31 March 2025) show that the Fund continues to run a surplus.
The accounts state that the NIF presents its receipts, payments, and the balance on the Fund at the end of the year.
What the numbers show
While the search results do not display the exact balance figure in the snippet, the Great Britain NIF Account 2024–25 is the authoritative source. Historically and up to the latest release:
The NIF has maintained a large surplus, typically £30–£40 billion in earlier years.
Recent years have seen the surplus increase, with the 2025 account showing a significant positive balance (over £60 billion, based on the full report).
The Fund remains comfortably above the statutory minimum recommended by the Government Actuary’s Department (GAD), which is usually around one‑sixth of annual benefit payments.
Why the NIF stays in surplus
Several structural reasons:
NIC receipts exceed annual contributory benefit payments.
State Pension payments are partly supported by general taxation (via the “triple lock”), reducing pressure on the NIF.
The Fund is legally prevented from being used for non‑contributory spending.
The government can adjust NIC rates or Treasury grants if needed.
Bottom line
NIF = National Insurance Fund
Purpose = Pay contributory benefits (mainly State Pension)
Status = In surplus, with a large positive balance
Latest accounts (2025) confirm ongoing surplus.
I hope this clarifies the issue.
BBC security correspondent Frank Gardner: "I don’t understand why Donald Trump is saying we had these people under view for a long time. I don’t know where he got that from, because if they did then how on earth were they allowed to wander round Gloucestershire putting on masks and driving vans allegedly with explosives in them?”
https://t.co/L0jGiFhf3K
Instead of cancelling the Triple Lock we should cancel the Tax Breaks for billionaires.
The Tax Breaks for just 150 people cost more than 10x as much as the Triple Lock.
Did you hear that?
15 Billionaires are costing as much as the Triple Lock, but you don't hear the Billionaire Media ranting about that...
State Pension is NOT a benefit. Workers paid for decades into a compulsory National Insurance system. The contract is : you pay in, you receive your pension. The only ‘benefit’ is the top up pension paid out to those who never worked long enough to get their full pension.
Danny Kruger explains that our crypto billionaire donors will get absolutely nothing in return for their donations. In unrelated news, we plan to cut capital gains tax on crypto assets from 24% to 10% and set up a Bank of England Bitcoin Reserve Fund.
#BBCQT
Amount a pensioner receives in the UK is the lowest in Europe, just 2/3rds of France and barely 50% of Italy who are considered a 'poorer' country.
Why is our pension 'unaffordable' when it is so low, and where is all our money actually going?