I don’t expect Tesla to flood Austin with Cybercabs anytime soon. The launch will involve a few dozen vehicles at most.
The current exponential ramp, doubling roughly every five weeks, should continue this year. I don’t expect more than a few thousand Cybercabs in operation by December. My base case remains around 1,000 vehicles.
Once the launch is over, the next outcry will be about the slow increase in fleet size.
Manage your expectations. Look at where we are today.
A few years ago the uncertainty was about the outcome. Now it’s only about the timing. That’s the whole difference.
InP Optical Interconnect Bottleneck Heats Up: AXTI and LandMark Surge, Sumitomo Pulls Back — Industry Opportunity Emerging
The AI optical interconnect supply chain has once again become a market focus. News of a severe shortage in indium phosphide (InP) substrates and epitaxial wafers continues to drive related stocks higher.
AXTI (U.S.-listed) , one of the world’s major InP substrate suppliers, has shown strong upward momentum amid the shortage and consecutive price-hike narrative. The market is paying close attention to its capacity locking and pricing power, bringing this long-viewed “upstream chokepoint” name back into the spotlight.
LandMark Optoelectronics (https://t.co/jcHw05ZWWk) has also benefited clearly. As a key Taiwanese supplier of InP epitaxial wafers and CW lasers, the company continues to post record revenue and profits. It has already signed a long-term substrate supply agreement with Sumitomo Electric, reducing material shortage risks. Combined with rising silicon photonics shipments and aggressive capacity expansion, its share price has been strong recently and has become one of the leading names in Taiwan’s optical communication sector.
In contrast, Sumitomo Electric (5802.T) , one of the world’s largest InP substrate suppliers, has entered a pullback/adjustment phase after earlier gains this year. While fundamentals remain supported by demand, its large conglomerate nature and partial internal consumption of capacity have led to a more moderate stock reaction, leaving it currently in a consolidation phase.
The broader industry opportunity is starting to surface
The InP shortage is not a short-term issue. Global effective capacity remains far below the demand driven by AI data centers for 800G, 1.6T, and future CPO architectures, while capacity expansion typically takes two to three years. This gives both upstream substrate players (AXTI, Sumitomo) and midstream epi/laser suppliers (LandMark, Visual Photonics Epitaxy, and others) room for pricing power and growth.
The market is beginning to shift from focusing on individual surging stocks toward broader attention across the entire supply chain. Sumitomo’s pullback may actually offer a chance to observe accumulation in a major supplier, while the strength in AXTI and LandMark highlights the value of chokepoints and execution capability. With Q4 price hikes confirming the tightness and new capacity gradually coming online into 2027, the overall optical interconnect supply chain still has potential to extend this structural uptrend.
(This is an industry observation summary only and does not constitute any investment advice. Stock prices are highly volatile; please assess risks independently)
It’s merely a technical demonstration/showcase and brings no positive benefit whatsoever to operations. Yet the stock still rose in the morning session because of this?
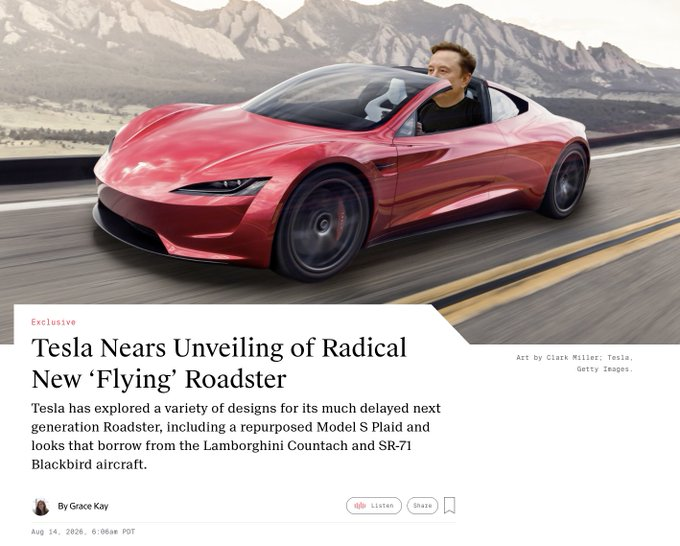
$TSLA is reportedly preparing to unveil its long-delayed Roadster as early as this month with a $SPCX powered version using cold-gas thrusters to “fly.”
What started as Tesla’s next hypercar has evolved into a showcase of Tesla and SpaceX engineering increasingly converging.