Short-term US stock setups.
What you’ll find here:
• Pre-market watchlists
• Catalysts and key levels
• Clear confirmation and invalidation
• Post-market reviews—including setups that failed
Every setup is a scenario, not a certainty.
Follow for the plan—and the review.
$VZ guides to about 4% Q4 mobility/broadband service-revenue growth. Holder plan: consider reducing exposure if churn reverses and cash generation weakens enough to undermine dividends plus debt reduction. Next checks: service revenue, churn and cash after capex.
$VZ reported Q3 free cash flow of $7.8B, up 12.1% YoY. That strengthens the cash-return thesis, but one quarter isn't a dividend guarantee. Holder plan: keep exposure within the original risk budget; wait for Q4 service-revenue and cash-flow delivery before adding.
$PLTR highlighted sovereign AI customer deployments on Oct 21. That supports adoption, but does not quantify incremental revenue. Holders can keep exposure within their risk budget while waiting for revenue conversion and guidance at Nov 2 earnings.
Holder plan: wait for monetization evidence before adding on customer headlines. If Nov 2 guidance or conversion undermines the growth thesis, consider reducing exposure. A deployment announcement alone cannot establish the earnings contribution.
$DECK repurchased $637M of shares in FY27's first half. Its full-year EPS outlook assumes $1B of buybacks—not $1B already completed. A smaller share count can lift EPS without stronger demand. Holders: track net income, diluted shares and cash generation together.
$AXP's FY26 EPS guide is $18.30–$18.60 GAAP, versus $17.60–$17.90 adjusted. Mixing those bases can distort valuation comparisons. Holders: watch whether spending and fee growth sustain earnings as credit costs evolve.
$DECK Q2 gross margin rose to 60.5% from 56.2%, but tariff refunds contributed about 3.1 percentage points. Most of the uplift wasn't demand-driven. Holders: watch DTC comparable sales, down 6.4%, and whether margins hold without refunds.
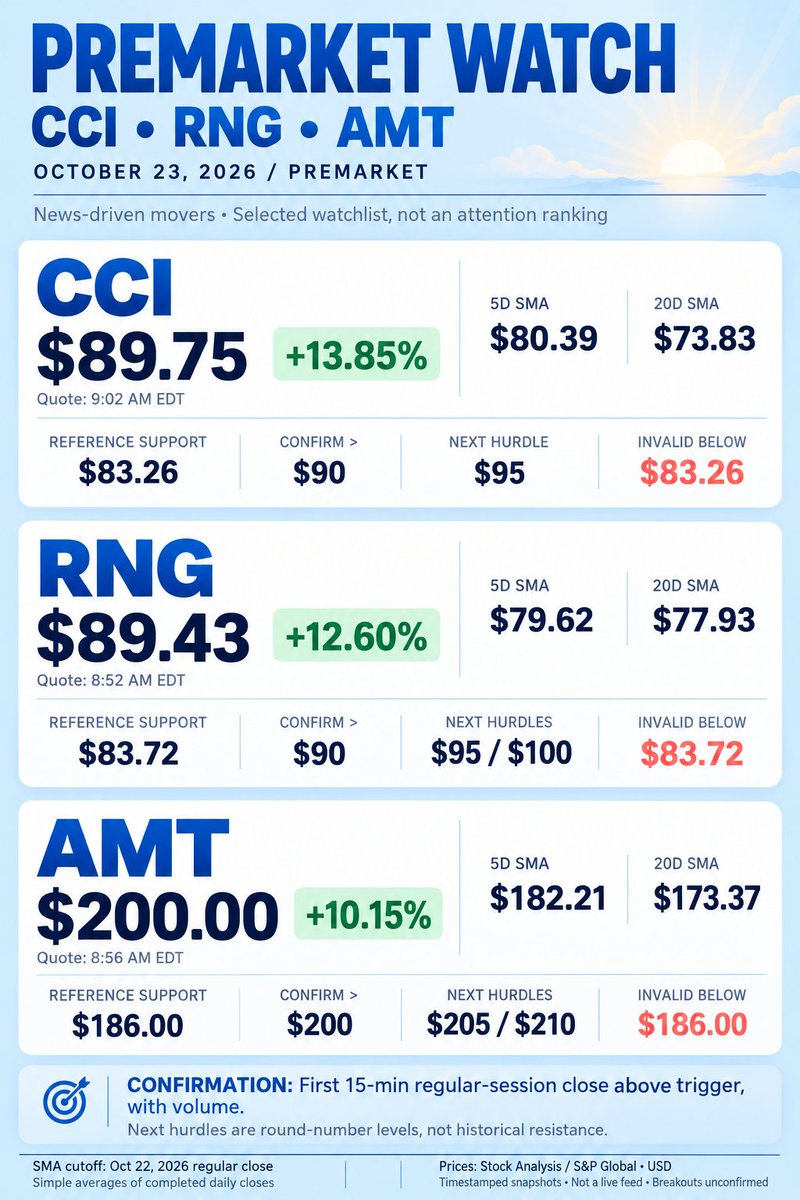
$AMT $200.00 (+10.15%), Oct 23, 8:56 ET premarket. Reported SpaceX carrier talks lift tower stocks; no deal confirmed. A first 15-min close above $200 on volume puts $205/$210 in play as round-number hurdles. Below $186, the setup fails.
$CCI $89.75 (+13.85%), Oct 23, 9:02 ET premarket. Reported SpaceX talks are the catalyst, not a signed deal. Bullish if the first 15-min candle closes above $90 on volume; $95 is the next round-number hurdle. Below $83.26, the setup fails.
👇👇👇
$RNG $89.43 (+12.60%), Oct 23, 8:52 ET premarket. Strong Q3 results and raised guidance put it in focus. A first 15-min close above $90 on volume opens $95, then $100—round-number hurdles. Below $83.72, the bullish setup fails.
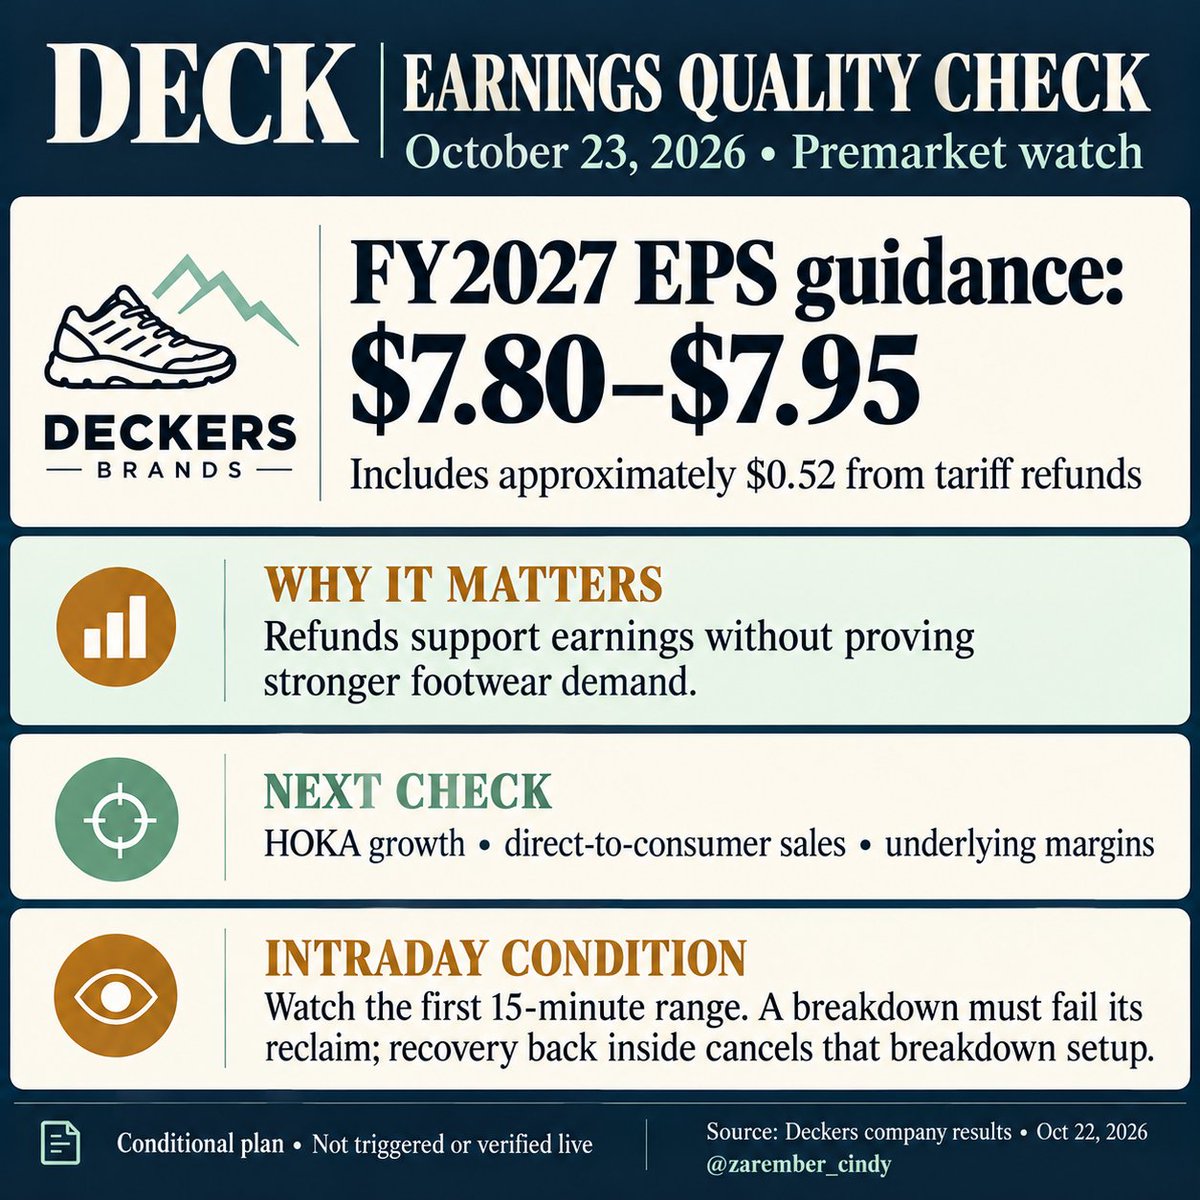
$DECK opening plan: watch the first 15-minute range. A break below its low needs a failed reclaim; recovery inside cancels that breakdown setup. Intraday weakness alone doesn't establish that the long-term brand thesis is broken.
$DECK's FY27 EPS guide of $7.80–$7.95 includes about $0.52 from tariff refunds. That supports profit, but doesn't prove stronger shoe demand. Holders: next check HOKA growth, direct-to-consumer sales and margins excluding the refund benefit.
$AXP opening plan: mark the first 15-minute range. A break above its high needs a successful retest; a return inside cancels that breakout setup. This is a conditional plan, not a confirmed signal or a verdict on credit quality.
$AXP Q3 revenue rose 9% to $20.1B. Credit-loss provisions fell to $1.0B from $1.3B, helped by a reserve release—even as net write-offs rose. Holders: watch spending growth and credit losses together. Lower provisions alone don't prove healthier borrowers.
$WDC revenue rose 55% to $4.38B. Next-quarter guidance: $5.1B revenue midpoint and 60.5% non-GAAP gross margin. That strengthens the earnings thesis, but holders need pricing and shipment growth to deliver. Watch margin execution—not just the headline beat.
$WDC scheduled earnings after today's close. For holders, the test is revenue guidance, gross margin and operating cash flow—not just an EPS beat. Carrying a day trade overnight adds gap risk: a stop price cannot guarantee an exit at that level.
$META reported Q3 GAAP EPS of $3.83; excluding a $9.89B legal charge, the company puts EPS at $7.40. That helps isolate operating performance—but doesn't erase the cash obligation. Holders: next check the settlement payment schedule and legal liabilities.
$LRCX guides December-quarter revenue to $8.6B ± $0.4B. China was 35% of September sales—a risk to the earnings thesis if export rules tighten. Holders: watch equipment orders and guidance revisions. Record profits alone don't remove that exposure.