Well some companies prefer to buyback stock at the wrong time all I’m saying is the read of the tea leaves to me says tidewater thinks the intrinsic value is a premium to its pre Wilson’s fleet which seems obvious but not every company acts like a value investor so it’s nice to see them do it and be direct about it
$TDW $RIG $VAL $OIH $SLB $XOP $SDRL $NE
Tidewater Q3 results were much stronger than I anticipated.
Seeing the leading edge at $27K with spare capacity ~11% of the fleet to reprice opportunistically is also a promising move.
At 82% util guide for 2027 that assumes a $2,700 increase in day rate but we think that actually undershoots what realized day rates could be in 2027.
FCF generation is going to allow for continued leverage declines though at a paltry 0.9x leveraged ratio now, we think any focus on debt is simply over thinking the businesses position at this point.
The buyback is unlimited in its application at these leverage ratios and we continue to believe that will be the case as leverage ratios are something like 0.6-07x by early next year.
Wilsons is closed and integration is expected complete by Q1 2027. That fleet is inherently value add not just in the optionality from access to Brazil but because of the position Brazil is in as a major offshore development hub which importantly is a bipartisan effort regardless of who is in office in Brazil.
Transocean talked about vessels moving from USG > West Africa and Tidewater was no different. Because of sluggish demand in the USG vessels are recontracting for work in Suriname (via Total), Guyana and Africa - markets Tidewater and Transocean remain incrementally bullish on in the next 24 months.
Asia Pacific has been strong with more projects to come in 2027 in Malaysia, Thailand, Vietnam and Indonesia. Indonesia specifically is seeing development pulled forward.
Projects we think Tidewater management was thinking about for continued demand include: Venus in Nambia, Neptun Deep in Romania, GranMorgu in Suriname, Bonga North Nigeria, Coral North FLNG, Agogo Integrated West Hub development in Angola, Buzios broadly alongside Albacora FPSO + 2 Sergipe FPSOs arriving later in the decade. CPOC Petronas/PTTEP JV in Asia Pacific.
Importantly, the less developed a basin, the more support required and more infrastructure that needs built. This is why we are incrementally bullish on the move out of the USG where intensity on vessels is higher and offer a more nascent development picture at this point - this further adds to our point that Tidewater, in the big picture of multi billion dollar FPSO/Drillships & subsea/SURF tech is a drop in the bucket to project economics.
Are you going to haggle hard over a few thousand in day rate when you are paying $500K a day for a drill ship and risk project delays and lost cost from untimely drill mud and equipment? We find that increasingly unlikely.
The buyback program restarting is a net positive and we think it is notable Tidewater management reasserted the point on buybacks relative to intrinsic value inclusive of Wilsons in our mind, this means they are clearly underwriting the buyback decision on a bigger, better fleet therefore the pace and intensity of buybacks even at $75-80 is highly economic where perhaps it wasn't as promising in 2H 2024-2025.
Supply that has been ordered largely was repurposed for other industries and different work with just 2 notable deliveries of OSVs from that 2024 order backlog.
We think supply is going to continue to be hard pressed to bring on and even if one wanted to - who is going to pay for it? OSV operator balance sheets cant support the type of scale required not even at the current leading edge.
We think Tidewater stands to earn something like $1.3B in cumulative FCF for 2027-2028. For next year, We think EBITDA could be a touch over $800M and using company average EV/EBITDA we think 8-10x is more than fair.
The wild card in our per share FCF is what does the pace of BB look like from here? Management notes vessel secondhand rates have exploded in the last 3 months so M&A is probably harder to get done at the prices Tidewater would hope to achieve.
That leaves nothing but high FCF generation that, even if done at $100 reduces roughly 10% of the outstanding shares. The business is absolutely statistically cheap and on 1-2 year forward numbers makes us blush.
We have been buyers throughout the life of this recovery starting back in 2020-2021 and continued to buy in the white space meltdown in 2025.
We think reactivation risk is far over blown. It stands to reason that if new builds from 2024 are being moved to other types of work that companies with old vessels laid up that haven't worked would be skeptical of spending the kind of money required to retrofit vessels and get them to work.
Those reactivations are also inhibited by the same shipyard dynamics as new builds. Our EBITDA walk is as follows:
Call it 63,450 working days on 212 vessels (assumes 82% active util includes dry dock).
Day rates of $27,000 give you revenue of $1.71B - the low end of management estimates (1.70-1.75B) - keeping util flat takes day rates required to just under $28,000 a day in rate for 2027.
Revenue $1.730M
Vessel Opex $825M
Gross Income $900M
Cash G&A $140M
EBITDA $765M
Dry Dock $145M
Capex $45M
Taxes $90M
$480 - $500M FCF
S/O 49M
$9.50 - $10.25 FCF/PS excluding any buyback.
Buyback $475M @ $85 p/s = 5.6M shares retired
Adj. S/O = 43M
The multiple of FCF is yours to assume but does a growing business with high operating leverage at a strong point in the cycle with no new supply coming justify 12-13x FCF? Perhaps. If it doesnt, rest assured the buyback will benefit shareholders even more.
$TDW
Left is current presentation (Q3 2026) right is September Barclays Energy Conference slides.
The entire business is inflecting not just within Tidewater but across the OSV industry broadly ($SMHI)
Iran’s SNSC secretary Mohsen Rezaei called reports of talks “fake news about imaginary talks” and demanded the US “surrender” to Tehran’s seven conditions (end hostilities on all fronts, lift blockade/sanctions, release assets, etc.) before any negotiations. Mediation continues via Qatar but Iran publicly rejects progress claims and signals it will maintain its stance otherwise. US keeps the blockade and holds major new strikes.
Mr Market is as deranged as he has been in a very long time, China & the West continue to move apart, and even value guys dont like value anymore.
What are the details and implications for constructing a portfolio in such an environment? We go in depth in our Monday issue.
$SPY $QQQ $IWM
https://t.co/BtG2lUeaIW
BREAKING: Trump administration sends message to Israel that new US strikes on Iran will target bridges and power plants, and that a return to major combat operations is near, per Israel's Channel 13.
The officiating in the Basset Stanich match was suspect.
Went back and reviewed some of the no take downs and I can see how the first was precautionary for Stanichs knee and was stopped - though I think some would let that wrestle out.
On the cut and take down by basset the officials simply got it wrong.
By the rules Escape (NCAA Rule 4.3): A defensive wrestler is awarded an escape when the offensive wrestler loses control of the opponent while any part of either wrestler remains in bounds. That’s the whole definition. There’s no requirement that the bottom wrestler face the opponent, stand up, or separate
When the top wrestler releases, they’ve lost control, so the bottom wrestler gets the escape point right then.
In practice, that means three things in order:
1The top wrestler actually lets go, so control is lost and the escape is awarded.
2The wrestlers are now in neutral.
3The takedown is a new one: the wrestler regains control, takes the opponent to the mat, and holds it beyond reaction time. Reaction time is determined by each individual referee and is described only as a period of time that is not instantaneous.
Seems clear to me control was lost or in this case intentionally given up and the officials missed the call should have been yet another take down for basset here.
@MrPatMineo@FloWrestling@USAWrestling@NCAAWrestling
French Debt is called irrelevant to world markets by some analysts - we disagree.
A capital control environment or a direct or defacto default on French debt would threaten global liquidity and spread quickly.
We detail how France got here, How it is likely going to be forced to proceed, and the investment implications for such a world.
Enjoy and have a great weekend.
https://t.co/85z8RMI00Z
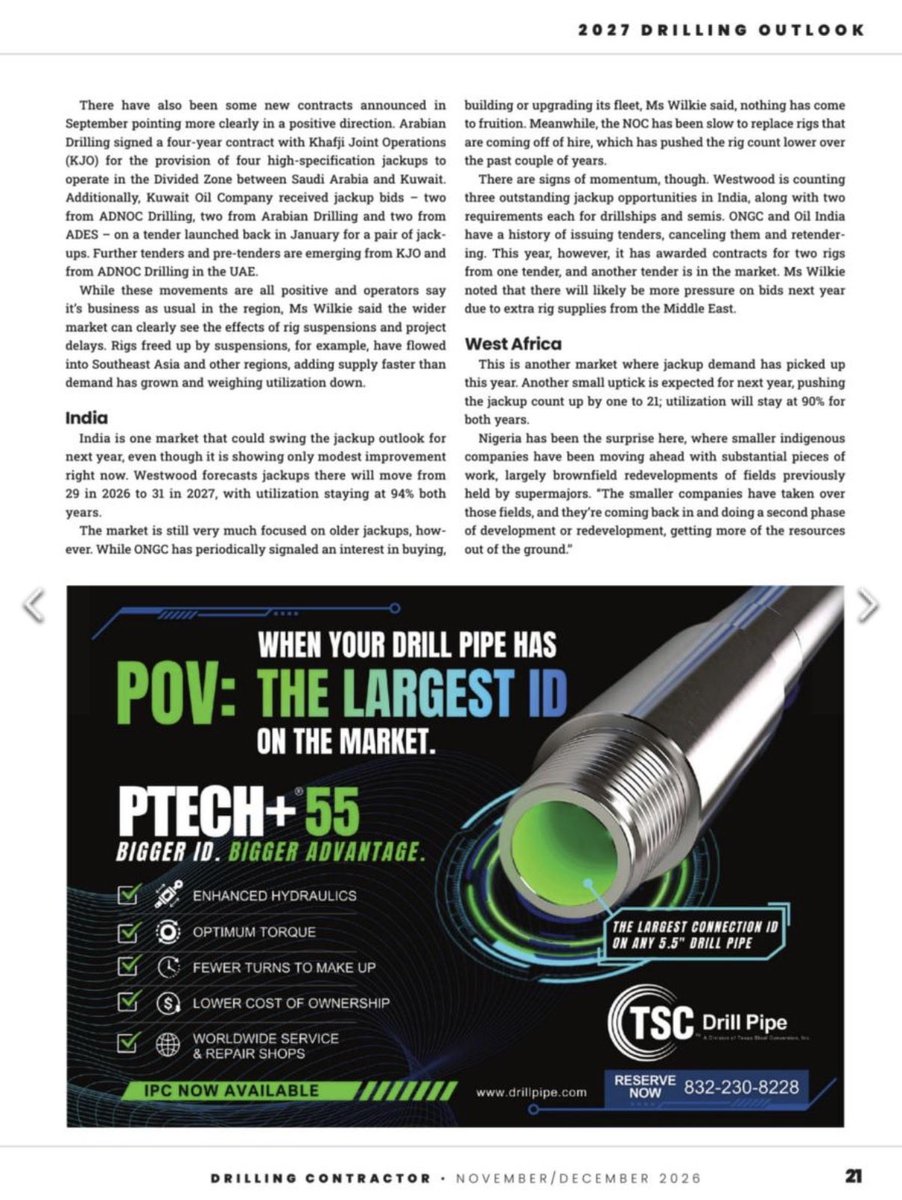
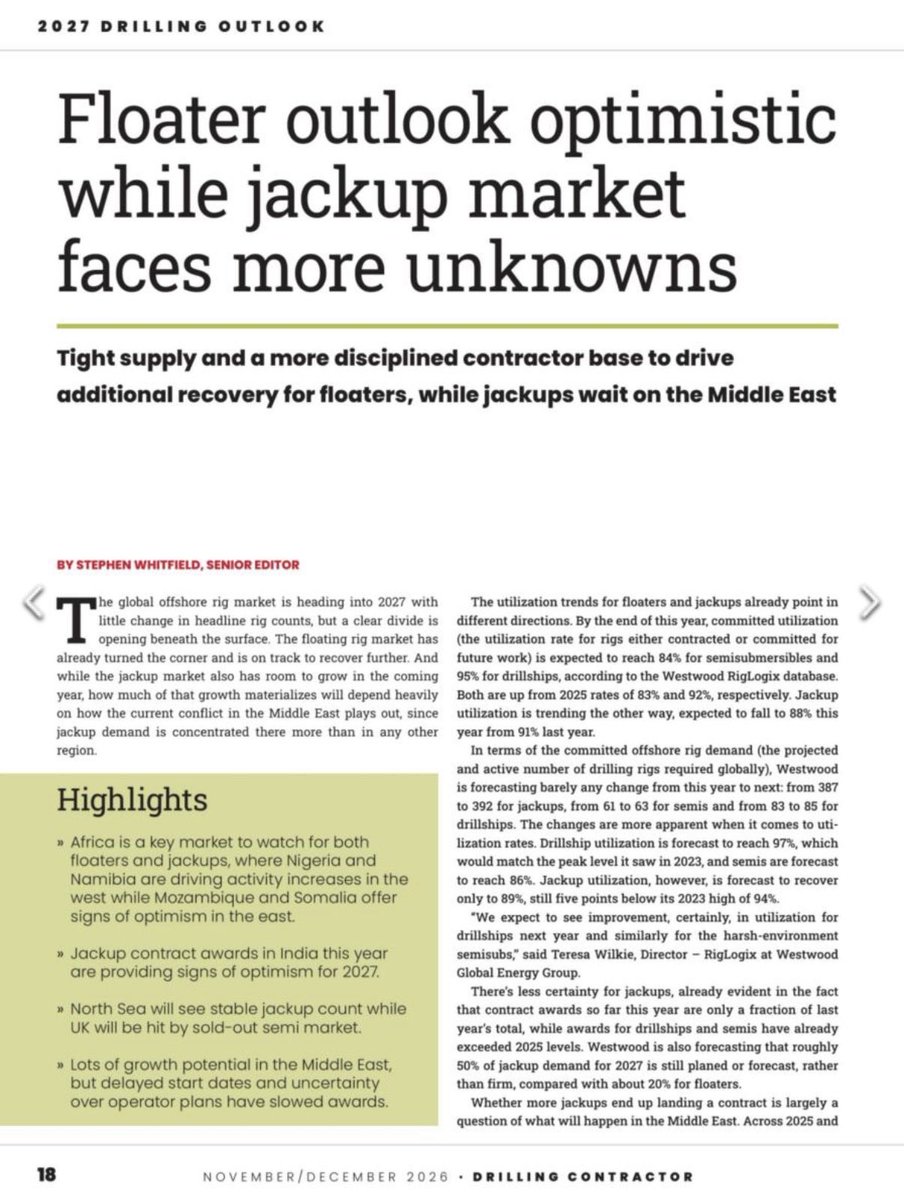
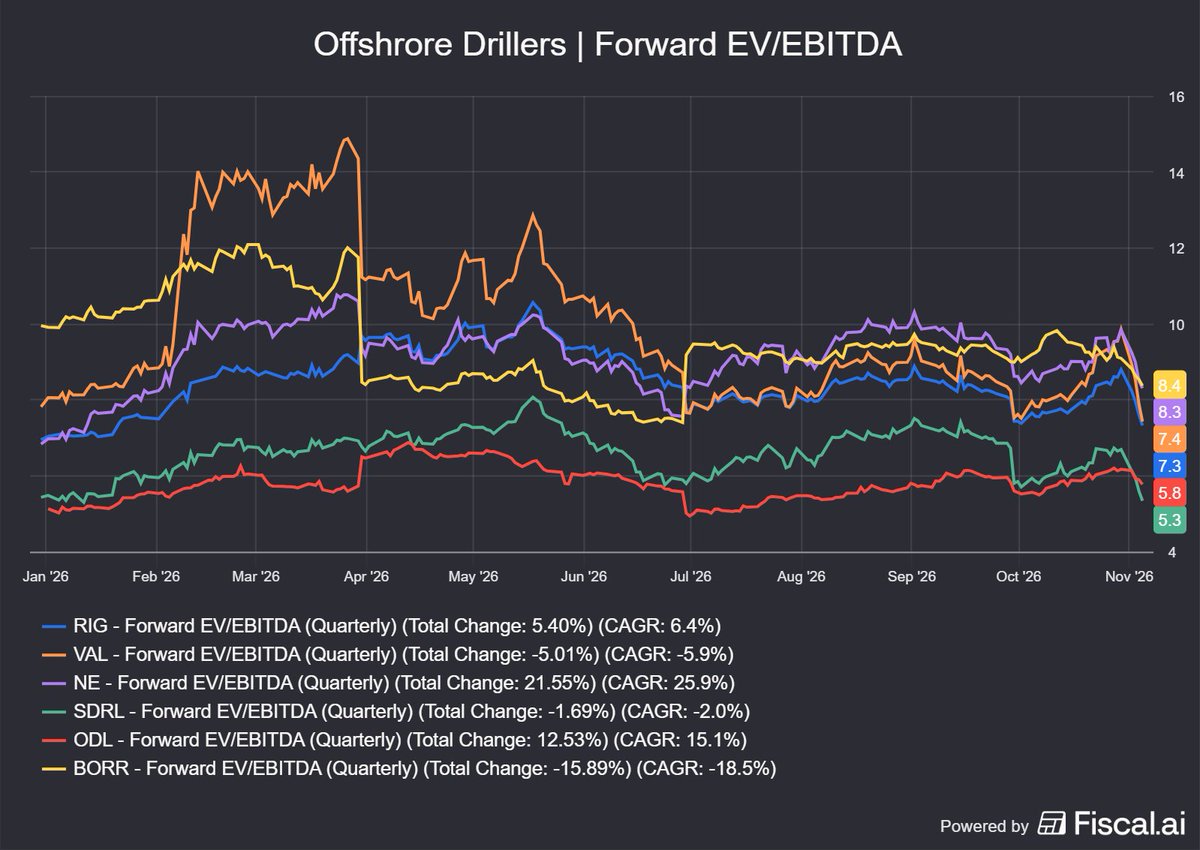
Cheaper than at the beginning of the year.
However, the market materially improved.
Utilisation is approaching 100%. Dayrates are increasing.
$RIG $VAL $NE $SDRL $ODL.OL $BORR