Pro Options trader since 2008, decent sports bettor, new dad. Just trying to make a dollar out of 50 cents. 4x Marathon finisher. *Not financial advice*
GET 50% OFF THE FIRST YEAR of Option Omega software with my discounted link: 👇👇https://t.co/zKPIVeePat
OPTION OMEGA is a popular and reliable tool for backtesting options strategies and trade automation that I have been utilizing for my SPX trading the past year so I wanted to allow you guys to check it out with the best possible deal.
Model any options strategy with live payoff diagrams and full Greeks — watch P&L, breakevens, and risk update in real time. Backtest the most liquid symbols plus automate your trades.
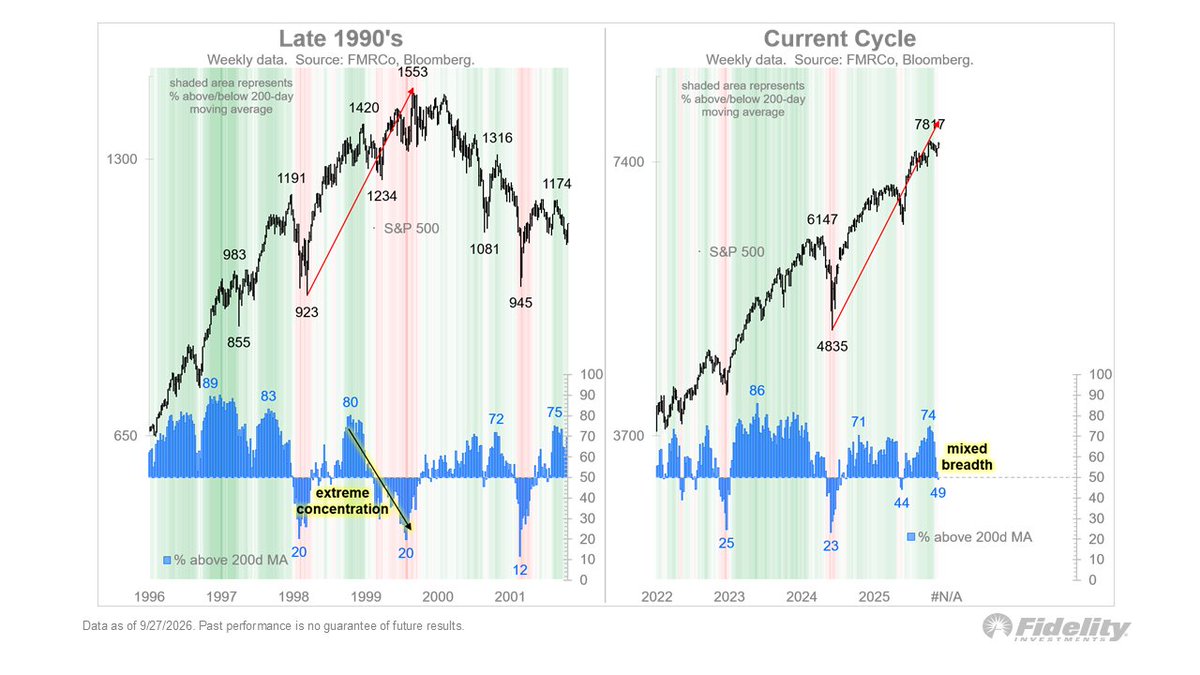
Market observers are pointing out that the internet bubble ended with narrow breadth and the market’s current internals need to be watched as a possible repeat. Indeed, the 1999-2000 blow-off top was an extremely narrow affair with only 20% of stocks participating at the end (below left). Fortunately, today’s 49% breadth (right) provides a favorable comparison for what is otherwise a scary price analog. Note that the two red arrows below are the exact same in both time and price.
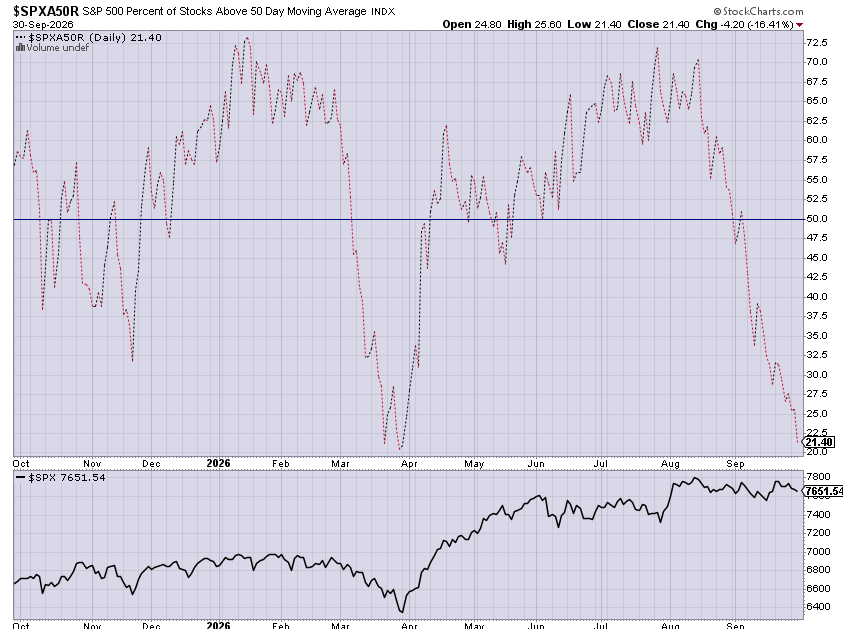
One of the top breadth metrics I track is % of $SPX stocks above the 50 day MA.
It broke under 50% level early in September as a warning to at least reduce overnight risk and be selective to whats showing relative strength.
Now hitting 21.4% today to end the month back near the March lows which marked a bottom. Often like to see this measure get under 20% to signal a potential flush low. We shall see what the next few days show.
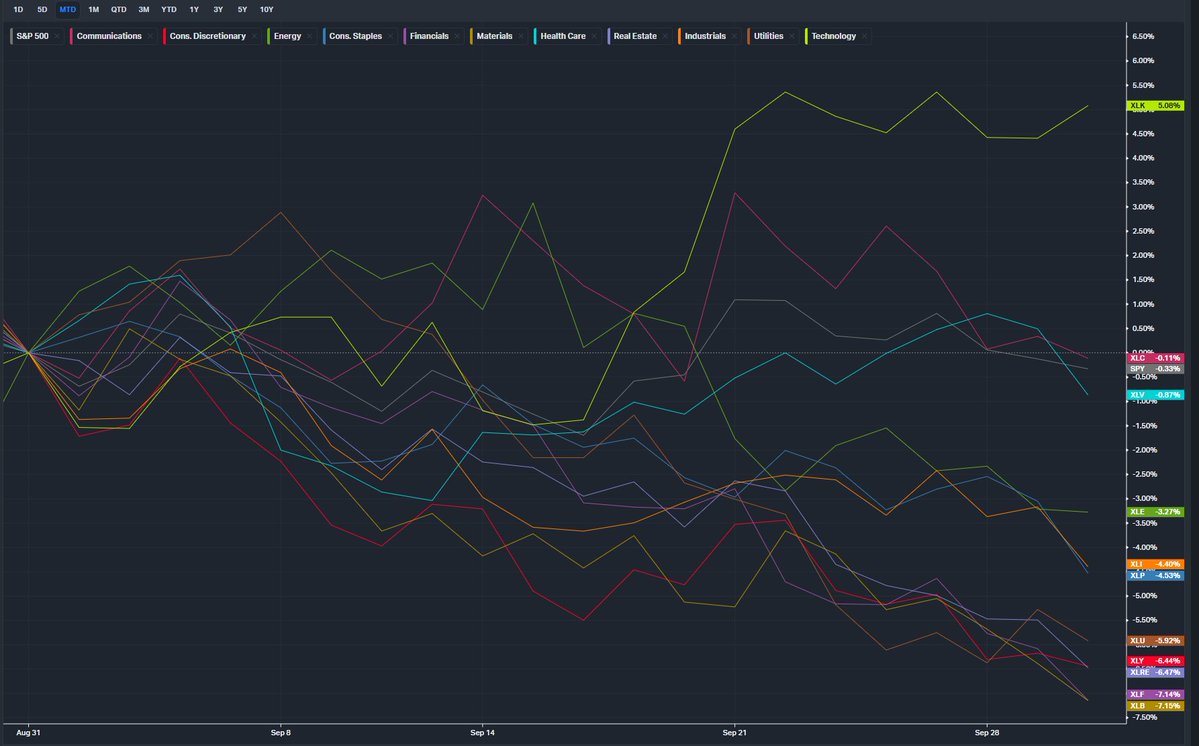
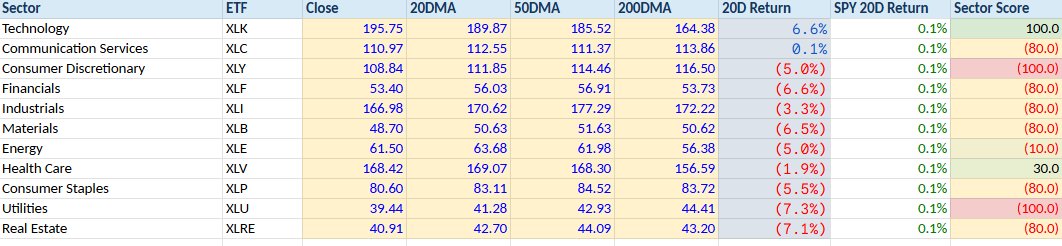
Pretty amazing how September was basically down -4% on a equal weighted basis looking at $RSP but Technology being up +5% held the $SPY near unchanged for the month.
The only two sectors with positive trend scores on my model is Tech and Healthcare
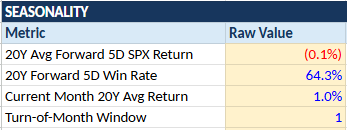
Updating the market model for subscribers and seeing a small improvement in Seasonality pillar now positive as the calendar shifts to October.
SPX 5 day forward win rate going back 20 years is 64.3% the next 5 trading days. Has been stuck under 50% the past few weeks.
Although returns are still choppy first week of Oct it has pointed to positive returns the next 20 days.
S&P 500 Up 10 of last 14 years on October’s first trading day. Longer-term record not as strong. Notable gains occurred in 2002, 2003 and 2022, sizable declines in 1998, 2000 (NAS), 2009, 2011. 2014 and 2019 standout for losses exceeding 1%. https://t.co/msWkTLLajf
@kingofsoysauce this idea was shared here as something to consider into the close.. I cant share 15 minute day trades precisely to the minute and not trying to have a day trade alert service on X
https://t.co/hPb0eUTHFg
Busy post market dad duties spending time with Riley and going for a stroller jog in the sun. The plus side of working from home and taking a break after market closes.
But what a crazy end of day there so wanted to recap my trade into the close that nearly made 1000% on SPX 0DTE long strangles..
End of month backtests have showed a large bias to last hour large moves in SPX for final day of month but even more so final day of the quarter (today)
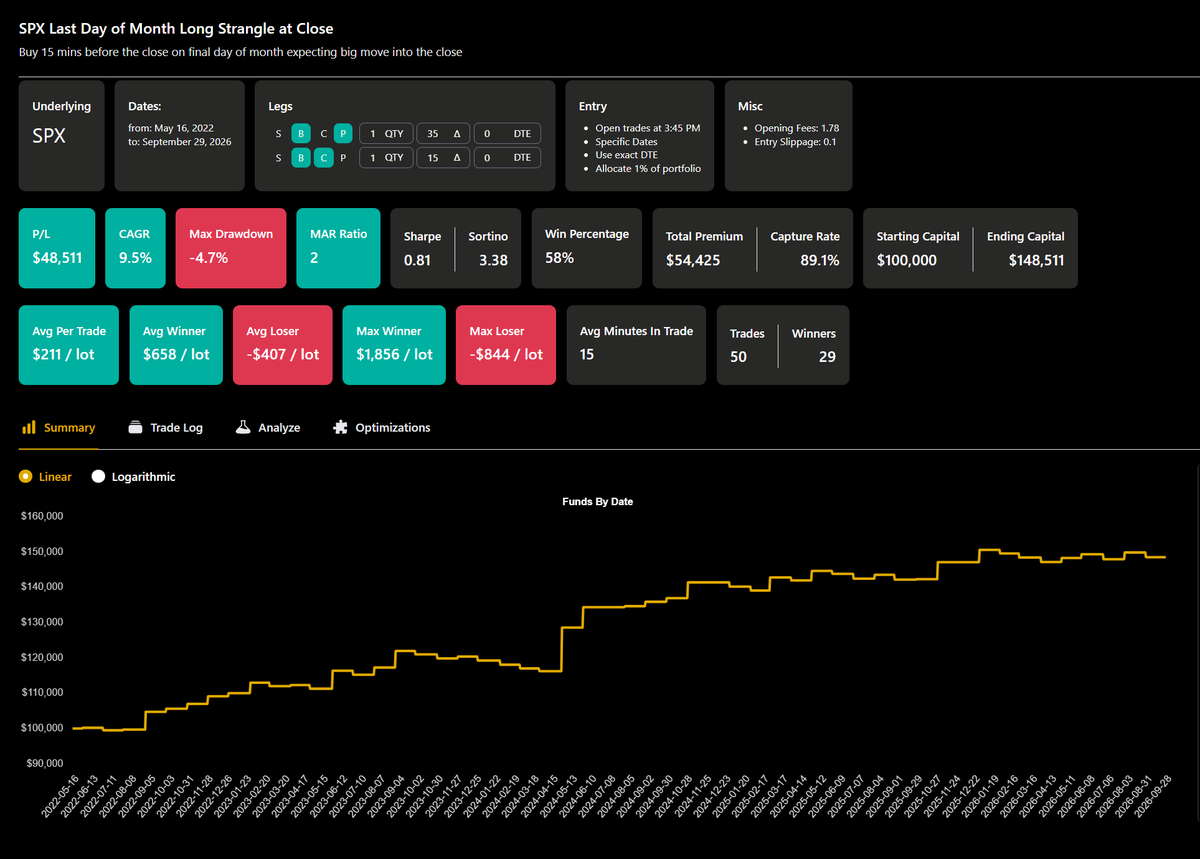
My @OptionOmega backtest for last day of month trade runs an automated SPX long strangle 15 minutes before the close. Cna really pick any deltas you prefer or default to 25 delta on each call/put but this backtest I like higher delta put 35 and a 15 delta call.
This actually has been mixed in 2026 but had a big win last day of August, May and April. Otherwise 2022-2025 had better results.
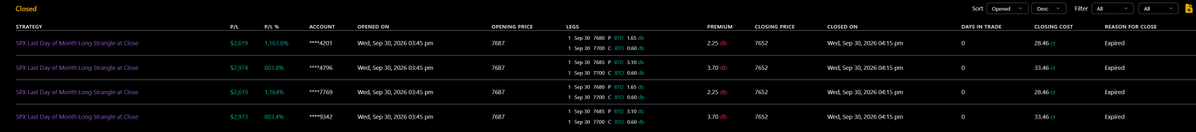
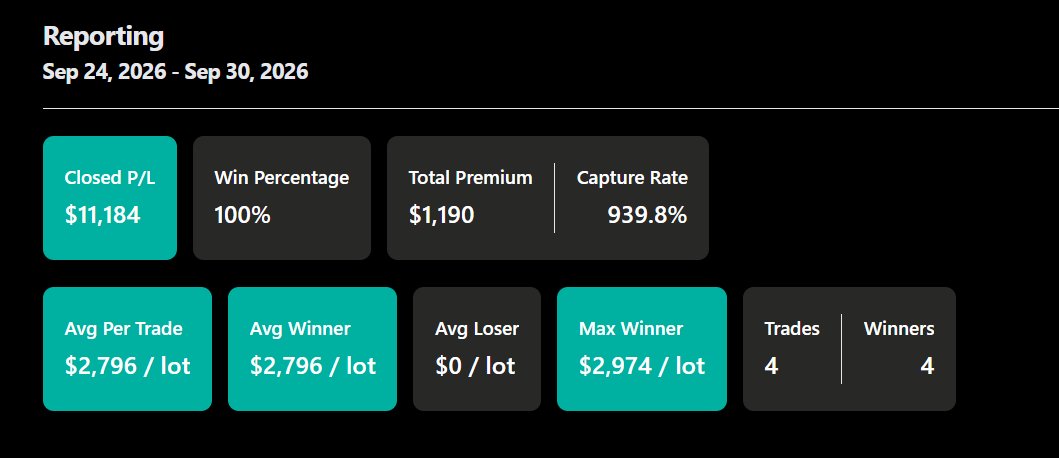
Then today comes and I shared my system bought a 0DTE strangle at 345pm EST with the 7685 puts and 7700 calls for a net debit of $3.70. Those expired at a closing price of $33.46 since SPX closed at $7651.54. 🤑
Also other account bought 7700/7680 strangles for cheaper $2.25 debit and these finished at $28.46 for a gain of over +1160%.
On just 4 lots of these strangles we profited $11,184. This was a 15 minute trade.
I will trade this every month on the final hour of the day and expect it to be a coin flip but historically the backtest going back to 2022 shows positive expected value and a good risk/reward based on Sortino ratio and MAR ratio.
The beauty is that SPX cash settles and you dont have to exit the trade into close. If funds are needing to sell $6 billion of stock or buy that much.. the end of day strangle is likely UNDERPRICED and gamma is the most EXTREME minutes before expiration.. as today clearly showed!
$VOO Vanguard fund rarely sees options flows but when it does its usually spot on long term.
Buyer later in day for 2700x June $750 calls at $24.40 and over $6.5M
theres the end of quarter last 15 minute selloff that is often so common!
Shared some long SPX 0DTE strangles on the premium sub side if anyone followed it should be a nice win
And notice how ES_F flushed down to 7705 into the close with that end of quarter imbalance to sellside.. now already bouncing back over 7725 so could setup the October 1st rally higher but with Jobs report friday it might be what most funds wait for still.