GP/operator in mid-market multifamily and AI data center power. Charts on rates, rents, and grids. Entrepreneurs will build the next decade of real assets.
What it takes to connect a 75MW+ load in Texas now:
Study fee: $100,000
Security: $50,000 per MW, refundable
Queue: ERCOT's Batch Zero review, report due Dec 10
On a 300MW site, that's $15M posted before any power. Capital is the easy part. The calendar isn't.
The US 10-year just had its biggest one-day drop since SVB, and the Bank of Canada is still expected to hike next week. For Canadian multifamily, the overnight rate doesn't set debt cost. The 5- and 10-year Canada bond does. Which one are you underwriting to?
Thursday's 10-year Treasury yield decline of 0.193 percentage point (to 4.952%) is the largest single day yield decline since March 10, 2023, which is the day Silicon Valley Bank failed.
@GregBlackett Agreed. On a fixed 5-year, the overnight rate hits you at renewal, not next month. The GoC 5-year (~3.59%) is the number that sets it.
The variable line is where it bites now. Are you seeing more owners fund capex that way?
Google is paying homes and businesses to use less power so its data centers can plug in. Flexibility is turning into the price of grid access. Texas already wrote it into SB6 for big new loads. How many site plans actually price it in?
Google + Voltus just announced a 1 GW virtual power plant across PJM, Voltus crushed their 100MW phase 1 in 30 days so Google decided to 10x their earlier deal. That's 10% of a 10,000 MW that PJM needs by 2030. Supply chain is ready, so are the 100,000 employees.
LFG
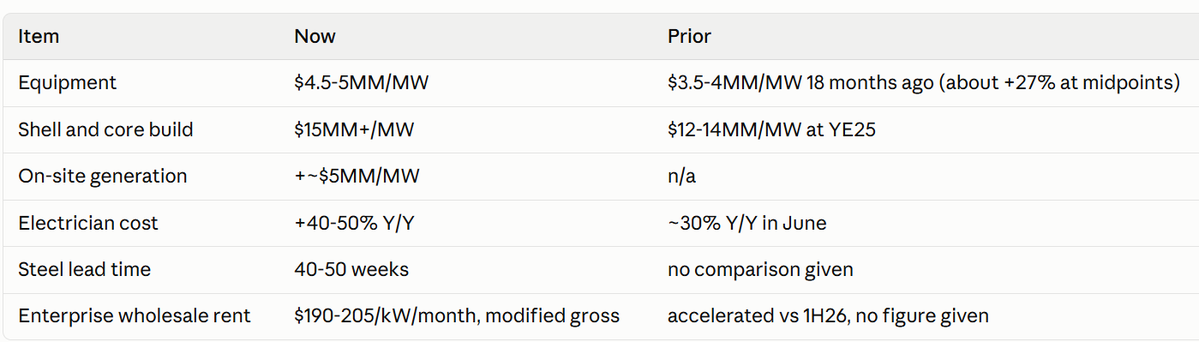
Build cost past $15M a MW, and on-site generation adds about $5M more. That only pencils if it buys months the grid can't. For every self-powered site in Texas: are the months saved worth roughly a third more capex?
Insights from cowen channel check = orders are running far ahead of delivery and costs are moving up.
>Equipment is +27% to $4.5-5MM/MW (from $3.5-4MM 18 months ago) and build cost is above $15MM/MW (from $12-14MM at YE25, roughly +15% at midpoints), with on-site generation adding ~$5MM/MW, electrician pay up 40-50% Y/Y, steel lead times at 40-50 weeks, and the 10-year yield up ~90bps since YE25.
>At the midpoint rent of $197.5/kW/month, revenue is about $2.37M/MW/yr. That is a ~15.8% revenue yield on a $15M build, and ~11.9% if on-site generation adds $5M
>Record 3Q26: ~15.0GW US (~16.9GW global), +70% Q/Q. The ~7.5x is against a 2Q25 base of ~2.0GW, a pre-acceleration quarter, so it flatters the multiple.
>Meta wants an incremental ~6.5GW by YE28, plus 10-40MW edge nodes across 20+ sites. It is over-engineering designs so the chipset decision can come late.
>The active pipeline is ~12.4GW against ~12.5GW in 2Q26. A flat pipeline after ~17GW of global leasing means roughly 17GW of new demand entered in a quarter.
>SpaceX has ~10GW of active requirements, of which ~2-3GW is in Southeast Asia (Indonesia, Malaysia, Thailand, with Thailand less likely given the required JV structure)
Sources:
CMHC, Housing starts and construction data, September 2026: https://t.co/zbDbFu3puV
https://t.co/H6bihmpmy2 & Urbanation, October 2026 National Rent Report: https://t.co/2TGMYdrXfs
CP24/CTV, condo-to-rental conversions, Oct 19: https://t.co/1u0FLTRCUD
CP24, bulk condo purchases (Urbanation Q3), Oct 21: https://t.co/OGKgUyf072
Trump says large data centers should make their own power.
Texas, Sept–Oct:
Data center air permits: paused since Sept 21
SB6: $50k/MW security on 75MW+ loads, and self-generation doesn't reduce it
Washington says build your own. Texas says wait.
Which gives first?
Texas AI power now has three gates, and none of them is capital.
ERCOT audit: report due Dec 10
TCEQ air permits: paused since Sept 21
SB6: $50k/MW security on 75MW+ loads, on-site generation doesn't reduce it
Paperwork keeps moving. Permits don't.
Self-powered sites: one quarter of slip, or two?