@Trader_9Al At this point it’s less about price levels and more about whether real buyers show up. Bounces are easy. Sustained demand is the part that’s missing.
@Trader_9Al The part that stands out is stocks making new highs while crypto keeps bleeding. That used to be where fresh risk appetite showed up first. Not this time.
Market Overview — May 29, 2026
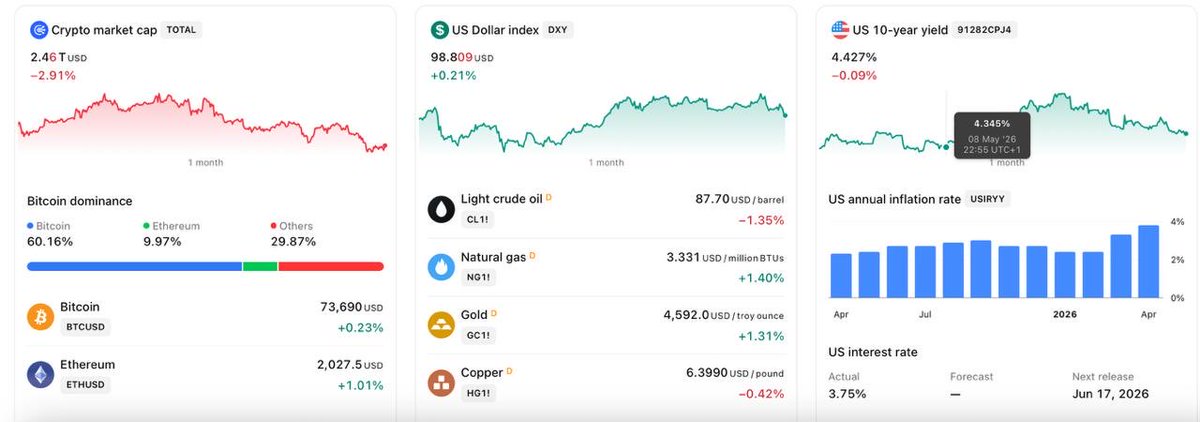
The U.S. stock market approached Friday’s session near its highs. Pre-market futures are trading slightly higher, and the S&P 500 and Nasdaq show no signs of panic following yesterday’s record close. The main reason: the extension of the truce between the U.S. and Iran and the possible lifting of restrictions on shipping through the Strait of Hormuz.
The engine is the same, but the gears have shifted. Although Brent fell below $100 per barrel, inflation is still at 4%, and this has rewritten the entire curve of expectations. The 10-year yield is at 4.4–4.6%, and the 30-year yield has retested its 2007 highs.
From May 26–28, spot Bitcoin ETFs saw a strong net outflow: $1.29 billion in total. In April, ETFs were the main buffer against drawdowns. Now, on the contrary, they have become a source of supply.
The expiration also played out as expected. Ahead of the May expiration on Deribit, the key zone was $75k max pain, with dense call positions above in the $80k–82k range. Bitcoin fell below $73k on massive long liquidations.
The rally in semiconductors and AI infrastructure is following the same trajectory as a week ago. First Micron at $1 trillion, now Snowflake +36.5% and Dell with 181% growth in the data center segment.
It’s the same story: capital freed from oil risk is flowing not into crypto, but into AI. This rotation is simply continuing.
The VIX is around 15–17—a low reading given the current news flow. I get the impression that volatility traders are being shaken out through a careful rotation between sectors.
The U.S. stock market, based on its internal fear metrics, is completely calm. These are short-term jitters driven by headlines, not structural fear.
#Markets #StockMarket #SP500 #Nasdaq #WallStreet #Investing #Trading #Macro #MacroEconomics #Economy #Inflation #Bonds #TreasuryYields #VIX #RiskOn #Oil #Brent #Iran #Bitcoin #BTC #Crypto #BitcoinETF #ETFs #Deribit #Options #AI #ArtificialIntelligence #Semiconductors #Micron #Snowflake #Dell #DataCenters #TechStocks
@Trader_9Al Money leaving oil isn’t automatically finding its way into crypto. Right now it’s chasing whatever can still show growth and numbers to back it up.
#SpaceX IPO Update
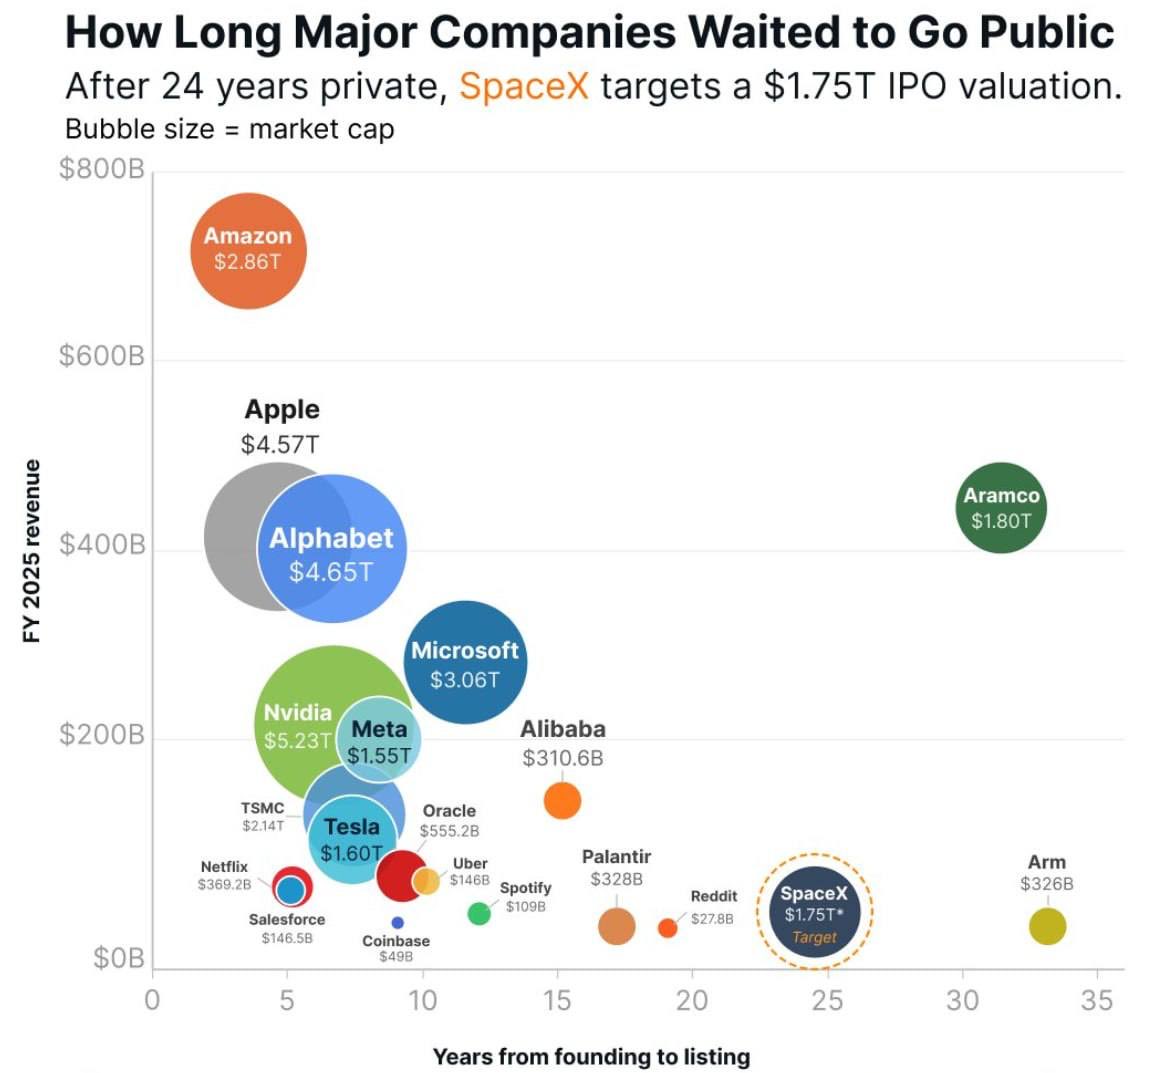
SpaceX (after merger with xAI) is preparing for an IPO in June 2026 with a target valuation of $1.5–2 trillion — potentially the largest in history.
2025 financials:
• Revenue ~$18.7B (+33% YoY)
• Starlink (connectivity): $11.4B (~61% of revenue) — main growth and profit driver
• Launches & government contracts: ~$4B
• AI/xAI: ~$3.2B (still unprofitable)
Starlink has >10M subscribers, but ARPU is declining as it expands into mass markets.
At $1.75T valuation, SpaceX would rank in the global top 10, close to Tesla (~$1.6T), but far behind Nvidia ($5T+), Alphabet, and Apple. The P/S multiple is extreme: 90–125x 2025 revenue.
**Bull case:** Starship succeeds, radically lowers launch costs, Starlink becomes a global monopoly with direct-to-cell, new markets (orbital data centers, point-to-point transport). Musk premium + AI/space hype could drive a massive initial pop.
**Bear case:** The valuation assumes decades of 40%+ CAGR — almost unprecedented. High capex, regulatory risks (FAA/FCC), competition (Amazon Kuiper, China), and AI losses could lead to a sharp correction.
For the valuation to hold post-IPO (and survive 2–3 month lock-up):
- Successful Starship tests + rapid reusability
- Starlink subscriber growth to 20M+ by end-2026 + margin stabilization
- Bullish tech/AI market sentiment, no recession
- Strong execution and clear “platform company” narrative
Conclusion: The IPO will likely be hype-driven (private market already values it at $800B–$1.25T). But sustaining it will be very difficult without concrete Starship progress. Classic high-risk “story stock” — huge upside if everything clicks, 30–50%+ downside if it doesn’t.
Focus on execution, not just vision.
#SpaceX #SPCX #Starlink #Starship #IPO #cryptocurrency
Market Overview – May 25, 2026 (Memorial Day Edition)
The U.S. stock market closed its eighth consecutive green week.
Against $100+ oil, a new Fed chair, and the Iran conflict, this looks like “strength.”
In reality, it’s the momentum of an extremely strong earnings season, trend-following algos, and the perception that U.S. stocks currently offer the best risk/reward.
Q1 earnings were impressive:
• S&P 500 earnings growth +28.4% YoY
• Revenue growth +11.6%
• 84% of companies beat EPS estimates
• 81% beat revenue estimates
This is the best earnings growth since Q4 2021.
Capital is flowing into markets with good liquidity, regulation, hedging tools, and investor protection. In this environment, crypto falls short on almost every front. Bitcoin is trading as a classic cyclical risk asset with long duration and high sensitivity to real yields.
1/ Macro Pressure
10-year UST holding 4.55–4.70%.
DXY at 99.32 and heading toward 100.
This puts pressure on non-US assets and commodities.
Gold and crypto correlation is rising this spring — both are declining as the dollar strengthens.
2/ Bitcoin & Liquidity Narrative
The popular “BTC moves with liquidity” thesis is facing a reality check.
In January the market priced 3–4 Fed cuts in 2026. By March it was down to 2. By early May even one cut was in doubt.
Last week the market started pricing in the possibility of a rate hike for the first time since fall 2024.
On May 22 Kevin Warsh became the new Fed Chair. Trump is publicly pushing for rapid cuts, while Warsh has historically been more hawkish than Powell. This contradiction adds uncertainty.
3/ Low Volatility Illusion
VIX = 16.70 (historically should be 22–25 in such conditions).
Bitcoin realized volatility (BVIV) = 38% — 7-month low.
The market has entered a paradoxical consensus: institutions are selling volatility en masse to generate yield in a sideways market. This artificially suppresses VIX and crypto volatility, creating an illusion of safety. Low volatility encourages systematic funds to add leverage.
4/ Crypto Specifics
Coinbase Premium Index has been deep in the red since May 6 — US investors actively selling on spot.
Spot Bitcoin ETFs: 6 consecutive sessions of outflows (~$1.26B).
Strategy is preparing the market for potential BTC sales.
Sentiment has dropped back into the fear zone.
Paradox: BTC remains relatively stable despite all this pressure.
Conclusion:
The market is in a state of “apparent calm amid structural risks.”
Crypto was sold off last week even as stock indices rose because its main narrative (“Trump-friendly Fed cuts”) completely fell apart.
We are waiting for new narratives and drivers. They will appear soon.
#Bitcoin #Crypto #Markets #Macro #ETF #Fed #Oil
Over $1.5 billion in long positions were liquidated over the past two days
Over 200,000 traders have been affected by this in the last 24 hours
The largest liquidation order occurred on
Bitget-BTC and amounted to $32.44 million
Meanwhile, U.S. stock indices closed in the green on Friday, near all-time highs.
The hunt for liquidity in the crypto market continues in the absence of new drivers.
I expect stabilization over the weekend
Trading ranges
BTC 74 - 77k
ETH $1,960 - $2,200
SOL $78 - $88
HYPE $50 - $60
BNB $620 - $680
XRP $1.28 - $1.42
@Trader_9Al Feels like crypto is still flushing leverage while equities keep absorbing liquidity. Until a new narrative shows up, market probably stays range-bound and headline-driven.
@Trader_9Al Most people trading this probably don’t realize they’re not buying SpaceX exposure, they’re trading crowd psychology with leverage attached to it.
@Trader_9Al Market tried hard to kill the narrative, but every wave of pressure just brought more buyers in. That’s usually not how weak assets behave.
@Trader_9Al Another correlation break. Software ripping higher while BTC tanks again. Full rotation out of chips into the beaten-down SaaS names — both assets are deeply oversold. Curious to see when money starts hunting the next oversold play and flows back into crypto.
The bond yields section really hits — 10Y and 30Y at those multi-year highs are basically running the whole market right now.
On BTC, spot on. Whales accumulating hard, exchange reserves at 7-year lows, while retail is once again writing the “it’s dead” obituary. Same script, different cycle.
Main priority for me too: just protect capital until DXY drops below 98. That feels like the real trigger.
Watching NVIDIA this week, but I’m way more focused on when bonds finally catch a break
What’s really changing here is perception.
For years, markets were conditioned to buy every dip assuming liquidity would always come back. Now high yields, expensive oil and geopolitical risk are all hitting at once.
And BTC trading like another high-beta tech asset instead of an inflation hedge is probably the biggest signal of all.
@Trader_9Al ZEC holding up while BTC drops 6% right after a major mainstream narrative push is probably not a coincidence.
Feels less like random strength and more like carefully built liquidity after years of accumulation.
What stands out most is that even gold sold off in this environment. That usually tells you the market isn't pricing narratives right now — it's pricing liquidity, real yields, and dollar strength.
And when even BTC starts trading more like high-beta tech than “digital gold,” macro clearly remains in control.
Next 2 weeks should be very telling.
Weekly Market Overview – May 11-17, 2026
The past week clarified several macro themes, and crypto once again proved to be one of the most sensitive risk assets.
Bitcoin fell ~6%, Ether -10%, total market cap slipped to $2.55–2.60T.
Classic mechanics: dollar strengthened → yields rose → metals, tech and crypto sold off.
Main trigger: DXY recovered from 97.5 to 99.4.
April inflation (CPI 3.8%, PPI 6.0%) forced the market to revise rate-cut expectations.
10-year Treasury yields climbed to 4.6% — a clear blow to all non-cash-flow assets.
Oil added fuel to the fire.
Brent above $100 and WTI in triple digits brought back fears of a second inflation wave.
Expensive oil → higher inflation → hawkish Fed → stronger dollar → liquidity drain from risk assets.
Gold became the key indicator: even it fell amid inflation and geopolitics.
This shows the market is trading liquidity and real yields, not “safe-haven” status.
The same logic hit Bitcoin — the “digital gold” narrative temporarily gave way to Nasdaq-beta behavior.
Equities: pressure came from tech.
AI, semiconductors, high-multiple software and unprofitable growth names were already overheated.
Massive profit-taking followed.
Kevin Warsh officially became the new Fed Chair on May 15.
The market will now hang on his every word until the June FOMC.
Spot Bitcoin ETFs recorded over $1B in outflows this week — the largest since late January.
IBIT, FBTC and ARKB led the selling.
Conclusion:
USD, oil and yields have resumed squeezing the long-duration trade.
Base case:
Bitcoin stays in a broad $76K–$86K range.
The $75K–$76K zone will be tested as key psychological and structural support.
A return above $82K is possible only if DXY stabilizes, yields ease, and Nvidia delivers strong results.
Iran situation and macro data will remain in focus over the next two weeks.
#Bitcoin #Crypto #Markets #Macro #ETF #Oil #Fed