very good update from #websol.
250 MW DCR solar modules from CRI pumps. the key is DCR. this will boost the PAT.
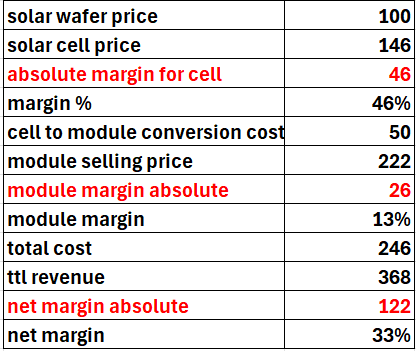
Cell margins are about 46% where as module margins are 13%. The blended margins will go down to 33%. But the profit will go up as I explained in the calculation below. This will be a big big jump for websol in topline and bottomline.
#waareeenergies
More than the results, the guidance is to be appreciated
If a company of this size is expecting at 80 odd percent increase in EBITDA, its clear signal that the sector is poised for super growth
Smaller players especially the ones having higher share of cell revenue will gain more. Good times ahead !
#websol
💼 Waaree Energies Ltd | Mar 2025 Results Out
#WaareeEnergies#SolarEnergy#RenewableEnergy#Growth#Manufacturing#IPO
Strong Performance & Growth Momentum 🔥
📊 Key Metrics
Revenue (REV):
📅 Mar 2025: ₹4003.93 Cr
📅 Dec 2024: ₹3457.29 Cr
📅 Mar 2024: ₹2935.84 Cr
📉 ⬆️15.81% QoQ, ⬆️36.38% YoY
Profit Before Tax (PBT):
📅 Mar 2025: ₹845.46 Cr
📅 Dec 2024: ₹689.81 Cr
📅 Mar 2024: ₹658.61 Cr
📉 ⬆️22.56% QoQ, ⬆️28.37% YoY
Profit After Tax (PAT):
📅 Mar 2025: ₹644.47 Cr
📅 Dec 2024: ₹506.88 Cr
📅 Mar 2024: ₹475.16 Cr
📉 ⬆️27.14% QoQ, ⬆️35.63% YoY
🤖 Key Insights:
📌 Robust Q4 PAT at ₹644 Cr (+27% QoQ, +36% YoY) concluded a strong FY25 with ~51% annual PAT growth, highlighting excellent execution despite some sequential margin pressure noted earlier. 🔥
📌 Aggressive capacity expansion is key: 5.4 GW cell plant (Gujarat) commissioning, 1.6 GW module line live in USA, and a massive 6 GW integrated plant planned in Odisha using IPO funds (~₹2,775 Cr earmarked). 🏗️💰
📌 Strategic diversification efforts are clear with the proposed acquisition of Enel Green Power India's renewable assets, aiming to move beyond pure manufacturing. Also exploring green hydrogen, electrolysers, and storage. 👀
📌 Management seems confident navigating potential US tariff impacts, likely leveraging its new US manufacturing base (1.6 GW) and supply chain flexibility. ✅
📌 Fundamentally strong growth backed by sector tailwinds (Govt push, demand). However, important to monitor working capital (noted rise in other current liabilities) and execution risks associated with large capex. Overall outlook appears positive. 🏦⚠️
🔗 Link: https://t.co/yB9Er8froF
🔔 Subscribe. Stay Ahead: https://t.co/TLwFJRGwV5
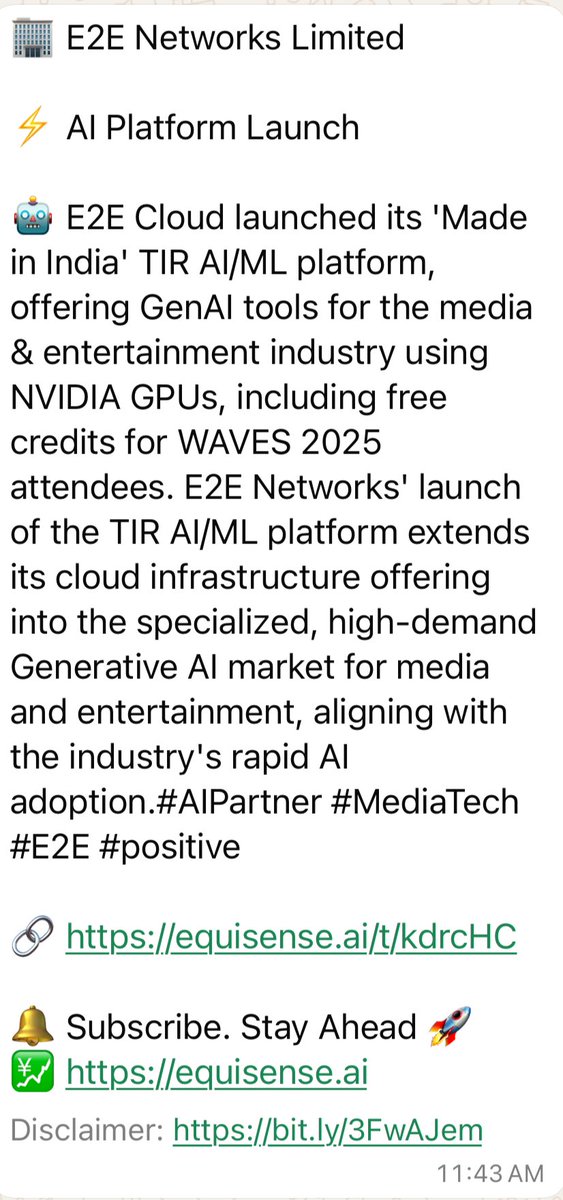
💼 E2E Networks Limited | Mar 2025 Results Out
#E2ENetworks#E2E#CloudInfra#AICloud#Growth#Valuation
Mixed Performance 😐
📊 Key Metrics
Revenue (REV):
📅 Mar 2025: ₹33.48 Cr
📅 Dec 2024: ₹41.60 Cr
📅 Mar 2024: ₹29.41 Cr
📉 🔻19.54% QoQ, ⬆️13.83% YoY
Profit Before Tax (PBT):
📅 Mar 2025: ₹17.59 Cr
📅 Dec 2024: ₹15.53 Cr
📅 Mar 2024: ₹5.57 Cr
📉 ⬆️13.23% QoQ, ⬆️215.58% YoY
Profit After Tax (PAT):
📅 Mar 2025: ₹13.61 Cr
📅 Dec 2024: ₹11.59 Cr
📅 Mar 2024: ₹3.53 Cr
📉 ⬆️17.41% QoQ, ⬆️285.93% YoY
🤖 Key Insights:
📌 PAT showed strong YoY growth (+286%), but revenue dipped nearly 20% QoQ, raising questions about demand sustainability or execution alignment with expansion plans. 👀
📌 Reported profits appear significantly boosted by interest income on funds raised (~₹12.79 Cr other income in Dec 2024 Qtr vs ~₹0.86 Cr in Sep 2024 Qtr), masking potential pressure on core operational profitability. Scrutiny needed. ⚠️
📌 Massive capex (~₹800 Cr+ planned for FY25, high CWIP noted) funded by preferential issues strengthens infra but carries significant execution risk. Monitoring project completion and revenue generation is key. 🏗️
📌 Balance sheet strengthened post-fundraising, nearly eliminating debt, but a sharp rise in 'Other Current Financial Liabilities' (user noted ₹876 Cr) requires clarification on its nature and implications. 🏦
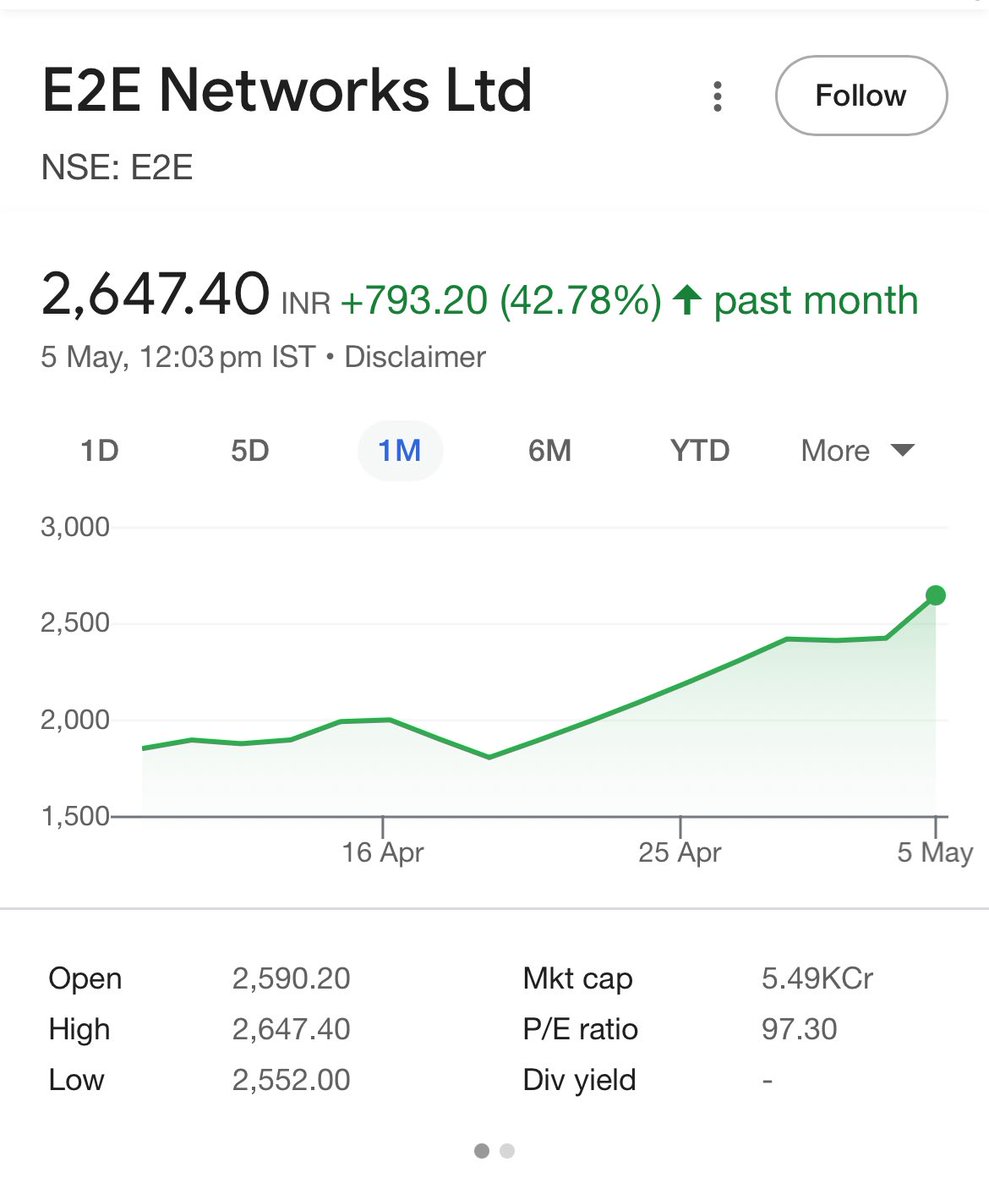
📌 Valuation seems high with a TTM PE around 48.6 (based on calculated TTM PAT) and market sources citing even higher current PE (~100+), well above historical median (~26) and industry averages, reflecting high growth expectations. 💰
🔗 Link: https://t.co/XND297sfXa
🔔 Subscribe. Stay Ahead: https://t.co/TLwFJRGwV5