*UNITED IN SOLIDARITY!*
*The struggle to save IDBI Bank is a collective struggle of the entire banking fraternity!*
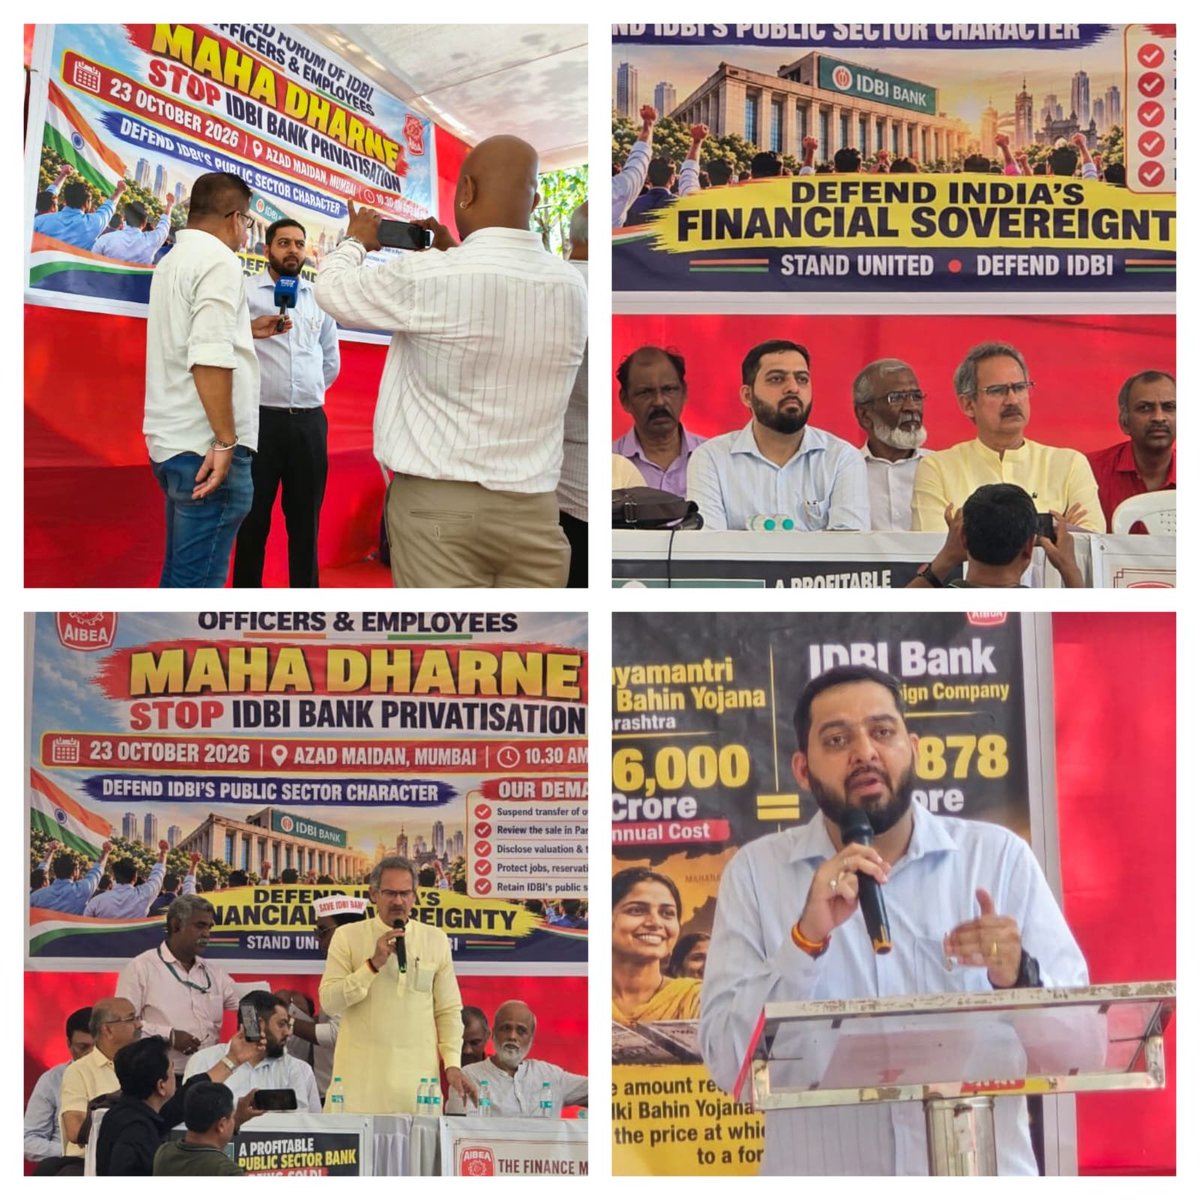
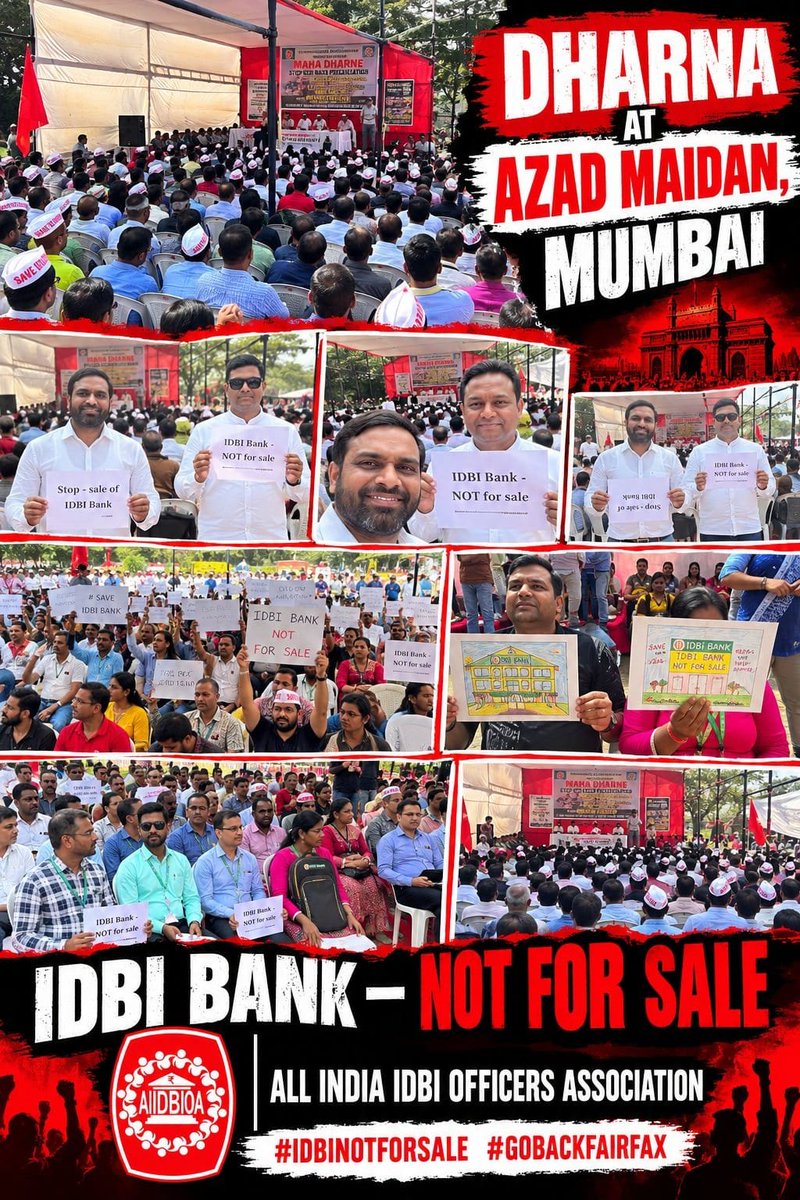
In a powerful expression of unity, commitment and collective resolve, We extended AIBOC’s wholehearted solidarity and moral support to the officers and employees of IDBI Bank at the *Maha Dharna held at Azad Maidan, Mumbai, on 23rd October 2026,* opposing the proposed privatisation of the Bank.
Standing shoulder to shoulder with our fighting employees, we reaffirmed that the struggle to protect IDBI Bank’s public sector character is not merely the concern of its employees, but a *collective responsibility of the entire banking fraternity* to safeguard public sector banking, protect employees’ livelihoods and preserve institutions built on public trust.
*Shri @ianildesai Ji, Hon’ble Member of Parliament, Shiv Sena (UBT),* also visited the dharna and extended his support. He further *assured the gathering that the issue would be raised on the floor of Parliament*, providing an important platform for the concerns of IDBI Bank officers and employees to be brought before the nation’s highest legislative forum.
**Our strength lies in our unity. Our resolve lies in our solidarity. Our responsibility lies in protecting the future of public sector banking.**
Today, we stand firmly with our comrades at IDBI Bank, united by the conviction that no struggle for a just cause should ever be fought alone. The collective voice of banking officers and employees is a powerful expression of our shared commitment to institutional integrity, public trust and the future of our banking system.
🔥 *TOGETHER WE STAND*.
*TOGETHER WE FIGHT.*
*TOGETHER WE SHALL DEFEND PUBLIC SECTOR BANKING!*
**SAVE IDBI BANK — SAFEGUARD THE PUBLIC SECTOR BANKING LEGACY!**
#SaveIDBIBank #DefendPublicSectorBanking #BankingUnity #WorkersSolidarity
*In Solidarity,*
*Team FBOIOA*
बिज़नेस सब-स्टैण्डर्ड के एडिटर ने कहा था कि एक दूधिया हर दिन पैसा जमा करता है बैंक में उसके लिए 5 दिन बैंकिंग में काम खराब हो जाएगा, पर वही एडिटर @AshokAkaybee तब क्यों चुप हो जाता जब निजी बैंक 3 से ज्यादा कॅश डिपाजिट करने पे चार्जेज लगा देता है।
ये पत्रकारिता है या... !!?
Post No.253#GOBACKFAIRFAX
WE, THE EMPLOYEES OF IDBI BANK, OPPOSE PRIVATISATION!
IDBI Bank is not just a financial institution,it is our livelihood, our professional identity, and a legacy built through decades of dedicated service @KTRBRS@BRSparty
भाग 2: आपका मोबाइल रिचार्ज, एक कहानी जो हर महीने आपकी जेब से गुज़रती है
पिछली बार मैंने पूछा था कि आपका मोबाइल रिचार्ज कितना बदला।
2016 से पहले याद कीजिए। Aircel, Telenor, Tata Docomo, Reliance Communications जैसे कई नाम थे। गली की हर दुकान पे अलग अलग कंपनी का बोर्ड लगा रहता था। फिर मुफ़्त डेटा की जंग शुरू हुई, और कुछ ही सालों मे ये नाम या तो बंद हो गए या किसी बड़ी कंपनी मे मिल गए।
जब मैदान मे खिलाड़ी कम हुए, तो रिचार्ज बढ़ने लगा। दिसंबर 2019 मे करीब 40% तक, दिसंबर 2021 मे करीब 20%, और जुलाई 2024 मे फिर 12 से 25%। जिओ का सबसे सस्ता महीने वाला प्लान ₹155 से ₹189 हो गया।
आज अगस्त 2026 के TRAI आँकड़े देखिए: जिओ 39.3%, एयरटेल 38%, Vi 15.4%, और सरकारी BSNL सिर्फ़ 7.2%। यानी 100 मे से 77 मोबाइल दो कंपनियों के पास।
अब असली बात। Vi जब डूबने लगी, तो मार्च 2025 मे सरकार ने उसके ₹36,950 करोड़ के बकाए को शेयर मे बदल दिया। आज सरकार Vi की 48.99% मालिक है, पर कंपनी चलाने का अधिकार अभी भी प्रमोटर के पास है। सोचिए, घाटे का बोझ जनता के पैसे पर, और चलाने की चाबी किसी और के हाथ मे।
अगले भाग मे बताऊँगा कि यही कहानी बैंकिंग मे कहाँ तक पहुँच चुकी है।
तब तक आप बताइए: आपके फ़ोन मे BSNL का सिम है? नही है, तो क्यों छोड़ा? सच्चा जवाब दीजिए, यही अगली कहानी की नींव बनेगा।
रहीम ने कहा था,
रहिमन देखि बड़ेन को, लघु न दीजिए डारि।
जहाँ काम आवे सुई, कहा करे तरवारि॥
पढ़ेगा इंडिया, तभी तो बढ़ेगा इंडिया।
#पढ़ेगा_इंडिया_तभी_बढ़ेगा_इंडिया #PadhegaIndiaBadhegaIndia
If the previous wave of foreign banks building out India franchises went badly wrong, the new wave is more about ‘buy, don’t build.’
That doesn’t assure success though.
Will the new wave of foreign bank investments lead to a meaningful share of India banking in the hands of foreign owned / controlled enterprises? That’s what we should be watching for after the big wave of foreign investment in Indian financials.
This week’s India File:
https://t.co/OKYpkXYtbx
गतांक से आगे…
बैंक मजबूत हुए हैं तो ग्राहकों का डेटा लीक कैसे हो रहा है?
संदर्भ :
शनिवार को पूछी गई हमारी निम्नांकित प्रश्नावली:
बारह साल, बारह सवाल
1. बैंक मजबूत हुए हैं तो फिर बेचे क्यों जा रहे हैं?
2. बैंक मजबूत हुए हैं तो ग़रीब जनता के खाते से पैसे क्यों काटे जा रहे हैं?
3. बैंक मजबूत हुए हैं तो बार-बार केवाईसी के नाम पर जनता के पैसे देने से इंकार क्यों किया जा रहा है?
4. बैंक मजबूत हुए हैं तो उन लोगों को पकड़कर देश में लाकर सज़ा क्यों नहीं दी जा रही है, जो बैंको से खरबों का लोन लेकर भाग गये हैं?
5. बैंक मजबूत हुए हैं तो फिर ग्रामीण इलाकों में ब्रांच और ATM बंद करके जनता को कैश के लिए क्यों भटकाया जा रहा है?
6. बैंक मजबूत हुए हैं तो फिर किसानों, छात्रों और छोटे दुकानदारों को बिना बिचौलिये और बिना गारंटर के लोन क्यों नहीं मिल रहा है?
7. बैंक मजबूत हुए हैं तो फिर साइबर ठगी का शिकार हुए गरीब आदमी का पैसा तुरंत वापस क्यों नहीं होता, उसे थाने और बैंक के चक्कर क्यों कटवाए जाते हैं?
8. बैंक मजबूत हुए हैं तो फिर होम लोन और शिक्षा लोन पर ब्याज इतना ज़्यादा क्यों है कि आम आदमी की कमर टूट रही है?
9. बैंक मजबूत हुए हैं तो फिर डिजिटल ट्रांजेक्शन फेल होने पर जनता का पैसा कई-कई दिन तक होल्ड पर क्यों रखा जा रहा है?
10. बैंक मजबूत हुए हैं तो फिर CIBIL स्कोर में छोटी सी चूक पर नौजवानों को डिफॉल्टर बताकर उनका भविष्य क्यों खराब किया जा रहा है?
11. बैंक मजबूत हुए हैं तो फिर बुजुर्गों और अनपढ़ लोगों को UPI और ऑनलाइन फ्रॉड से बचाने के लिए हर ब्रांच में सहायता काउंटर क्यों नहीं है?
12. बैंक मजबूत हुए हैं तो बैंक कर्मियों की जायज़ माँगे क्यों नहीं मानी जा रही हैं और बैंकों में नई भर्ती क्यों नहीं हो रही और मौजूदा कर्मचारियों पर इतना दबाव क्यों है कि ग्राहक सेवा ही चौपट हो रही है?
@DFS_India
Read Prof. Arvind Panagariya's piece in ET today, "Pivot to Privatisation 2.0". With all respect to the Chairman of the 16th Finance Commission, I did not need a single outside fact to answer it. His own article does the job!
He says there is "enormous wisdom in transferring the bank to private hands now, when its healthy books enable it to attract buyers". Healthy books made by whom? By his own figures, gross NPA fell from 21.25% to 2.32% and CRAR rose from 10.7% to 26.65% while LIC and the Government owned the bank. So the "healthy books" are the proof that public ownership worked, not a reason to end it.
He says it is best to close or sell PSBs "that regularly drain government finances". His own article says IDBI made a record profit of ₹9,513 crore in 2025-26. By his own test, IDBI does not even qualify for sale!
He says repeated support "amounts to throwing good money after bad". His own numbers: GoI put in ₹27,441 crore and LIC ₹26,367 crore. That money did not go waste, it built a bank earning ₹9,513 crore a year. Good money after bad is when the patient dies. Here the patient walked out of the hospital, and we are selling him at the gate.
He says GoI and LIC, with 15% and 19%, "stand to share in the benefits almost certain to accrue". If the benefits are almost certain, why sell 60.72% of them? And the sale brings ₹52,879 crore against roughly ₹53,800 crore of public money put in. Where is the fiscal gain?
He says worker and wage concerns "lacked empirical support", citing a study of 14 Vajpayee-era privatisations. Not one of them was a bank. And if he is so sure employees will be better off, the government should have no hesitation in giving IDBI staff written statutory protection. The union is asking for exactly that.
He compares it with Air India, sold with ₹61,000 crore of debt settled at taxpayers' expense. IDBI carries no such burden. One was bleeding, the other is earning.
His subheading says "non-strategic PSBs", yet his own last paragraph lists "banking, insurance and financial services" among the four strategic sectors of the 2021 policy, and his own caveat says "provided national security or strategic concerns are not at stake". So we must ask, who examined that before handing an Indian bank to a foreign group?
In 2018 I wrote about "अश्वत्थामा हतः" and how nobody hears "नरो वा कुंजरो वा". Today also, "biggest FDI" is announced loudly, while the turnaround under public ownership is said softly. And in December 2003 Parliament was assured majority ownership would stay. "रघुकुल रीति सदा चलि आई। प्रान जाहुँ बरु बचनु न जाई॥"
Keep 51%.
@DFS_India@narendramodi@nsitharaman
The Sale of IDBI: Fatten on Public Money, Then Gift Back to Private Sector
Amid the rhetoric of self-reliance, why transfer control of a public financial institution to a foreign group? asks @DTuljapurkar
https://t.co/WHeqTUY8ln
DIPAM claims discussions were held, but UNIONS say no such discussions took place.
How can DIPAM and the Finance Ministry sell a Public Sector Bank without even discussing it with the employees and officers’ unions?
How can they take such a big decision affecting thousands of employees and their families without even hearing their views?
For the bhakts who are seeing foreign funding in the CJP movement;
Canada's Fairfax buying IDBI is what foreign funding looks like.
IDBI was an iconic institute created in the times of Nehru, which was instrumental in creating the following key institutions of modern India:
Nehru created IDBi
It gave us
1) SIDBI (Small Industries Development Bank of India )
2) NSE ( National Stock Exchange)
3) National Securities Depository Limited (NSDL)
4) Export-Import Bank of India (EXIM Bank):
5) Entrepreneurship Development Institute of India (EDII)
6) Securities and Exchange Board of India (SEBI)
7) CARE Ratings (Credit Analysis & Research Ltd)
8) Stock Holding Corporation of India Ltd. (SHCIL)
9) Technical Consultancy Organisations (TCOs)
10) Clearing Corporation of India Ltd. (CCIL)
It is being undervalued.
Why this favor for a Canadian company?
Is their a personal or party benefit ?
इतिहास से सबक: Hindustan Zinc की कहानी, और IDBI पर उठते सवाल
आजकल IDBI बैंक की बिक्री के पक्ष में एक उदाहरण बहुत दिया जा रहा है, Hindustan Zinc का। कहा जाता है कि देखिए, 2002 में सरकार ने इसे बेचा और कंपनी कितनी आगे बढ़ गई। कंपनी आगे बढ़ी, ये सच है। पर कहानी का दूसरा हिस्सा कम लोग बताते हैं।
मार्च 2002 में सरकार ने Hindustan Zinc की 26% हिस्सेदारी Sterlite (आज का वेदांता समूह) को बेची। इसके करीब बीस साल बाद, 18 नवंबर 2021 को सुप्रीम कोर्ट ने कहा कि उस बिक्री में गड़बड़ी का प्रथम दृष्टया मामला बनता है। कोर्ट ने CBI को regular case दर्ज करके पूरी जाँच करने और हर तिमाही स्टेटस रिपोर्ट देने का आदेश दिया। 2022 में केंद्र सरकार ने खुद कोर्ट को बताया कि CBI ने FIR दर्ज कर ली है।
कोर्ट के सामने जो बातें आईं, वो ध्यान देने लायक हैं। सवाल उठे कि 25% की जगह 26% हिस्सा बेचने का फ़ैसला क्यों हुआ, बोली की प्रक्रिया कैसी रही, और 26% हिस्से का मूल्यांकन कैसे हुआ।
रिपोर्टों के अनुसार strategic sale में asset valuation method इस्तेमाल नहीं हुआ, जबकि Disinvestment Commission ने इसकी सलाह दी थी।
एक और बात। सरकार ने जो करीब 30% हिस्सा अपने पास रखा, उस पर इतना dividend आता है कि सरकार अब बाकी हिस्सा बेचने में जल्दबाज़ी नहीं कर रही। बिक्री के समर्थक भी मानते हैं कि जितने में बेचा था, उससे ज़्यादा सरकार dividend में ले चुकी है। यानी कमाऊ संपत्ति का सही दाम लगाना कितना ज़रूरी है, ये इसी उदाहरण से समझ आता है।
अब IDBI पर आइए।
इस बार सरकार कह रही है कि दो independent valuers लगाए गए, और एक ने asset valuation method भी अपनाया। ये अच्छी बात है, और इसे मानना चाहिए।
Hindustan Zinc से सबक लिया गया है तो उसकी तारीफ़ होनी चाहिए।
पर सबक का दूसरा हिस्सा अभी अधूरा है: पारदर्शिता। वो valuation report आज तक सार्वजनिक नहीं है। बैंक की ज़मीनों और इमारतों की कीमत कितनी आँकी गई, कोई नहीं जानता। Hindustan Zinc का मामला 20 साल बाद अदालत में खुला। क्या हम चाहते हैं कि IDBI के सवाल भी 2046 में किसी अदालत में खुलें?
कबीर ने सही कहा था,
काल करे सो आज कर, आज करे सो अब।
पल में परलय होएगी, बहुरि करेगा कब॥
अभी कोई binding agreement साइन नहीं हुआ है। RBI की मंज़ूरी बाकी है। सवाल पूछने का सही वक्त अभी है, बाद में नहीं।
और जो लोग कहते हैं कि सवाल पूछना विकास का विरोध है, उनके लिए भी कबीर की एक बात,
निंदक नियरे राखिए, आँगन कुटी छवाय।
बिन पानी साबुन बिना, निर्मल करे सुभाय॥
सवाल पूछने वाला दुश्मन नहीं होता, वो व्यवस्था को साफ़ रखता है।
IDBI की पूरी valuation report सार्वजनिक की जाए। संविधान का अनुच्छेद 14 कहता है कि राज्य का कोई फ़ैसला मनमाना न हो। जनता की संपत्ति का हिसाब जनता को मिलना उसका हक़ है।
सत्यमेव जयते।
#IDBINotForSale #SaveIDBI
Till last month, the government was on the back foot. All the bankers were united.
Then something happened on 26th September that was never made public.
Now, the government, which had been trying to sell IDBI Bank for years, has succeeded within 20 days of the deferral of that strike and trying to prove it as a big sign.
Unions became a joke, and bankers are back on the back foot. The 5 day banking week, which many bankers assumed was right around the corner, is nowhere to be seen.
No one is raising their voice.
Wage revision negotiations are expected to begin in the next few months. It will be almost funny this time.
AIBOA Denies Discussions on IDBI Bank Disinvestment, Seeks Correction from DIPAM
Read More: https://t.co/FsMFAsoPMI
All India Bank Officers’ Association (#AIBOA) has disputed #DIPAM’s claim that discussions were held with employee associations regarding IDBI Bank’s disinvestment. In a letter dated 17 October 2026, the association sought a correction to the media statement and reiterated its opposition to the disinvestment of public sector undertakings.
#IDBIBank #saveidbi
A year ago, Rahul Gandhi warned about a closed-door deal on IDBI Bank. Today, Cabinet approval moves the deal forward, without an open debate in Parliament.
Cabinet approval is not public consent. Debate in parliament before handing over a PSB to Foreign hands?