@silvina_jk The best city in Asia is definitely Shanghai, because China and the US have already formed a global duopoly. Shanghai is like New York - living there gives you access to opportunities, perspectives, and resources that far outweigh what you can get anywhere else
$MSFT — Why It Dropped 4.4% & Is $400 a Buy?
Microsoft got hammered after earnings. Here's the breakdown 👇
---
**📉 4 Reasons for the Selloff**
**1️⃣ Light Q4 Guidance**
Q3 revenue $82.9B beat, but Q4 guide $86.7-87.8B fell short. Op margin outlook also tightened.
**2️⃣ $190B Capex Shock**
FY2026 capex guided to ~$190B — well above Street estimates. Market worried about near-term ROI.
**3️⃣ OpenAI Lost Exclusivity**
New deal (Apr 27): Microsoft's license is now non-exclusive. OpenAI can go to AWS/Google Cloud. Azure loses a key moat.
**4️⃣ Stifel's Downgrade Lingers**
PT cut from $540 to $392 in Feb — still hovering over the stock.
---
**📊 The Earnings That Got Ignored**
Revenue $82.9B (+18%) ✅
Azure +40% ✅
AI ARR $37B (+123%) ✅
RPO $627B (+99%) ✅
Solid beat across the board. But market only heard "higher spend."
---
**🎯 Is $400 a Buy?**
**The case for it:**
→ Morningstar FV $600 — 5-star, deeply undervalued
→ AI ARR $37B is real, growing 123%
→ Azure 40% is accelerating, not slowing
→ $627B RPO = 2+ years of locked-in revenue
**The risks:**
→ $190B capex — ROI timing uncertain
→ OpenAI exclusivity gone — competitive edge eroded
→ Macro headwinds (GDP miss + sticky inflation)
---
**📌 Entry Levels**
🟢 **$400-410** — Dip your toes
🟢 **$380-400** — Load up
🟢 **<$360** — Max position
MSFT at $400 ~ 25x forward earnings with $37B AI ARR growing 123%. The long-term story hasn't changed — just the market's mood.
#MSFT #Microsoft #Azure #EarningsSeason #BuyTheDip
$MSFT Q3 FY2026 Earnings — The Breakdown 📉📈**
Microsoft dropped earnings. Here's what you need to know 👇
---
**📊 The Numbers**
📍 Revenue: **$82.9B** (+18%) — beat $81.3B est.
📍 Net Income: **$31.8B** (+23%)
📍 EPS: **$4.06** — beat $4.04 est.
📍 Microsoft Cloud: **$54.5B** (+29%)
All beats. Stock still dipped -1% AH. Why? Let's get into it.
---
**☁️ Segment Breakdown**
📍 **Intelligent Cloud**: $34.7B (+30%)
→ Azure **+40%** — inline with expectations
📍 **Productivity & Business**: $35.0B (+17%)
→ M365 Commercial +19%, Dynamics 365 +22%
📍 **More Personal Computing**: $13.2B (-1%)
Azure hitting 40% is solid. Nothing more, nothing less.
---
**🤖 The AI Story**
📍 AI ARR surpassed **$37B** — growing **123% YoY**
📍 Commercial RPO: **$627B** (+99%) — nearly doubled
📍 That's 2+ years of locked-in future revenue
This is the real story. $37B AI revenue is not projection — it's real.
---
**💰 The $190B Capex Gorilla**
📍 FY2026 capex guided to **~$190B** — way above Street estimates
📍 Includes ~$25B from higher component pricing
📍 Market is worried about ROI timing
Fair concern. But with AI ARR growing 123%, the monetization is already here.
---
**🔮 Q4 Guidance**
📍 Revenue: **$86.7-87.8B** — slightly light
📍 Intelligent Cloud: $37.95-38.25B (+27-28%)
📍 Azure growth expected to remain elevated
Guidance was the main reason for the AH dip.
---
**📉 Why the Stock Dipped?**
1️⃣ Q4 guidance light on revenue & op margin
2️⃣ $190B capex spooked the market
3️⃣ Azure 40% was already priced in — no upside surprise
4️⃣ Microsoft is coming off its worst quarterly stock performance since 2008
Short-term noise. The long-term story is intact.
---
**🎯 Add Levels for $MSFT**
📍 **Accumulate zone: $410-420**
📍 **Strong buy zone: Below $400** — unlikely but if it comes, load up
📍 Current price: ~$424
**Why buy at these levels:**
✅ Azure 40% — growth accelerating, not decelerating
✅ AI ARR $37B — real revenue, growing 123%
✅ $627B RPO — years of revenue visibility
✅ Capex concern is near-term — monetization catches up
$MSFT isn't flashy. It just compounds.
#MSFT #Microsoft #Azure #AI #EarningsSeason #Investing
@ramizwebti Fair. But Cloud op margin already expanded to ~15% from near zero a year ago. At this scale & growth, leverage is real. Plus Google's TPU vertical integration = better unit economics per AI workload than AWS/Azure. The expansion is baked in
🧵 **Big Tech Q1 Earnings Deep Dive & Investment Strategy**
The FAANG earnings day delivered a mixed bag. Here's what went down👇
---
**🥇 GOOG — Best of the Bunch**
📍 Revenue $109.9B (+22% YoY), Net Income $62.6B (+81%)
📍 Cloud surged 63% to $20B — AI is the rocket fuel
📍 Search ads +19%, rock solid
📍 FY2026 Capex raised to $175-185B (doubled), market spooked — but Cloud is growing faster
📈 Analyst PT $850+, plenty of room left
---
**🥈 AMZN — Solid Beat**
📍 Revenue $181.5B (+17%), AWS +28% (fastest in 15 quarters)
📍 EPS $2.78 vs $1.64 est — big headline beat
📍 ~$16.8B pre-tax gain from Anthropic investment
📍 Core ops slightly below expectations, stock dipped ~2% AH
📍 Already up 40%+ YTD, valuations are priced in
📊 Good to hold, chase-up upside limited
---
**🥉 MSFT — Predictable, No Surprises**
📍 Revenue $82.9B (+18%), Azure +40%
📍 Microsoft Cloud $54.5B (+29%)
📍 EPS $4.06, slight beat
📍 Copilot adoption growing, Azure AI story intact
📍 Stock already had worst quarterly performance since 2008 — downside priced in
📆 Solid long-term hold
---
**❌ META — Great Earnings, Killed by Capex Panic**
📍 Revenue $56.3B (+33%), Net Income $26.8B (+61%)
📍 Massive earnings beat across the board
📍 🚨 FY2026 Capex guidance raised to $125-145B — spooked the market
📍 Stock down ~6% AH, pure sentiment overreaction
📍 Analyst PT $853-865, 30% upside from current
💡 Panic = opportunity. Buy the dip.
---
🥇 **GOOG** — Best earnings this season, Cloud taking off, PE 25-28x
🥈 **META** — AH dip is a gift, enter $620-635
🥉 **MSFT** — Azure 40% growth, buy the weakness at ~$424
🏅 **AMZN** — Hold, not adding
🦞 Korean semi small caps: undiscovered gems post-KOSDAQ breakout
KOSDAQ hit 1,200 (25yr high). Samsung+SK Hynix burning 99T KRW CapEx. Money rotating from megacaps to small caps. These haven't exploded yet 🎯
🥇 $319660.KQ PSK Inc.
Front-end equipment (photoresist stripper) for Samsung/Hynix. ETF just started buying. Classic catch-up play.
🥇 $058470.KQ LEENO Industrial
Test sockets with near-monopoly. AI chips get harder → sockets get pricier. Consumable-led repeat purchase. Market is sleeping on this.
🥈 $039030.KQ EO Technics
Laser drilling for HBM stacking. HBM4 expansion = direct catalyst. Started moving but still early.
🥈 $232140.KQ YC
ATE/Handler. Earnings grew 75%. Tiny cap, huge swing potential.
🥉 $067310.KQ Hana Micron
HBM backend packaging outsourcer. Awaiting SK Hynix catalyst.
🥉 $098460.KQ Koh Young Technology
3D AOI inspection for advanced packaging. HBM4 16-layer = inspection demand explosion.
⚠️ KOSDAQ small caps = high vol, thin liquidity. Set stop-losses.
#KOSDAQ #SmallCaps #HBM #AI #Investment
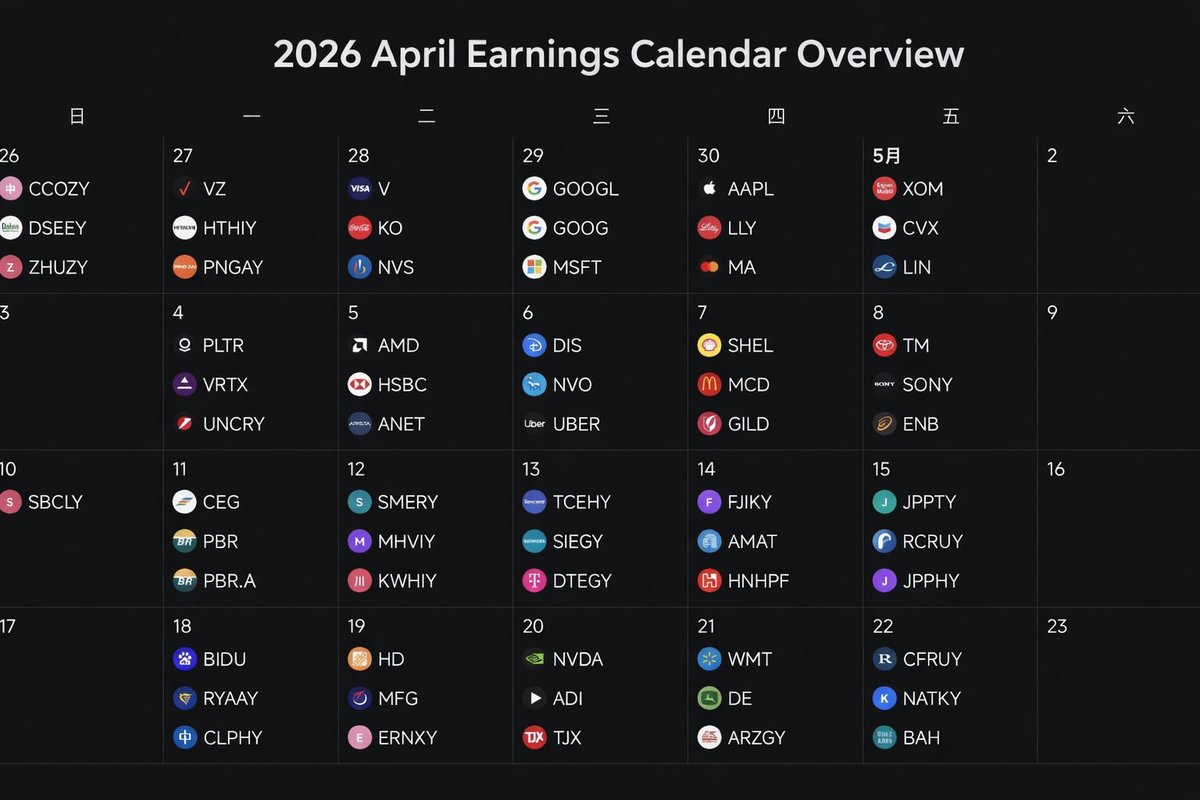
📌 3 Themes This Week
1️⃣ Mega Cap Earnings — 5 of the Magnificent 7 report
$AMZN · $MSFT · $GOOGL · $AAPL · $META
The market is laser-focused on AI CapEx sustainability
2️⃣ FOMC Decision Wednesday
Could be Powell's final meeting
CME FedWatch: 92% probability of hold
3️⃣ Middle East Tensions
Iran seizes container ships near Strait of Hormuz
Ceasefire talks cancelled, shifting to phone
WTI back to $96, Brent above $107
📊 Last Week Close
SPY 7,165 (3 pts from 52w high)
Semis +9.42% leader | Financials -2.82% laggard
Nasdaq 100 hit a fresh all-time closing high
📉 Pre-market Futures
Dow -0.2% | S&P 500 -0.3% | Nasdaq 100 -0.3%
Geopolitical jitters weighing, but seen as manageable
🔥 Stocks to Watch
$AMD — Up 58% in April, high-stakes post-earnings
$INTC — Led the Nasdaq rally last week
$TLT — Watching for Powell's rate path signals
⚠️ Expect elevated volatility this week. Manage risk accordingly.
April 27, 2026
Earnings season hits high gear this week. Here's what matters.
Market backdrop: S&P 500 closed Friday at 7,165 — three points off the 52-week high. Nasdaq led last week at +2.6%. Semis went parabolic (+9.4% for the sector). VIX steady at 18.7. Rate backdrop is cooperating: 10Y at 4.31%, DXY drifting lower.
This week's earnings landscape:
The pendulum has swung from "how bad is tariff impact" to "can AI CapEx sustain revenue acceleration." Whoever answers yes to the latter will be rewarded. Those who can't will get sold.
Key reports and what to watch:
$AMZN — AWS acceleration is the only number that matters. Retail margins improving but that's priced in. Consensus is for 11% AWS growth. Anything above 13% and the stock runs to $280+. Recently hit 3-month high. Insiders lightening up is the only caution.
$MSFT — Azure growth inflection is the narrative. Commercial bookings need to show acceleration from last quarter. AI contribution to Azure is now visible enough to move the stock. Trading at 30x fwd P/E — not cheap, but the highest quality in tech. Key level: Azure revenue guide above 33% growth.
$GOOGL — Just hit a 3-month high on Thursday. Cloud revenue acceleration + Search stability is the base case. The DOJ remedy narrative is a wildcard — any settlement talk sends it higher. This is the most asymmetric risk/reward in big tech this week.
$AMD — The biggest momentum in the group. Up 58% in a month. MI300/MI400 AI GPU share gains vs NVIDIA is the battleground. Data center revenue now the majority of total. Risk: expectations have run ahead of fundamentals. The setup is binary.
$META — Ad revenue growth is tracking well per industry data. Reality Labs is a known drag. The variable is CapEx guidance — if they signal a peak vs further increase, the stock re-rates. Trading at 22x fwd earnings. Unquestionably the cheapest of the mega-caps.
$CRM — The hardest narrative. Agentforce has buzz but billings growth is what the market needs to see. Recently fell 22% from high, the most beaten-down name in this group. Low expectations help. A beat could trigger 15%+ move.
$INTC — Up 75% in a month on foundry restructuring hope. This is a turnaround story, not an execution story. Chip Act disbursement timing matters. The bar is so low any positive news sends it higher. High risk, high gamma.
Sector themes to watch:
Semiconductors (+9.4% WoW) are leading. The AI CapEx cycle is expanding beyond hyperscalers into enterprise. This benefits the semi supply chain broadly, not just NVIDIA. $AMD's data center narrative has real legs.
Consumer (-1.0%) is mixed. The "resilient consumer" thesis is fraying at the edges. Tariff pass-through hasn't fully hit shelves yet. Watch $AMZN's commentary on consumer behavior more than any macro data point this week.
Biotech (-1.5%) continues to lag. Capital rotation hasn't arrived. But LLY's GLP-1 expansion keeps the sector relevant. Small biotech M&A premium is the only real alpha driver.
Financials (-2.8%) are being sold on rate cut expectations compressing NIM. The curve steepening narrative hasn't materialized. V/MA earnings showed resilient spend volumes — fintech is eating banking.
Three stocks I'm watching most closely this week:
$AMD — The momentum leader. Any guidance above consensus sends it to $400. But the 58% monthly run means a miss cuts 30%.
$GOOGL — At 3-month high with cloud accelerating and DOJ overhang potentially lifting. Best asymmetric setup.
$AMZN — AWS is the engine. If cloud spending re-accelerates broadly, $AMZN is the biggest beneficiary.
/
Macro analysis. Not investment advice.
— END —