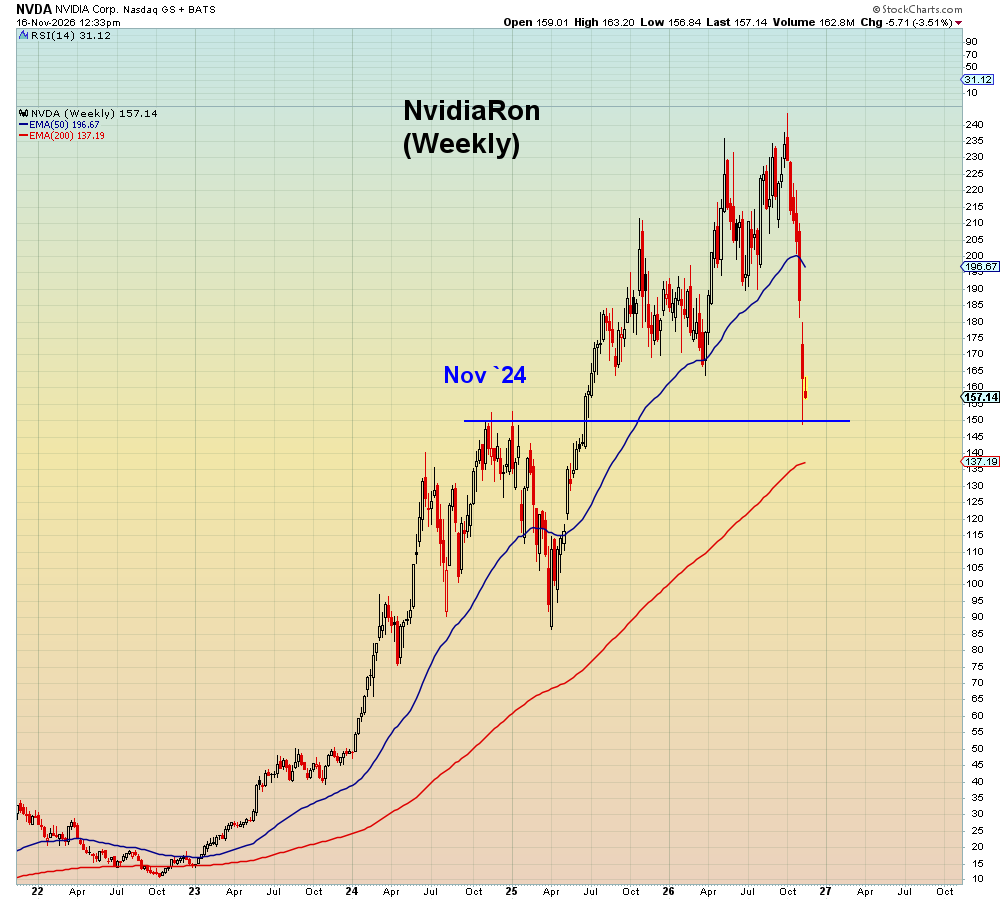
Wall Street knows that once you take all of those illegal sales out of Nvidia's forward sales forecast, the numbers are going to come down bigly.
"Following Enron's massive bankruptcy fraud, Standard & Poor’s selected Nvidia to take Enron's vacant spot in the S&P 500"
They nailed it first time.
This is a very very difficult game that has been on easy mode for years. It quickly shifted to expert mode months ago.
Now that the tide has gone out. You see who is swimming naked. The beautiful thing is the quality accounts are beginning to shine.
Unfortunately making it seem easy is what appeals to the masses when it’s easy.
People dont think in terms of risk/reward. Only reward. Which is what a slot machine player does. You either play this game like a slot machine player or a poker player. There are no long-term successful slot machine players. But there are occasionally some winners!
It's very tough to see people being rag dolled by daily price action and having no plan, no thesis. Just gambling and vibes.
People have constantly promoted gambling to escape the permanent underclass. The ironic thing is that it sent everyone further into the permanent underclass.
Risk management is important. Anyone who was discussing this prior to June was shit on. I was one and and saw it happen to every other person who did.
This cycle exposed how many people think like 🤖 and not just retail
Most people don't do their own research and they outsource conviction. How do you expect to succeed if you are not on and endless pursuit of getting better and challenging your own assumptions? That's who you're trading against.
I see people who mute bears/bulls and I think that's the dumbest thing you can do for yourself. You need to be challenging your own ideas. Confirmation bias is deadly.
Maybe I sound like an asshole. But most people who tell it to you straight do right?
There is money on the line. This is serious. Hearing fairytales that make you feel better may be nice in the moment, but it hurts much more in the long run.
-AC 🕊️
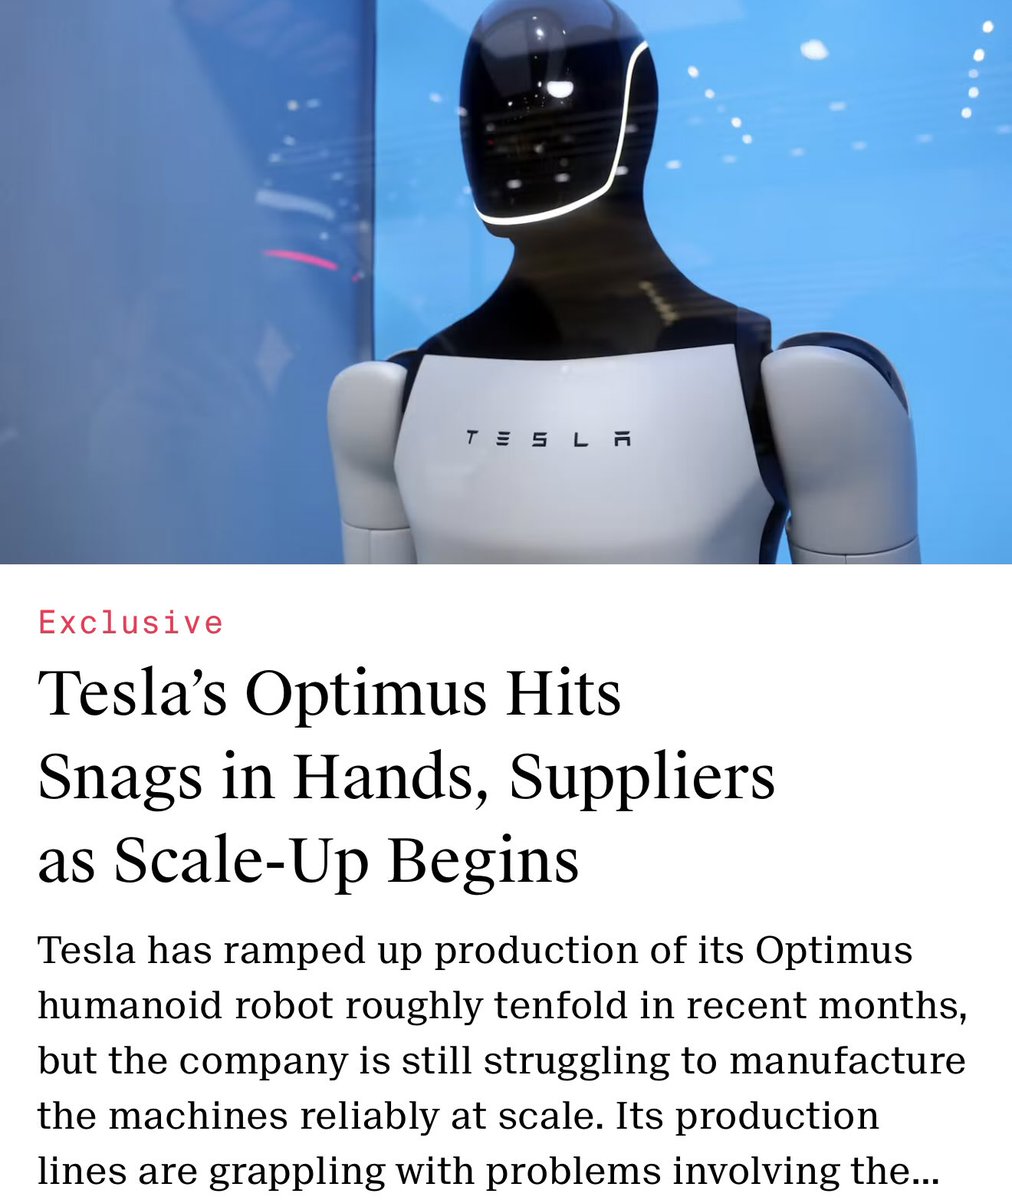
$TSLA has increased Optimus production roughly tenfold in recent months, but is still struggling to build the humanoid robots reliably at scale.
•Hands are a bottleneck: The robot’s intricate hands pose both manufacturing and durability challenges, the report says.
$NVDA earnings were once against fantastic for anyone incapable of/unwilling to read a 10Q.
Revenue grew by $14.6B QOQ, up 18% sequentially.
Accounts Receivable grew by a much larger $22.3B, up 55% sequentially. AR is growing 3X faster than revenue, a major red flag to anyone bothering to look.
Days sales outstanding jumped from 45 days last Q to 60 days. Why are all these "investment grade" customers taking so long to pay their bills?
Debt and equity investments grew by $35.9B, up 126% QOQ. Nvidia is giving their customers more money than ever yet somehow it's taking them much longer to get paid.
Cherry on top: Jensen Huang's bold faced lie on the conference call that tokens are now profitable. He repeated this lie on the Jim Cramer interview.
BTW, if you watched the Jim Cramer interview but did not read the 10Q, I have neither the time nor the crayons required to explain any of this to you.
While everyone is busy commenting on the headline numbers, $NVDA just disclosed in the 10-Q its whole agreement with OpenAI / SB Energy (they should have done a better job redacting the details), revealing many "secrets" of how the whole AI circular financing scheme is working
NVDA $500B fund (not to be confused with funding) consortium plan will not likely age well. Assets of unknown life as collateral for long term debt? Why not do a 30 year ABS deal backed by warehouses of bananas? It’s OK, they’ll be newly engineered bananas of unknown life.
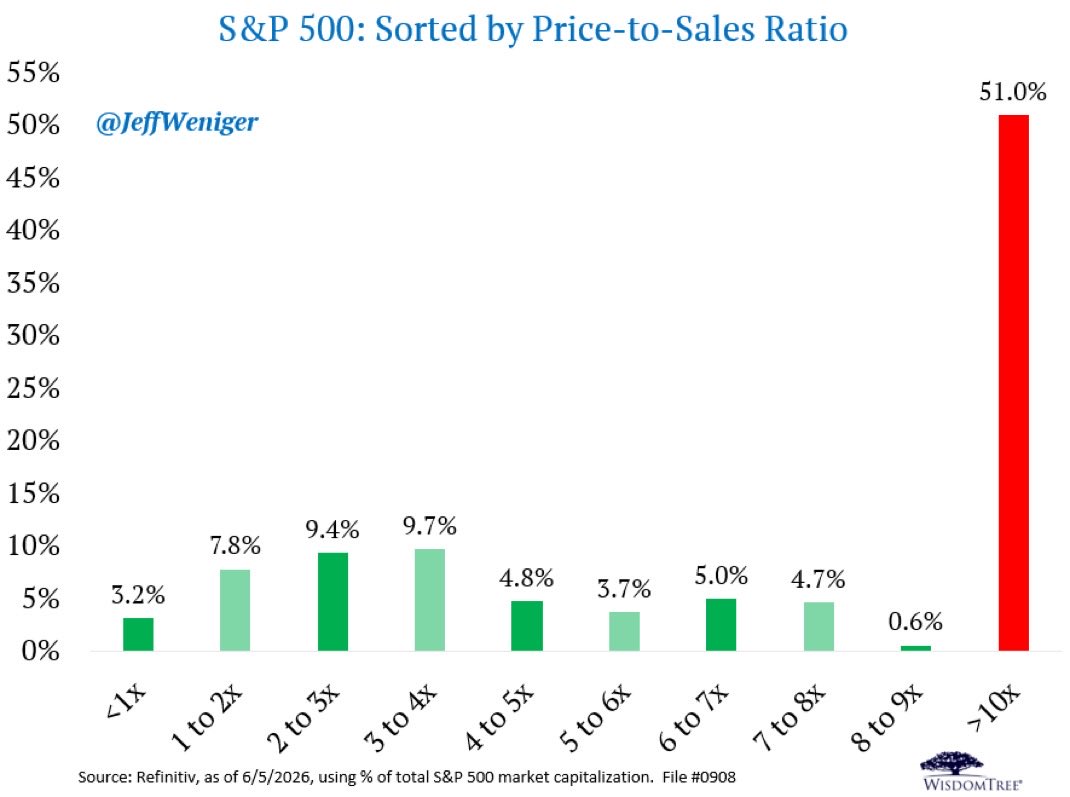
51% of the S&P 500's market cap is in stocks trading above 10x sales.
Half the index.
In 2002, after Sun Microsystems crashed 90%, CEO Scott McNealy famously said this about his own stock at 10x sales:
"At 10x revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. Zero costs. Zero R&D. Zero taxes. Zero employees. What were you thinking?"
He was explaining why investors had been insane to pay it.
Today, half the S&P 500 trades there.
Different decade. Same math.
Wow, this is huge, after months of speculation and the U.S. running a massive pre-emptive discreditation campaign (https://t.co/OYg0rNn9MN), DeepSeek-V4 is finally out!
I haven't studied it in depth but here are the most striking aspects as far as I can tell:
- Fully open sourced with open weights (available for download on huggingface: https://t.co/YMvgMTErcr)
- Zero CUDA dependency anywhere in its stack, which is probably the biggest deal of all. For those who don't know, CUDA is Nvidia's software layer - the foundation nearly every frontier AI model in the world is built on. Except, as of today, DeepSeek V4, which can run entirely on Huawei Ascend chips via Huawei's CANN framework (https://t.co/YLL7kJEYq5). Very concretely it means that China now not only has its own frontier AI models, but its own domestic AI stack, top to bottom.
- The prices are insanely low. V4-Pro is roughly 3x cheaper than GPT-5.5 on input and 8.6x cheaper on output. And V4-Flash is an order of magnitude cheaper still, at $0.14/$0.28 per million tokens vs OpenAI's $5/$30 - so 30-100x cheaper than GPT-5.5 (!). And remember, these are the prices DeepSeek charges on its own API - anyone can download the weights and run them for "free" on their own server.
- It is at or near the frontier on most benchmarks that matter. V4-Pro-Max matches or beats GPT-5.4 and Claude Opus 4.6 on competitive programming (Codeforces rating 3206), coding (LiveCodeBench 93.5), and math (HMMT 95.2, IMO AnswerBench 89.8). It trails the very newest GPT-5.5 and Opus 4.7 on a handful of the hardest agentic and knowledge benchmarks, but it's in the same league.
In effect the value proposition is: "Same league as frontier US AI, at a fraction of the price, open-source and freely modifiable, and hardware-agnostic - you can run it on whatever infrastructure you choose."
Which is insanely good. I now understand the need for a preemptive discreditation campaign: they had every reason to be worried. For the vast majority of use cases, you'd have to be a literal idiot to keep paying OpenAI or Anthropic's prices when this exists.
Last night was the biggest disaster in the history of Tesla.
Let me walk you through what actually happened on that earnings call, because the headlines are doing you a disservice:
Elon Musk got on the call and admitted (his words) that Hardware 3 "simply does not have the capability to achieve unsupervised FSD."
He said he wished it were otherwise. He said the memory bandwidth is one-eighth of what Hardware 4 has. And that's the end of the conversation.
Approximately 4 million Tesla vehicles on the road right now have Hardware 3. Many of those owners paid $8,000 to $15,000 for Full Self-Driving capability based on Musk's repeated promises (going back to 2016) that the hardware was sufficient for full autonomy. As recently as 2022, Musk was publicly assuring owners that HW3 had the processing power to get it done.
BUT IT DIDN'T
Those promises are now officially broken.
The solution is a "discounted trade-in" toward a new car with Hardware 4.
Not a refund or a free upgrade...
A discount on buying ANOTHER Tesla.
Investor Ross Gerber said it too - all HW3 owners got screwed, and with roughly 285,000 FSD purchasers affected, the potential liability runs into the BILLIONS.
But that's not even the worst part.
Musk was asked if the current FSD v14.3 was ready for unsupervised deployment. He said yes. Then immediately walked it back and admitted Tesla has "major architectural improvements" in the pipeline that would significantly improve safety.
What he really means: the software isn't SAFE ENOUGH to deploy without a human watching. Full unsupervised FSD for consumer cars is pushed to Q4 2026. At the earliest... Maybe.
How many times has this deadline been pushed? I've lost count. And trust me, I've seen a lot of broken promises. But this one takes the cake.
Now let's talk about the numbers everyone is celebrating:
Tesla reported $22.4 billion in revenue and $0.41 in non-GAAP earnings. A "double beat." The stock popped 4% after hours. Victory, right?
WRONG
Dig into the actual filing:
The number one driver of operating income improvement wasn't cost reductions, wasn't volume growth, wasn't FSD revenue. It was - and Tesla listed this FIRST in their own shareholder letter - "one-time benefits related to warranty and tariffs."
They released warranty reserves. They booked tariff refund windfalls. They stretched supplier payments by 10 days. They took on billions in new debt. Then they presented everything through non-GAAP metrics that strip out over $1 billion in stock-based compensation.
GAAP net income was $477 million on $22.4 billion in revenue. That's a 2.1% net margin. On a $1.4 trillion market cap.
Let me put that in perspective:
3.75 billion shares outstanding. Annualize the Q1 GAAP profit and you get roughly $1.9 billion. That's a trailing P/E ratio north of 700. Use the adjusted number - strip out stock comp, which is a REAL cost to shareholders through dilution - and you're still at around 250x earnings.
All of this is extremely bad, but I didn't even talk about the CAPEX BOMB yet...
3 months ago, Tesla guided to "over $20 billion" in 2026 capital expenditure. Last night they raised it to over $25 billion. A $5 billion increase in a single quarter. That's 3x their historical annual capex run rate - $8.5 billion in 2025, $11.3 billion in 2024. The CFO confirmed on the call that Tesla expects NEGATIVE free cash flow for the rest of the year.
So you have a company generating roughly $6 billion in annual free cash flow on a good year, and they're about to spend $25 billion.
The math doesn't work.
They will almost certainly need to issue equity. Which means dilution. Which means the $1.9 billion in annual earnings gets spread across even MORE shares.
The core auto business is literally deteriorating in real time:
Tesla delivered 358,000 vehicles in Q1 (missed estimates again).
They produced 408,000. That's 50,000 cars sitting on lots that nobody bought.
Inventory days jumped from 10 to 27 in just a few quarters. California (their most important US market) saw registrations crash 24% year over year.
Their market share in the state fell from 9.2% to 7.7%. That's on top of a Q1 2025 that was ALREADY weak from Model Y retooling. They're declining off a decline.
And here's what really kills the bull case...
The entire valuation rests on robotaxis, Optimus robots, and autonomy. So let's put numbers on it:
Waymo - the actual leader in autonomous driving with 15 million completed rides in 2025 alone, over 127 million autonomous miles driven, operating commercially across 6 US cities with plans to expand to 20 more - just raised $16 billion at a $126 billion valuation.
That's the market's verdict on what the LEADING robotaxi company is worth. $126 billion.
And Waymo is YEARS ahead of Tesla in actual deployment.
Tesla has 3.75 billion shares outstanding. So even if you assign $126 billion in robotaxi value (giving Tesla full credit for matching Waymo despite being nowhere close) that's $33 a share. Add the auto business at generous auto-industry multiples, maybe $20 a share. Throw in energy storage and services, $10-15.
Sum of the parts gets you to roughly $65-70 a share if you're feeling generous. Maybe $50 if you're not.
The stock is $387.
So what exactly are you paying for?
You're paying for a STORY. You're paying for PROMISES that keep getting pushed back, technology that keeps falling short, and a business plan that requires spending $25 billion a year while the core product sells fewer units at declining margins in a market where California sales just fell 24% and the federal EV tax credit is gone.
I managed the number one mutual fund in America. I founded two billion-dollar hedge funds. I've been doing this since 1981.
And I am telling you:
Tesla at $387 is one of the most egregious mispricings I have seen in my entire career.
THE CRASH WILL BE EPIC
After waiting over an hour for a ride @Tesla@robotaxi support tells me to go home.. 😣😭
They said that they don’t show any Robotaxis in Dallas. The rep went to get confirmation and they said they see the post from @aelluswamy and Robotaxi but can confirm there is nothing showing in Dallas on their side…..go home. Robotaxi is not live in Dallas. Who do I believe? What do I do?
Here’s the call …. This stuff is why people get frustrated with Tesla
DeepSeek will create a moment where all the AI startups that bought thousands of NVIDIA chips will probably go bankrupt, leading to a huge flow of NVIDIA GPUs into the second-hand market. This is in addition to startups whose model was to operate datacenters (e.g. Coreweave) and rent NVIDIA GPUs to other companies in hopes of generating ROI.
Lastly, the Magnificent 7 will finally start to slow down or cut any future orders from NVIDIA as there are already thousands, if not more, GPUs stored in warehouses and not fully utilized.
Then, everything about NVIDIA will start to unravel.