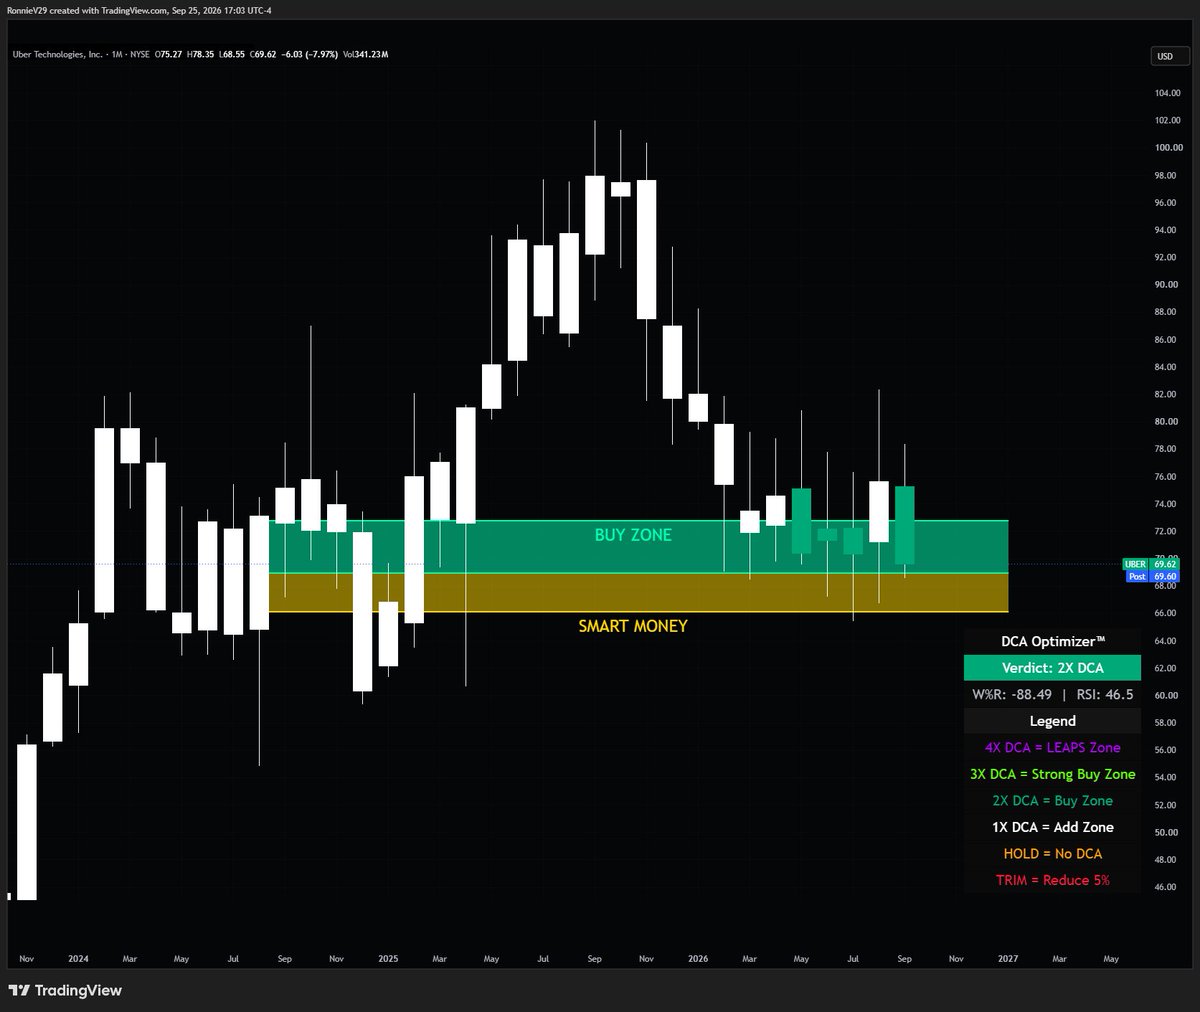
$UBER HITS 2X DCA AGAIN.
AT THE RESPECTED SMART MONEY ZONE FOR ALMOST 3 YEARS NOW.
ALSO, I JUST DROPPED 9 OTHER STOCKS THAT ARE GREAT BUYS BASED ON FUNDAMENTALS AND THE DCA OPTIMIZER INSIDE THE INVESTING COLLECTIVE.
🚨 @HIVEDigitalTech Taps AI/HPC Vet Mark Volk as SVP Revenue, Tops $1M Daily Revenue 🚨
⚡ $1M+ daily revenue — combined hashrate + GPU cloud services surpassed the mark on August 21
⚡ ~12 BTC/day — roughly 2% of global network production, with GPU cloud adding ~$100K/day on top
⚡ $1B+ pipeline — GPU cloud demand pipeline built with Volk's help over a 9-month advisory stint; $600M+ already closed YTD, including 3- and 5-year contracts
⚡ 425% growth track record — Volk grew HPE's HPC/AI business to $2B+ in revenue during his tenure there
⚡ Swedish mining wind-down — sub-5% of August revenue, being repurposed toward higher-value HPC/AI use as HIVE optimizes every megawatt
$HIVE
$HIVE September catalysts...
1- Clarity Act passage September 15
2- Yguazu substation completed and energized,with potential data center plan revealed
3- Bodon,Sweden LOI completed
With the likely passage of the Clarity Act,Bitcoin will quickly run to $100,000,as this will lead to the next Marijuana,AI type of run...
With these catalysts, and the stock chart just beginning to cross on the Mac-D,expect Hive to run to $6.00 or more by early October.
hive:native
Two AI contracts. $570M. 8 weeks. That's 70% of HIVE's entire market cap — signed as new business, not priced in.
💸1/ Signed two AI cloud contracts in the last 2 months: → $220M TCV (June) → $350M TCV (August) → $570M total vs. → $827M — HIVE's entire market cap That's 70% of the company's market cap in new contracted business, signed in 8 weeks. The market hasn't repriced it yet. Here's why
🧵 2/ THE Q1 PRINTFQ1'27 (quarter ended June 30): Revenue: $79.1M (+74% YoY) Adjusted EBITDA: $13.4M — positive, non-GAAP HPC/AI revenue: $7.1M (+52% QoQ, +47% YoY) Bitcoin mining revenue: $72.1M (1,004 BTC mined) The AI segment is still small in absolute terms — but it's growing faster than the mining base that funds it.
⏫3/ THE PEER COMPARISON — this is the part nobody's pricing inLTM revenue vs the exact peer set the market compares HIVE to: HIVE: $331M ← largest HUT: $318M CIFR: $191M KEEL: $188M WULF: $165M HIVE generates more trailing revenue than every other HPC-pivot miner in this group. It's not close.
📈4/ THE MISPRICING Now look at market cap for that same group: HIVE: $827M KEEL: ~$2B CIFR / WULF: ~$9B+ HUT: ~$11B+ The company with the most revenue in the group has, by a wide margin, the smallest market cap. That gap is the entire trade.
5/ WHY THE GAP EXISTS HIVE still gets tagged as "just a bitcoin miner" — 91% of revenue is still mining. The market hasn't repriced it as AI infra the way it has HUT, CIFR, WULF, and KEEL. BUZZ HPC just hit $180M ARR, closing in on the $200M year-end target. That's the catalyst that closes the gap.
6/ THE RE-RATING MATH Holding net debt fixed ($144M): Current: 2.9x EV/Sales → $3.01 Street consensus target ($7.13): implies ~6.2x — already pricing a partial re-rate Halfway to KEEL (5.5x): ~$5.99 (+99%) Full re-rate to KEEL (~10.8x): ~$12.72 (+323%) Not calling for HUT or CIFR's 35-55x — different business mix. But even closing half the gap to the cheapest peer in this group is a multi-bagger from here.
🔋 7/ THE POWER FOOTPRINT 860 MW of power contracted globally. 440 MW active today. 420 MW more coming online through 2028. Three continents. One vision: secure renewable energy, build the data centers, convert that energy into computing power. This is the physical constraint everyone in AI infra is racing to solve — HIVE already has it under contract.
🛖8/ WHO'S ALREADY POSITIONEDTop institutional holders (% of shares outstanding, 6/30/26): Invesco: 4.97% Citadel Advisors: 4.91% Millennium Management: 2.71% Two Sigma: 2.28% Charles Schwab Corp: 1.95% Invesco and Citadel both added meaningfully last quarter. Not unanimous — some funds trimmed — but the size of these positions from names like this isn't nothing.
9/ 📷 BULL CASEBUZZ HPC ARR clears $200M ahead of schedule. First real quarter of GB300 cluster contribution + Paraguay's 100MW online lifts mining margins too. The market stops calling it a miner and starts pricing the revenue it already leads on.
10/ 📷 BEAR CASEReal balance sheet flags: net debt $144M, debt/equity 0.8, EBIT/interest at -59.7x — operations aren't covering interest right now. Stack more capex-heavy contracts on that and leverage risk isn't hypothetical. Add: Blackwell GPU delivery delays, an unnamed "investment-grade" counterparty nobody can verify, and a BTC drawdown masking any AI progress since mining is still 91% of revenue.
11/ CLOSE$570M in new AI contracts. 860 MW of power under contract across three continents. The most revenue in its peer group. The smallest market cap by a mile.
The market is still pricing like a bitcoin miner. Q2 earnings in November might be the quarter that stops.
$HIVE.TO
@HIVEDigitalTech@BUZZHPC
$HIVE $HIVE.NE $HIVE.TO
@HIVEDigitalTech@BUZZHPC
Most investors are still analyzing HIVE through its income statement.
I think they're looking at the wrong place.
The latest earnings were dominated by accounting losses, depreciation, and non-cash charges.
But depreciation doesn't tell you how much cash a business is generating today.
Cash From Operations does.
And that's where the story gets interesting.
🧵
1/
Look at what has happened since Q4'23:
• Cash From Operations: $11.9M → $40.1M projected
• Gross Profit Margin: consistently around 30-40% with peaks near 49%
• Revenue trajectory: $31M quarterly → over $110M projected
The business has clearly strengthened.
Yet the stock price tells a completely different story.
2/
The stock is down significantly from its AI euphoria highs.
That's what makes this chart fascinating.
Not because the stock fell.
But because the business kept improving while the stock fell.
The market has become less optimistic at the exact time the company became fundamentally stronger.
3/
In 2025, investors were pricing expectations.
Today, they can price execution.
Back then, the AI opportunity was largely theoretical.
Today:
• $180M of contracted HPC/AI ARR
• $200M ARR target by year-end
• Real customers
• Real GPUs
• Real infrastructure
The future is no longer hypothetical.
4/
The market celebrated the promise.
Then sold off during the delivery phase.
That's not unusual.
Many of the best-performing investments go through exactly this sequence:
Narrative peak → Stock peak
Execution peak → Opportunity
5/
The latest earnings are a perfect example.
A large part of the market focused on net losses.
I focused on operating cash generation.
Why?
Because HIVE is building infrastructure.
Infrastructure businesses often look expensive, unprofitable, or messy during expansion cycles because depreciation distorts accounting earnings.
Cash generation tells you whether the underlying engine is actually working.
6/
And the cash generation story is improving.
Even after all the volatility in crypto markets.
Even after investor sentiment reset.
Even after the AI trade cooled off.
Cash From Operations continues moving in the right direction.
That's difficult to ignore.
7/
Meanwhile, HIVE is no longer simply scaling hash rate.
The company now has:
• 860 MW contracted globally
• 440 MW active today
• 420 MW still scheduled through 2028
Across three continents.
This is increasingly becoming an energy and compute infrastructure story.
Not just a mining story.
8/
The HPC business is already becoming material.
Signed contracts include:
• $75M ARR with Cohere using 2,304 NVIDIA GB200 GPUs
• $70M ARR with an investment-grade enterprise customer using 2,016 NVIDIA Blackwell Ultra GPUs
Combined contracted ARR now stands at approximately $180M.
Management is targeting $200M by year-end.
9/
Here's the disconnect I struggle with.
When HIVE traded above $7, investors were valuing a vision.
Today, HIVE trades around $3 while possessing:
• More contracted power
• More compute infrastructure
• More AI revenue
• More cash generation
• More signed customers
The stock is lower.
The company is stronger.
10/
Markets are not always efficient in the short term.
Sometimes price leads fundamentals.
Sometimes fundamentals lead price.
This chart suggests HIVE may currently be in the second category.
11/
Wall Street analysts continue to cluster around the $6-$7 range, with several targets above that level.
Whether those targets are ultimately correct is not the point.
The point is that the market appears far more skeptical today than it was when the company's fundamentals were materially weaker.
That's the kind of asymmetry I pay attention to.
12/
The stock price is acting as if the AI buildout failed.
The contracts suggest it is just beginning.
A move toward the $6-$7 analyst target range looks increasingly reasonable if execution continues. 🚀🚀
$HIVE is still widely viewed as a Bitcoin miner.
The numbers suggest something much bigger is emerging.
• 860 MW of contracted power globally
• 440 MW active today
• 420 MW additional capacity coming online through 2028
• Operations spanning three continents
• ~$180M of contracted HPC/AI ARR already signed
• Management targeting $200M ARR by year-end
• $75M ARR contract with Cohere using 2,304 NVIDIA GB200 GPUs
• $70M ARR agreement with an investment-grade enterprise customer using 2,016 NVIDIA Blackwell Ultra GPUs
Meanwhile:
Revenue is projected to grow from ~$31M per quarter to more than ~$110M per quarter.
Operating cash flow is projected to grow from ~$12M to ~$40M per quarter.
The market still tends to analyze HIVE through the lens of Bitcoin mining.
But increasingly, HIVE looks like a company doing something else:
Securing renewable energy.
Building high-performance data centers.
Converting energy into AI compute.
Sometimes the biggest opportunities appear when investors are valuing yesterday's company instead of tomorrow's company.
$HIVE vs $KEEL
This valuation gap makes very little sense to me.
$HIVE
• $257M TTM revenue
• 51% 3-year revenue CAGR
• EV/Sales: 2.8x
• Recently secured a ~$350M AI/HPC infrastructure agreement
$KEEL
• $188M TTM revenue
• 16% 3-year revenue CAGR
• EV/Sales: 12.4x
The disconnect becomes even larger when looking forward.
HIVE's revenue is projected to grow from ~$72M to ~$110M per quarter by FY27 while operating cash flow turns strongly positive.
KEEL's revenue is projected to decline from ~$68M to ~$19M per quarter while operating cash flow remains negative.
Yet the market values KEEL at ~$2.0B and HIVE at only ~$772M.
Either KEEL is dramatically overvalued, HIVE is dramatically undervalued, or both.
Markets eventually close gaps like these.