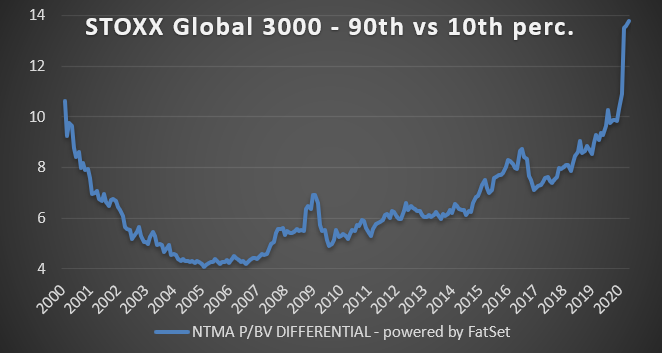
Twitter debut - after having spent many years on the sell side as a quant strategist. Thought I would share a favorite chart depicting the great valuation divide. Expensive (90th percentile) versus cheap stocks (10th percentile) utilizing P/BV estimates from FactSet.
@AndreasSteno I would call todays reading a touch worse . I sat in the market in those days - can't say I see much of a difference, but that's opinion of course.
@MrBlonde_macro @MaverickBogdan Agree on direction importance but the strength of the eventual reversal becomes even more powerful if the relative discount has widened considerably. That’s why I suggested that you index proportionally rather than making chart look 1-1.
@MrBlonde_macro @MaverickBogdan Why not do a proper indexation where you apply the same to both lines. Clearly EM EPS underperformance explains a fair bit - but you would see EM getting cheaper in relative terms as relative price falls faster/more than relative EPS if you have them on one axis.
Looking at the 90th percentile in isolation I very much doubt that market participants will feel comfortable buying this dip. Expected returns for this group of stocks remain quite grim. We are not even back to pre-covid levels…
Time to post a few updated charts on valuation differences, which has corrected a fair bit. Below charts compare the 90th vs 10th percentiles (US LCAP >5bn in MCAP). Also linking it to my pinned tweet.
Time to post a few updated charts on valuation differences, which has corrected a fair bit. Below charts compare the 90th vs 10th percentiles (US LCAP >5bn in MCAP). Also linking it to my pinned tweet.
Twitter debut - after having spent many years on the sell side as a quant strategist. Thought I would share a favorite chart depicting the great valuation divide. Expensive (90th percentile) versus cheap stocks (10th percentile) utilizing P/BV estimates from FactSet.
🌍Week Ahead: US inflation has arrived
https://t.co/10nT7tEpPQ
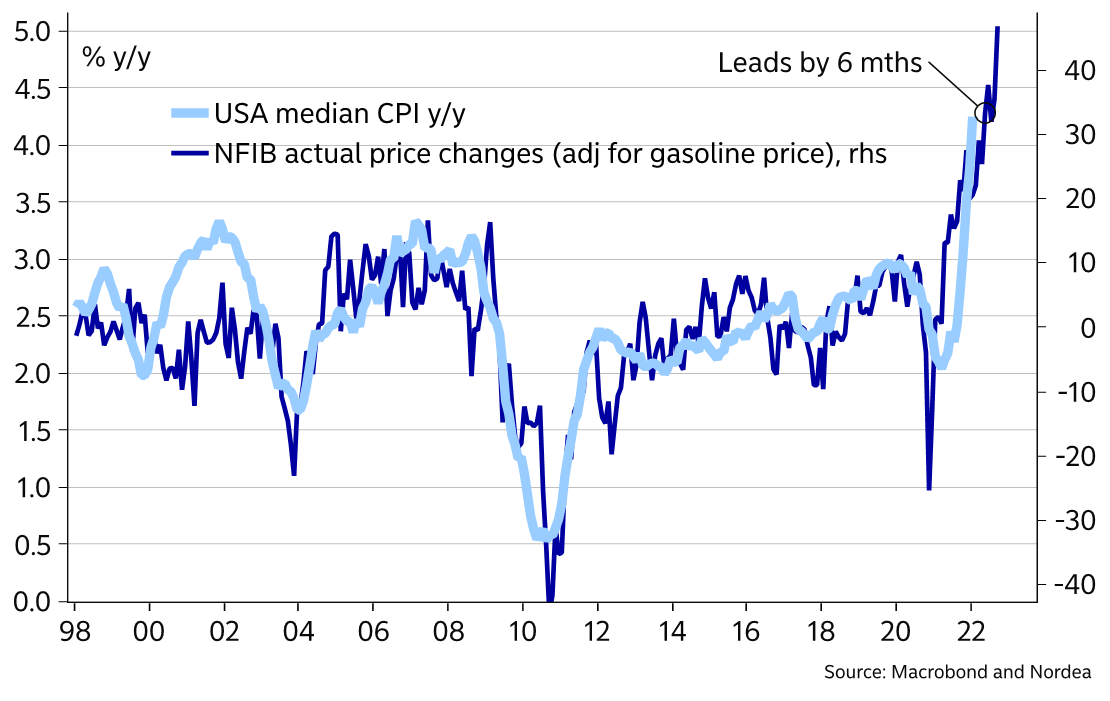
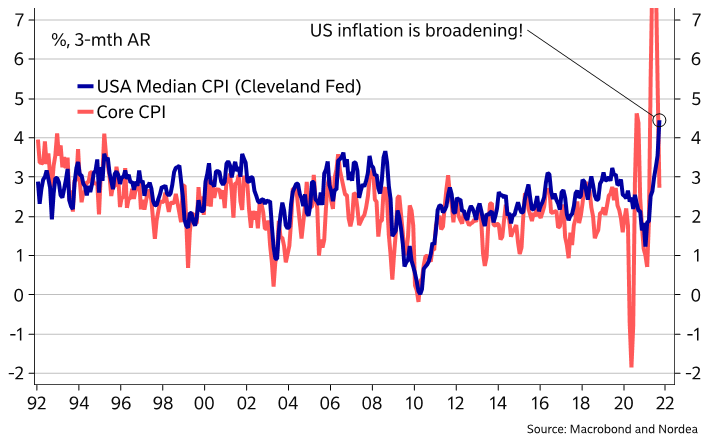
We can't remember a week with so much evidence that our longstanding anti-transitory US inflation view is correct, but the Fed has interpretive precedence. Q4 risk-on mode, which is reasonable. Expect a noisier -22
🌍Week Ahead: Volatility Comeback
https://t.co/463SwwPTdo
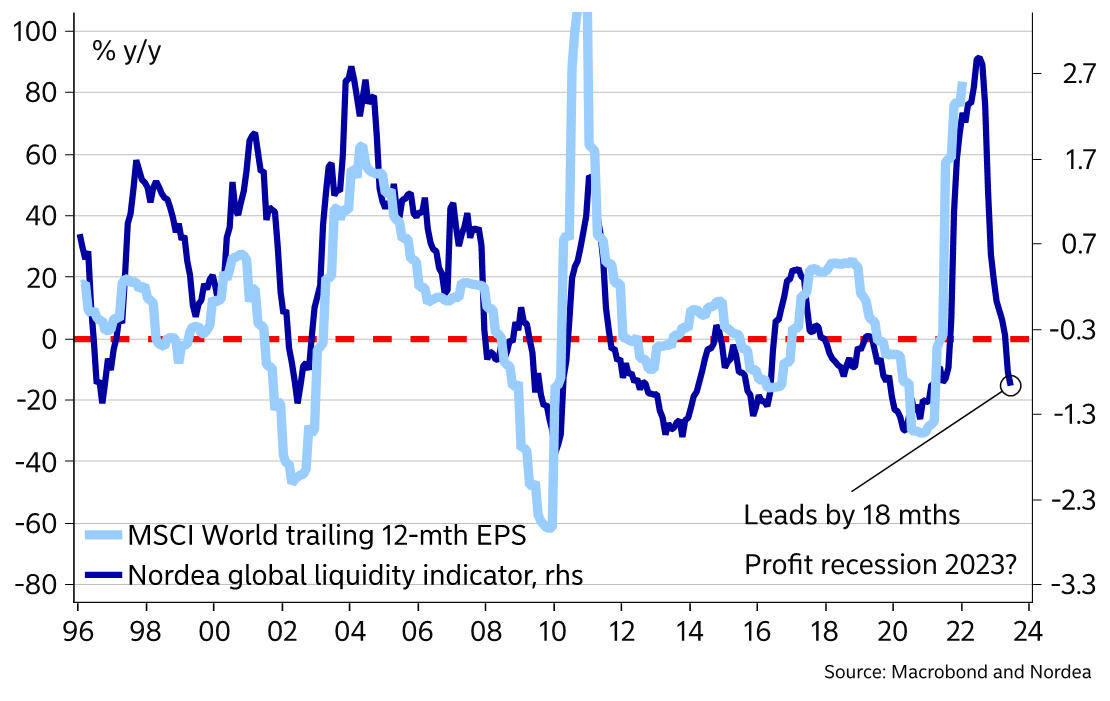
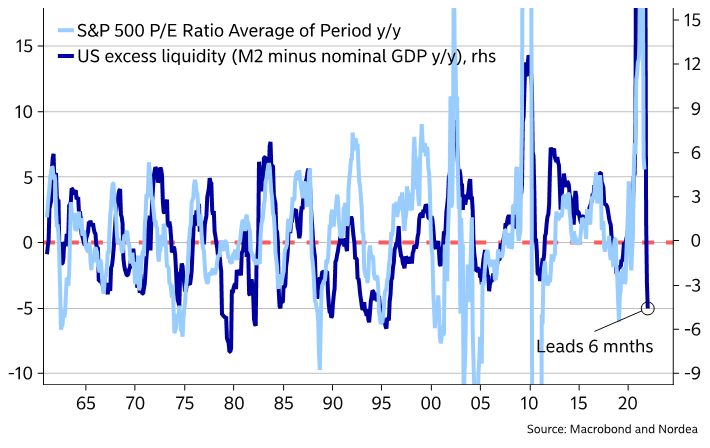
Equity volatility is back. We see 4 macro reasons why 2022 should be noisier than 2021: liquidity, growth slowdown, cost/margin problems & the risk of the Fed put looking different if inflation indicators stay elevated
14/ In my experience a high multiple stock is at its most vulnerable when earnings growth decelerates. I am amazed that market participants are not more worried about lofty market valuations in combination with an increased likelihood of decelerating earnings growth /end
13/ In my mind we simply have to get used to slower earnings growth in the years to come. Compound this risk with the fact that we have valuation levels at such extremes that the expected return from equities is very meagre to start with.