Please contact me if you are interested in joining the group. There is absolutely no commitment at this stage.
The objective is simply to assess whether we can gather enough shareholders to launch legal proceedings in a way that makes economic sense for everyone.
OPRO Ongoing - only a few days left for $FCMC (Fermière du Casino Municipal de Cannes)
For those wishing to challenge the scandalously low price "offered" as part of this squeeze-out, there is one last possible avenue: an appeal before the Paris Court of Appeal.
1/n
Of course, this will involve legal costs. However, if we join forces and share the costs pro rata to our respective shareholdings, this could make the action economically worthwhile for everyone.
5/n
Conclusion:
Japan $Eyewear Holdings brings a unique combination of exceptional operating economics, founder-led execution, room to grow and a sub-9x EV/EBIT valuation.
I am long JEH (5889.T)
This is Not an investment advice, just my personal view. Always do your own research!
Investing alongside great entrepreneurs is a real pleasure.
I consider Shinya Kaneko one of them. Through $JAPAN Eyewear Holdings, he combines traditional Japanese craftsmanship, innovation, and an outstanding customer experience.
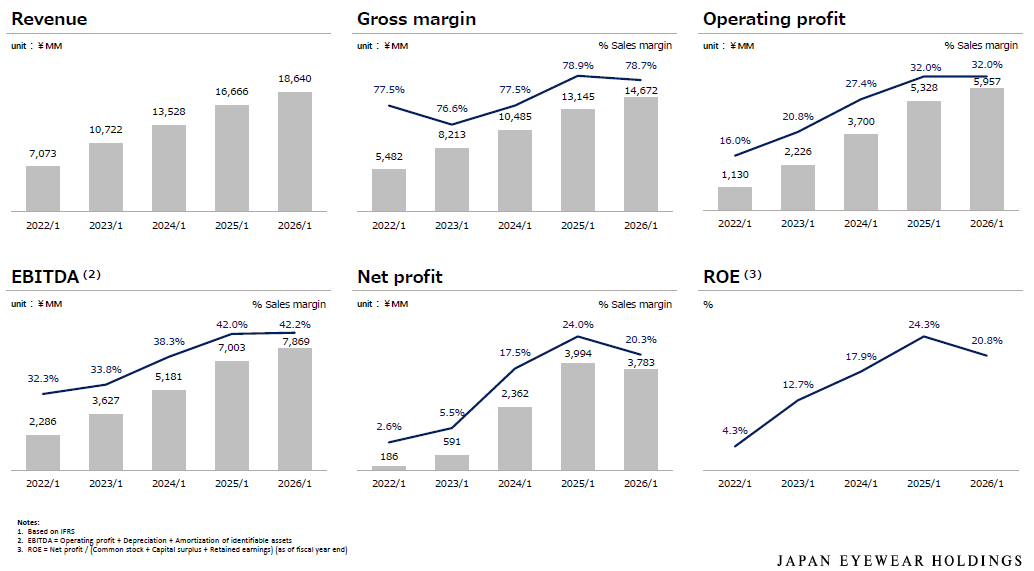
The results speak for themselves: +14%...(1/n)
H1 operating income reached ¥3.5bn, putting ¥7bn for the full year within reach.
Their business model enable them to sustain their growth while maintaining a dividend (40% target payout ratio).
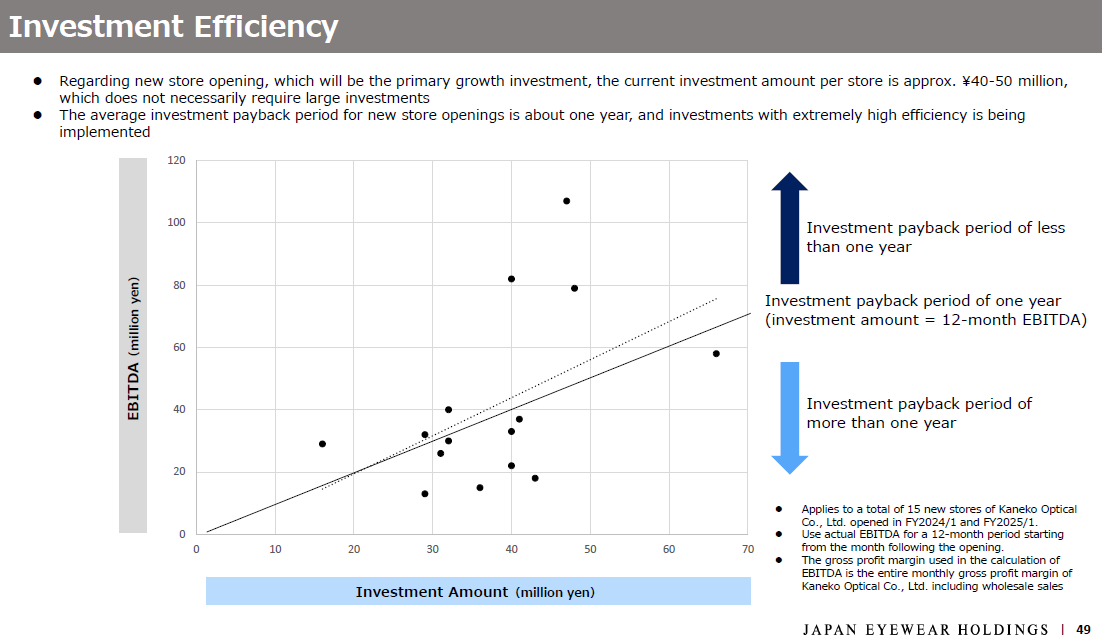
Each new store requires around ¥50M to open and brings this same amount in EBITDA.
What price for this high-quality, growing business? Spoiler alert: Less than 9x EV/EBIT!
At ¥2,147 per share (October 22, 2026), market cap stands at ¥52bn and EV at ¥60bn (including ¥11.6bn in borrowings and ¥3.6bn in cash as of July 31, 2026).
(5/n)
International expansion offers significant upside.
High-end Japanese craftsmanship has strong appeal worldwide.
While the group owns the land and buildings of some manufacturing facilities, most boutiques are leased, allowing continued expansion (+10 stores in 2025). (4/n)
Execution is equally impressive, with two clear strategic priorities:
1) Vertical integration: recently acquiring a frame surface-treatment company in Sabae.
2) Boutique expansion: 113 stores, only 11 of which are outside Japan, offering ample room for growth.
(3/n)
14% annual growth, a 32% operating margin, and ROE above 20%.
From frame design and manufacturing in Sabae, Japan’s traditional eyewear hub, to its exquisite boutiques, quality is paramount.
No compromise.
(2/n)
Disclaimer: I hold shares of Electricité de Strasbourg, bought a bit in 2021 and 2023 (under 100€)... and now again in October 2026 around 155€.
This is not a Financial Advice, do your own research!
Quietly printing cash with a non-replicable electricity network as its main asset, a French regional Energy provider can currently be bought for less than 5x its op. cash flow.
If you can live with low liquidity (11% free float), $Electricité de Strasbourg is a cash rich… (1/n)
Optionality
The small free float can be a liquidity constraint for institutional investors but it also offers an optionality on a takeover operation from EDF, the majority shareholder (they hold 88.6%).
They have no need to keep it listed. (8/n)
Also, please note that H1-2026 figures took a bath (30% down). Half-year operating Income is still a strong 83.5M€ though!
I took that into consideration, the case remains attractive in my opinion with EV/EBIT under 5x. (6/n)
Note
Enterprise Value figures reported by most financial data providers exclude short-term financial assets (€129m in this case) simply because their maturity exceeds 3 months, even though it remains below one year.
I have included these assets in my own EV calculation. (5/n)
2) Energy sales (ES Energies), only keeps a 7.7% Operating margin (5.5% net Margin). This activity brings volatility to the group's sales turnover but remember that their business is on the commercial margin which is much more stable and less correlated with energy prices. (4/n)
1) The Distribution (electricity network) is their crown jewel. With 332M€ Sales and 88M€ Net Income, this activity prints a 26.6% Net Margin! They distribute electricity to 600k clients.
It represents 25% of the group sales but 50% of net income. (3/n)
Electricité de Strasbourg is a cash rich (345M€ net cash) dividend payer (13.7€ per share representing 8.8% for current 155€ share price) with strong and recurring cash flows (huge 282M€ Op cash flow 2025).
They have two main activities : Distribution and Energy Sales. (2/n)