Must read article.
With some quick & co-ordinated action OneWeb ($ETL.PA) terminals could be designed to offer a real alternative to Starshield terminals for certain drone applications.
Will it happen though ...
https://t.co/ibodSjJLvB
Reminder that PAC-3 isn't the only AD missile that is scaling. E.U. is starting to do the same with Aster/SAMP/T. Although, in E.U. fashion ever....sooo....slowly.
Avio and @MBDAGroup have signed a production order for the supply of solid rocket motors and related aerodynamic surfaces for the ASTER 30 defense system. Read the full press release: https://t.co/PjcyJ6Egph #space
This is eye-opening. Europe’s share of global tech R&D has collapsed from 23% in 2005 to just 8% today, while the US has climbed to 62% and China has risen from near zero to 15%. South Korea now outspends Germany, France, the UK, and Italy combined in tech R&D. Yep, you read that right.
This is the predictable result of policy choices that systematically favor control and redistribution over growth. Layered regulation, data rules, AI restrictions, labor rigidities, and precautionary frameworks, raises the cost and slows the pace of turning ideas into products, forcing companies to spend scarce resources on compliance rather than experimentation. High taxation and expansive redistributive systems extract capital that would otherwise fund private R&D and risk-taking, while shrinking the after-tax reward for building something new and scaling it. The broader left-leaning mindset that prioritizes equality of outcome over dynamism treats entrepreneurial success as something to be managed, taxed, or shared rather than unleashed and rewarded.
Places that protect the returns to innovation and keep barriers low continue to pull ahead, attracting talent and capital that Europe increasingly loses. Europe’s relative decline is the cumulative outcome of treating dynamism as a problem to be regulated rather than the engine of prosperity. Without a shift toward lighter rules, lower burdens on enterprise, and greater tolerance for unequal outcomes from unequal effort, the gap will keep widening, and Europe will become an open-air museum for wealthy Americans and Asians.
European Commission sounds the alarm (now !!!) about the number of oil refineries closing in the region over the last 20 years. "We need to counter this trend," says EU Energy Commissioner Dan Jørgensen. "This crisis is a wake-up call." Quite.
Saab is giving its Giraffe AMB radar a new role at sea, allowing naval forces to track threats in 3D across both air and surface domains
https://t.co/HJ4VvJgLTl
Berenberg upgrades $AVIO.MI from Hold to BUY, raising its price target from €33 to €39.
More interesting is the reassessment of Avio's Defence Propulsion business. Berenberg now expects €532m in revenue by 2030, up from its previous estimate of €312m (+71%).
This development was foreseeable for some time.
Avio started working with Raytheon ($RTX) on solid rocket motors back in 2024, followed by cooperation agreements with $LMT and $RTX in November 2025.
Then came the announcement of the $500m factory in Virginia, the groundbreaking in September 2026 and Advent's €109m investment.
I've been highlighting this business for quite some time. Avio is increasingly becoming an important independent supplier to the US missile industry. Good to see analysts starting to reflect that potential in their forecasts.
Who is buying 50,000 thermal lenses from LightPath $LPTH
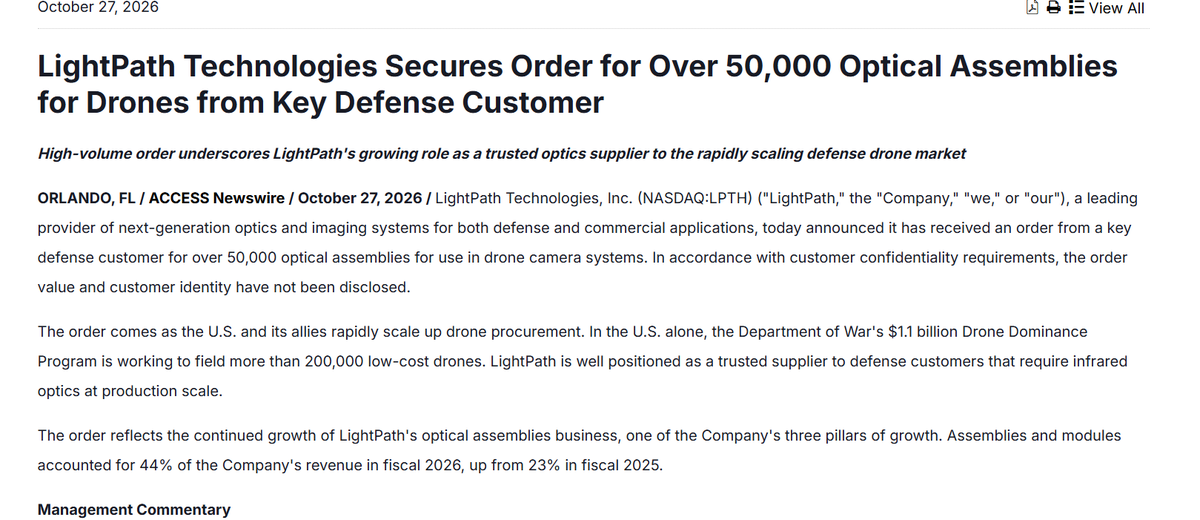
On Tuesday @lightpathtech announced an order for more than 50,000 optical assemblies for drone camera systems from an unnamed “key defense customer”, with no value disclosed.
My day job is advising Australian defence and advanced materials companies on getting into US defence supply chains, and from that seat this reads as a beachhead order, the first public proof that a major buyer trusts LightPath with a production line rather than a qualification lot.
In this deep dive article I cover
* Working through every candidate, from Leonardo DRS and Teledyne FLIR to Neros, Anduril and LightPath’s original European FPV customer, with the evidence for and against each
* Why I think the buyer is a camera maker rather than a drone maker, and why that’s the better outcome for LightPath
* Putting a range on what the order could be worth (roughly USD $5–$10M) and size it against FY26 revenue and backlog
* Laying out what happens next if it’s DRS, whose 50,000-camera Tenum Orbit agreement from July lines up almost exactly
* Mapping how LightPath now controls its own stack, from the glass it melts through to finished cameras and seekers
The unit count is the story, as this is the first time Drone Dominance scale volume has shown up in a single LightPath order.
A second order from this customer is what would turn it into a run rate, and I’ll be watching for it.
Full article link in the first comment - enjoy. 🫦
$TKA.DE is spinning off 49% its tk accelis shares ($TKAG.DE) to existing investors and retaining a majority in the business which buys, sells and processes materials such as steel and alloys and manages their warehousing.
https://t.co/FebnzSS0tf
Putting the finishing touches on a deep dive into the latest developments with $LPTH
Article will be published on my substack - if you're not already subscribed, please do so.
It's free, and will remain free.
https://t.co/XCtfQ8HVda
🫡
Sitting here working on $UMAC Q3 numbers.
Allan has provided their internal targets of $12M to $14M for the Q, down from $16.72M in Q2.
Reasons given are:
- Inventory shortages on electronics parts due to outgrowing a vendor and vendor switching
- Motor factory construction for installation of the first automated line
- Motor defect spillover into Q3. A defect was caught in Q2 and addressed, and they're continuing to replace customer inventory.
With that in mind, I built a table to help understand where that would fall vs UMAC's historical performance.
Taking the lowest all time revenue/employee set in Q2 '25, measured with end of Q headcount of 38 (ergo most diluted rev/emp), against the beginning period Q3 headcount of 240, we'd just be below the $14 internal target at $13.5M.
Taking the lowest rev/emp against midpoint headcount, set in Q1 '26 at just below $73k/emp, against beginning of period Q3 (240), suggests $17.5M.
Then I take a look at the suggested revenue for Q4, measuring against average rev/emp in Q2 (the latest for which we actually have numbers) and my guess for midpoint Q4 headcount at 350 (we're at 330 with the UE close), suggests about $30.7M vs the $25M Allan indicated in the Q2 call.
All just a fun experiment to see what's possible vs what's been communicated. Also strengthens my perspective that we'll likely see numbers come in at the high end of Allan's target, if not slightly above. A miss below $12 would require a lot of explanation.
This is all well and good, but there's no mention of access to orbit.
You can build all the satellites you want, but if you can't get them into space quickly and cheaply, your position is still fragile.
The access to orbit dependency must be addressed.
Europe is working on several plans to break the dominance of tech billionaire Elon Musk’s satellite communications service, Starlink.
The moves come as the world's richest man expands his grip on space.
🔗 https://t.co/nUsH0PpmuG
$LPTH just announced an order for 50,000+ optical assemblies for defense drones.
On the Q4 call eight weeks ago, Sam Rubin described this business as "a few million dollars" in orders.
Step-change in order dynamics, not an increment. 🧵
Well good morning $LPTH
My best guess on value is based on small infrared lens assemblies for Group 1 drones selling somewhere in the USD 50-200 range each, so probably USD 2.5-10M.
The more important part is the volume and the cadence, as 50,000 units is a production run rather than a qualification lot, and it lands two weeks after a USD 6.3M follow-on from the C-UAS customer that had already placed USD 13M in July, so the assemblies business is now booking repeat orders at scale from what reads as two different customers.
It also fits what the numbers were already showing, with assemblies and modules going from 23% of revenue in FY25 to 44% in FY26, and the release says they've been adding automation and capacity for exactly this kind of volume.
The DoW is trying to field 200,000+ low-cost drones under Drone Dominance alone, and I suspect the list of suppliers who can actually ship NDAA-compliant infrared optics in the tens of thousands is a short one 🫦
Amazing work @skrubin and the @lightpathtech team
Conviction will be rewarded.
https://t.co/8MH1Ak9ZEA