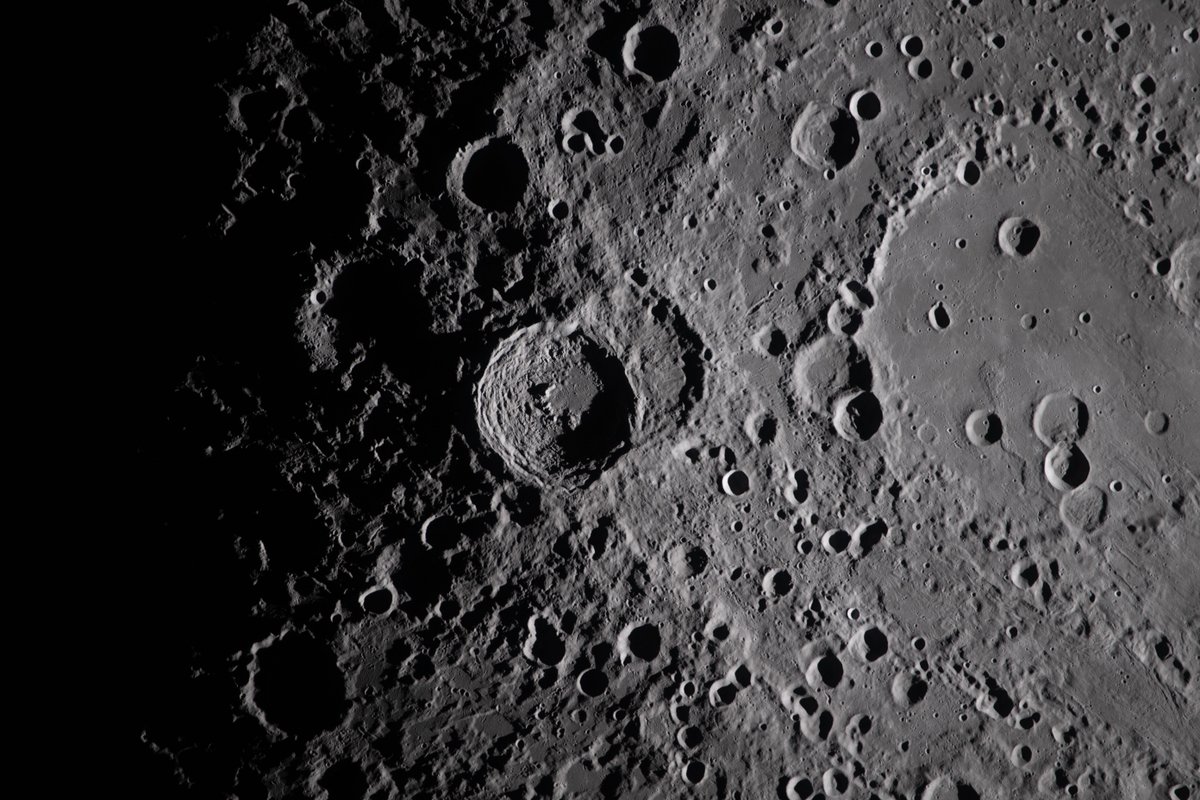
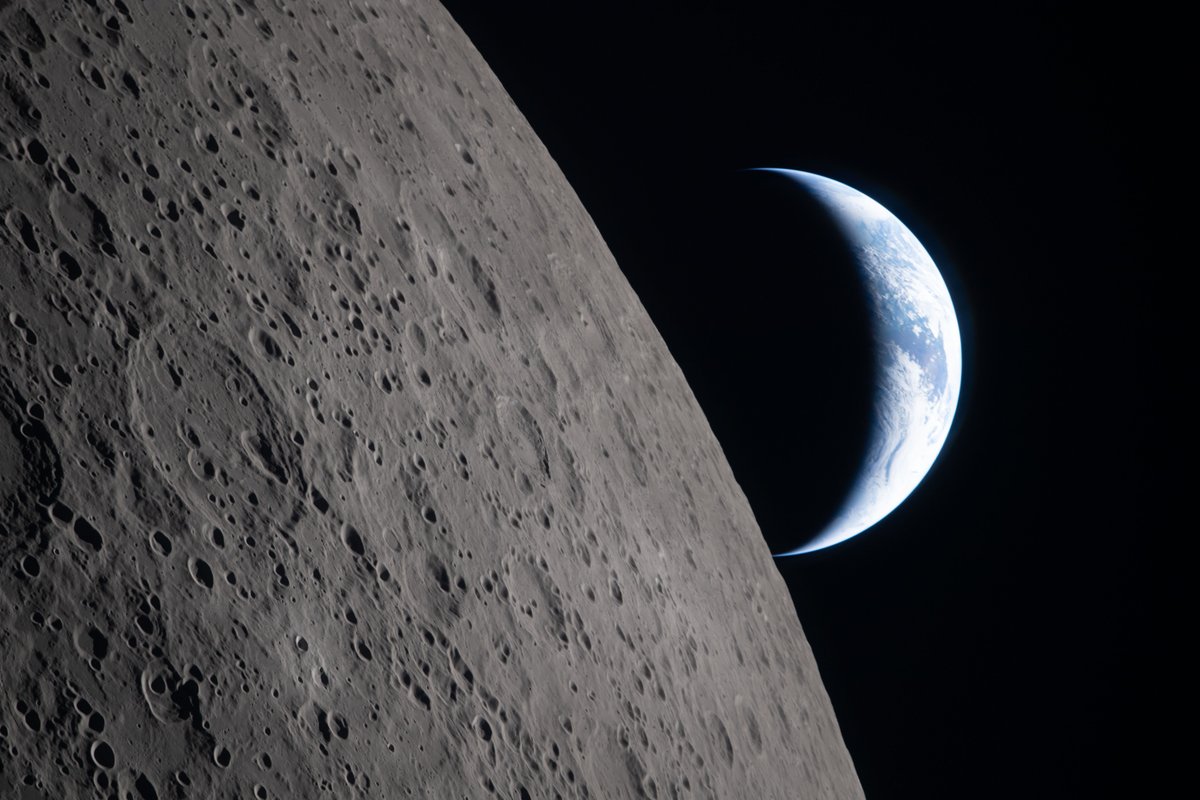
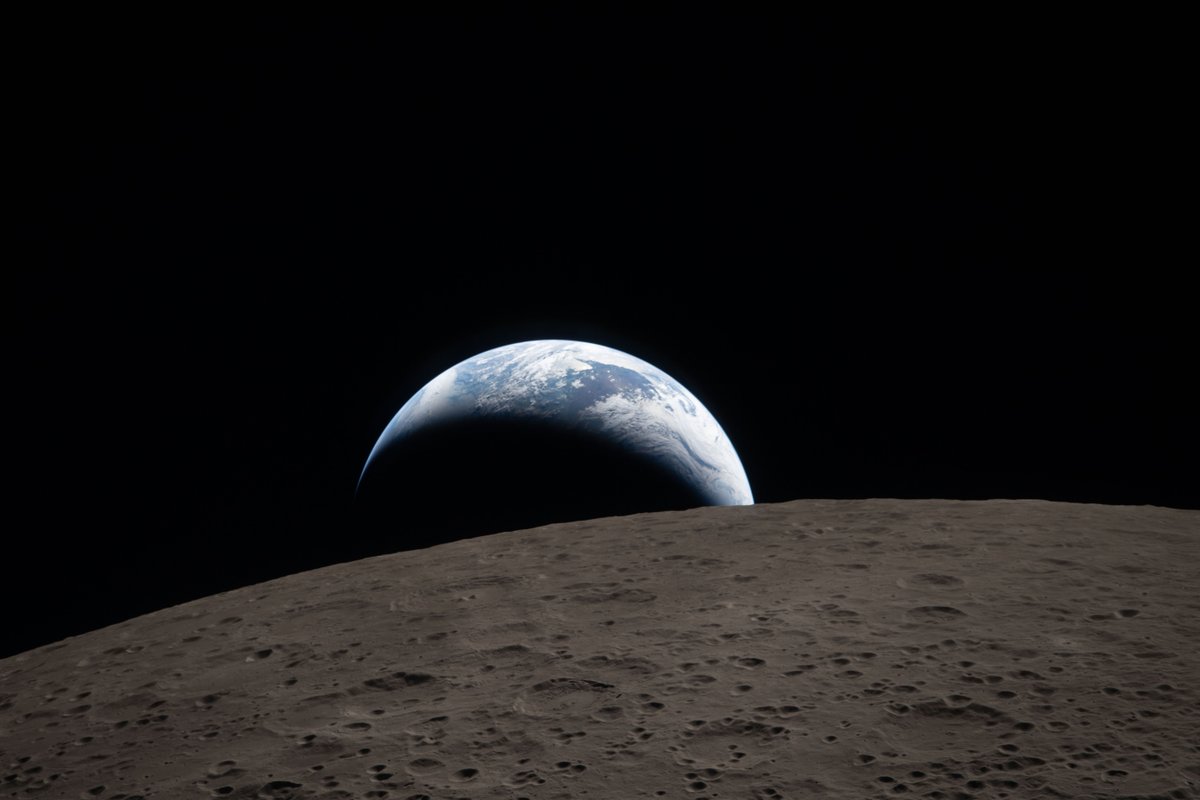
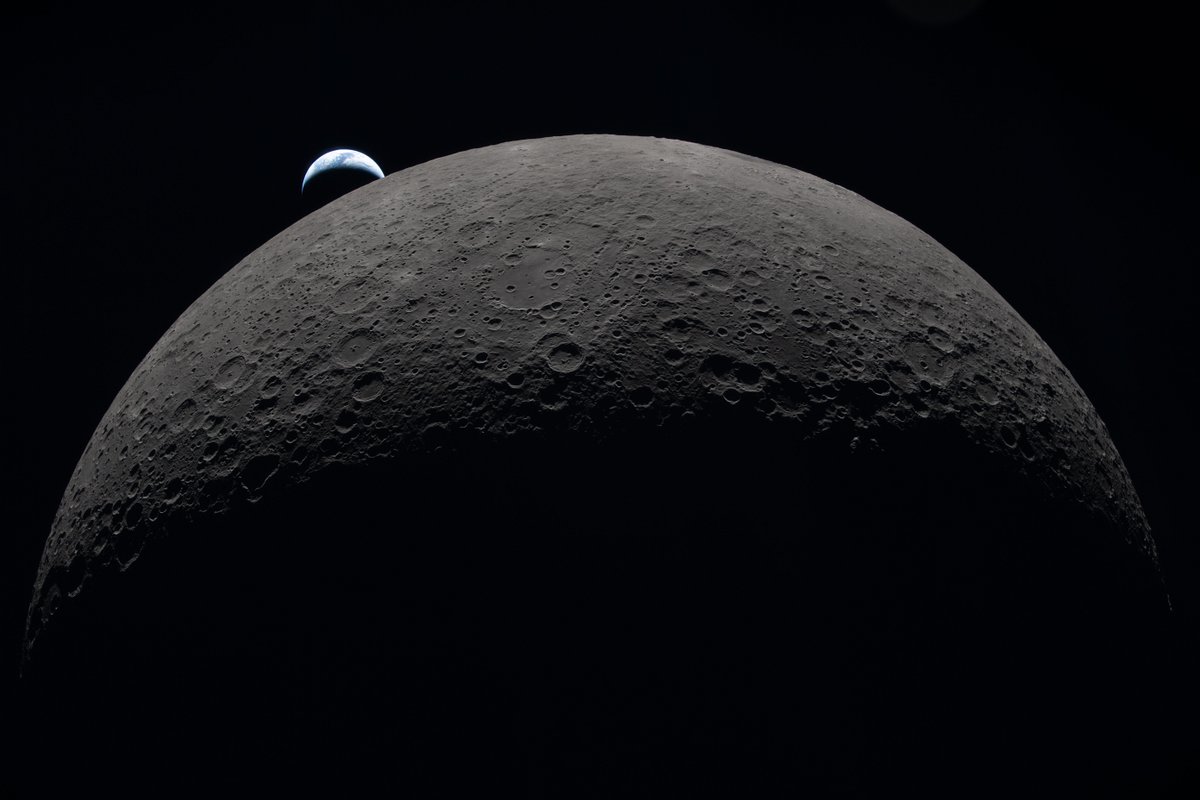
Hello, Moon. It’s great to be back.
Here’s a taste of what the Artemis II astronauts photographed during their flight around the Moon. Check out more photos from the mission: https://t.co/rzM1P0QbOl
$OSCR
THESIS SUMMARY:
In a quick summary, I believe Oscar Health will out perform in 2026. Despite enhanced ACA subsidies expiring, the baseline original subsidies are in-effect and cap UP TO 9.44% of monthly income. The market is pricing in a straight Armageddon to their member count, I disagree. Using the recent ACA enrollment release the YoY change is rough a 5% decline, and using 2024 member counts, a weighted ~6.9% decline for Oscar’s states. Meanwhile, the market was pricing in a decline from 20-25% depending on the source. Meanwhile, in the insurance industry, you are always preparing for the next open enrollment. In 2025, they launched their plans into 2 new states and SEVERAL new counties, representing a ~14% increase in coverage, which is not a direct 14% increase in members, but could be or even more (not betting on it). Also, Oscar health’s tech platform and operating leverage is allowing them to offer cheaper plans than many competitors, personalized care, and many great and SUPER competitive benefits. Because of expansion and competitive offerings, I expect them to gain member share to offset some of the potential member loss. I am looking for a 3% net member gain year-over-year, in one of the most feared ACA marketplace enrollment periods… this is a conservative estimate, many others expecting higher. But that isn’t the best part for 2026… profitability should be reached again… when stocks reach profitability, and consistently QoQ, typically the stock will re-rate, and in the insurance industry, around .65x min to 1.5x on the high-side depending on market conditions. Paired with a 28% weighted price increase across all plans, which is largely subsidized by the government, I expect strong 2026 results.
Price Targets I have calculated range from $25 (super conservative, low multiples, continued fears), all the way to $70 (super bull case with enhanced ACA subsidies, not realistic anymore, this was also with all estimates at the high end), with more realistically looking for $35 based on my expectations. (Representing ~169% increase from today’s price.
Expectations:
Profitability
14B revenue guidance given minimum (actuals closer to 15B, beat and raise style CEO)
2.5-5% margins (CEO looking for 5%)
Net gain in members of ~3%
Super conservative expectations in my mind based on my research, which puts us considerably higher than our current stock price. This is both a DEEP VALUE play, due to the immense fear for member drop-off, and a growth play due to ICHRA, ACA, and tech expansion.
Consistent profit in this industry will force a re-rating, this is a stock I am keeping my Roth IRA, and expect it to increase considerably over the years.
Short-term price action means nothing. I am forecasting almost a year out, and until my thesis changes, I am buying.
Prison for me and you if I share Non Public Information (NPI) during the “quiet period”. We are currently in the “quiet period” which starts when quarterly/annual results are reasonably known and our quarterly conference call.
The SEC reports a list of potentially suspicious trades during the quiet period which insiders (me) are asked if we know any of those names.
The SEC has good information on that knowledge, including who I “know”. If I don’t acknowledge that “knowness”, we both get charged with suspicious behavior.
I appreciate all your support. I am not going to jail for anybody!
At Oscar, we're always looking for ways to make healthcare simpler, faster, and more accessible, especially in moments when members need to take action but are slowed down by avoidable barriers, like account logins or setup.
In our latest blog by Audrey Western and Nicki Padar, we share how Applets (small, secure digital tools delivered by text or email) help members take charge of their care, like accessing their ID cards, scheduling a virtual health assessment, or paying a bill, without the unnecessary friction.
Read how our teams designed Applets around real member behavior to create a more personalized experience: https://t.co/RbBX3hseWB
Today CleanSpark announced we have expanded our capital strategy to include an increase in our credit facility with Coinbase Prime (Nasdaq: $COIN) to $200 million. Additionally, $CLSK's Digital Asset Management team has officially launched its institutional grade Bitcoin treasury desk. The team completed partner selections after running a competitive and thorough RFP and due diligence process across four product lines — borrowing, lending, custody, and derivatives — to support our risk management and Bitcoin treasury optimization strategy.
“We are proud to expand our relationship with Coinbase through their Bitcoin-collateralized lending program as part of our broader strategic approach to capital management,” said @ZachKBradford, CEO of CleanSpark. “Our capital strategy has matured significantly, enabling us to pursue non-dilutive funding options that support both our operations and long-term growth. CleanSpark is among a select few in our industry to have achieved escape velocity — the ability to self-fund operations, augment our bitcoin treasury, and contribute to expansion capital through operational cash flow.”
“Coinbase is excited to support CleanSpark and their innovative approach to capital and treasury management in Bitcoin mining,” said Brett Tejpaul, Head of @CoinbaseInsto. “By deepening our relationship with CleanSpark and offering institutional-grade lending and custody management through our Prime service offering, we're committed to delivering strategic solutions that help CleanSpark thrive in the evolving crypto landscape.”
Bradford continued, “With our Bitcoin holdings now exceeding 12,000, valued at approximately $1 billion1, we believe this is the right time to evolve from a nearly 100% hold strategy adopted in mid-2023 and move back using a portion of our monthly production to support operations. This represents a meaningful strategic distinction from many of our peers, who continue to rely on equity dilution to fund operating costs or increased leverage to grow their Bitcoin reserves. We view our approach as deliberately strategic rather than ideological — particularly now that we’ve reached our current scale. While we remain committed to Bitcoin as a long-term, hardened asset, we believe a more effective way to increase shareholder value is through a balanced approach between monetizing new production and building long-term holdings.”
“As part of this balanced approach, we intend to further build out our diversified capital stack. In today’s market environment, we view the debt markets as the most efficient and responsible path to support accretive growth, and our strong balance sheet positions us to take full advantage of that opportunity. As we enter our next phase — targeting 50 exahash and beyond— we believe CleanSpark, America’s Bitcoin miner®, is uniquely positioned to deliver sustained, long-term shareholder value as we continue to execute on our strategic vision and evolve.”
[1] Based on a Bitcoin spot price of $84,500 as of April 14, 2025
Full press release here: https://t.co/Hw7nmAG9nn
1. Daily Confluence Chart:
Price has dipped nearly 30% since its December highs. Volatility is high, I have taken the past three days as huge buying opportunities.
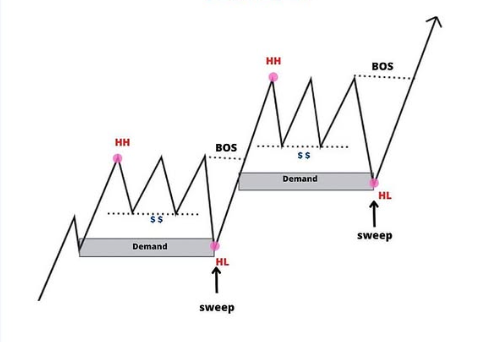
- Price broke and quickly recovered from the resistance flipped support (green box). Looks like we had a text book liquidity sweep. I expect the bottom to be in!
- Found support on the weekly bull market support band. We are now in a holding zone right inside the band.
- Price is at multiple key fib levels right now (0.382 march 2024 fib, 0.618 local retracement zone). Lets see if price can hold these zones moving forward. This is still a buy zone for me.
- Price has tried to break the gann arc many times buy has rejected every time. The arc now sits much lower at $14. I am expecting a breakout easily by EOY.
Overall, I still believe the gap does NOT need to be filled. I bought this dip heavy with intentions of it not filling the gap.
Q1 2024 Shareholder Update → https://t.co/fvAaI97WoA
— Highlights
While many are pulling back on their investments in EVs, we are investing in future growth. This includes our AI programs, production capacity, Supercharger & service networks as well as new products infrastructure.
To maximize the impact of our products, we design & manufacture a fully integrated ecosystem.
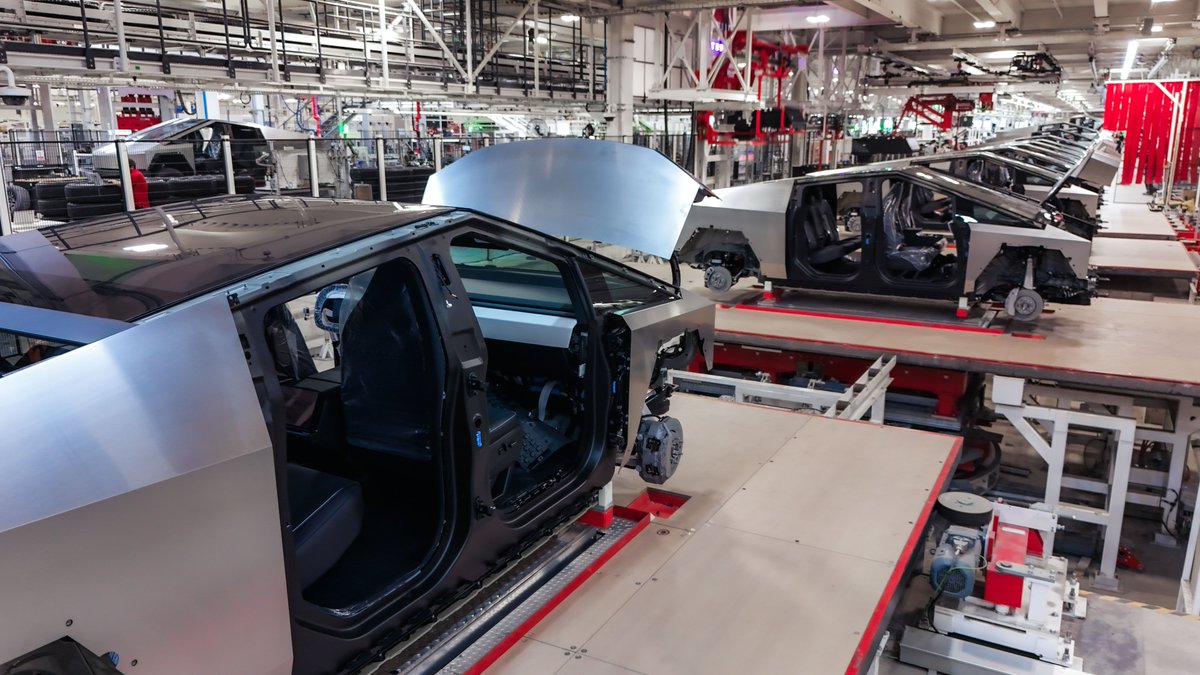
Cybertruck production ramp is progressing, with a sequential cost improvement in Q1 & a production rate of over 1k units/week in April.
Additionally, 4680 ramp continued successfully in Q1 & remains ahead of Cybertruck ramp.
The future is not only electric, but also autonomous.
Since the launch of FSD V12 earlier this year, it has become clear that a vision-only architecture with end-to-end neural networks, trained on billions of miles of real-world data, is the right solution for scalable autonomy.
We also completed the transition to Hardware 4.0 in Q1, our latest in-vehicle computer with increased inference processing power & improved cameras.
To make FSD Supervised more accessible, we reduced the subscription price to $99/month & purchase price to $8k in the US.
We're also building ride-hailing functionality that will seamlessly integrate into the Tesla app & become available in the future.
Energy storage deployments in Q1 increased sequentially to a record 4.1 GWh & we continue to ramp our 40 GWh Megafactory in Lathrop, CA to full capacity.