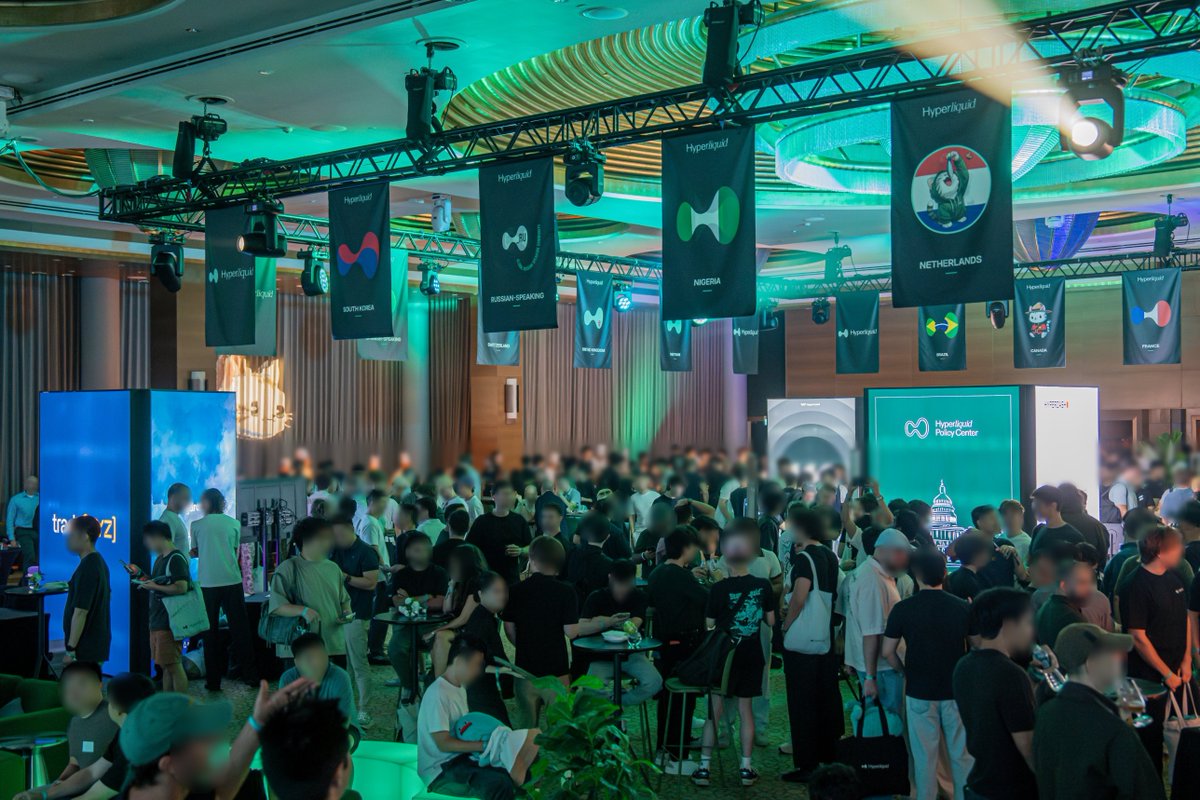
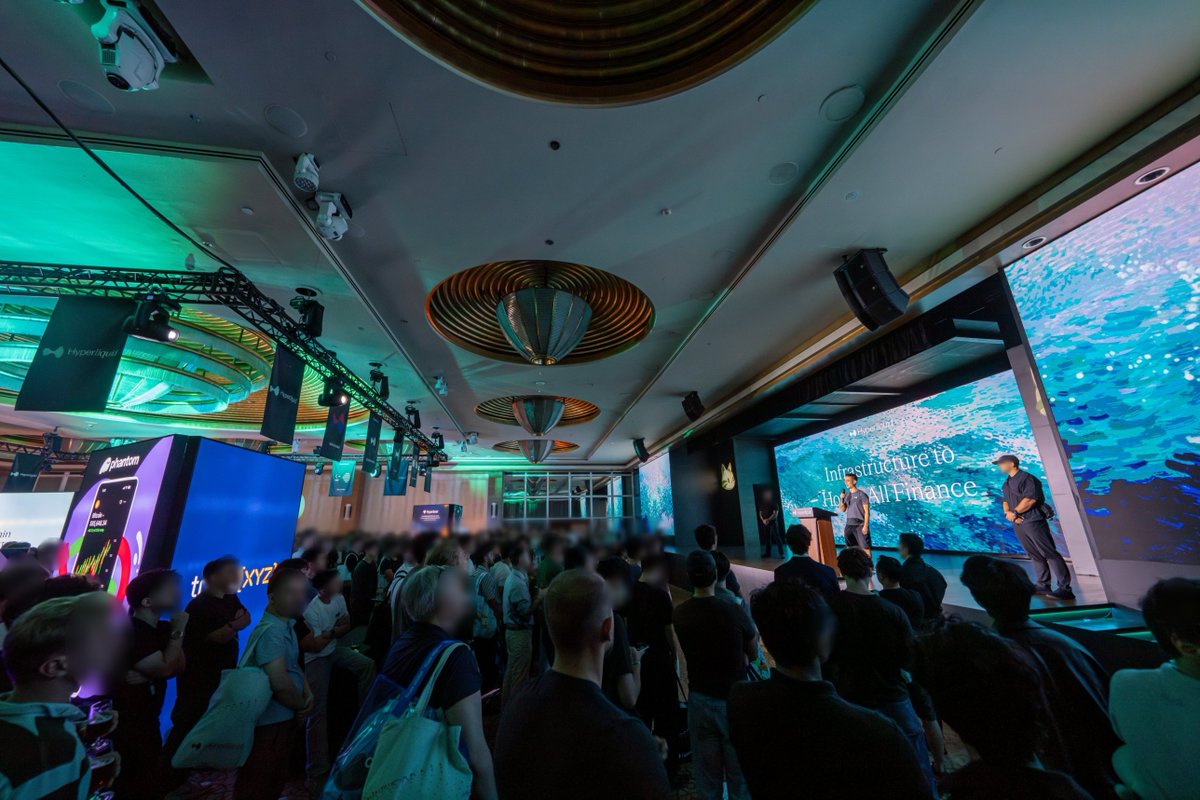
Thank you to everyone who traveled near and far to make it to Monday's community event. Multiple members of the ecosystem hosted their own events to celebrate Hyperliquid and the community throughout the week. Thank you to every organizer for the hard work and dedication behind each one.
The builder booths were a highlight for many. To everyone building on Hyperliquid: thank you for bringing more of finance onchain and spreading the word.
Since last year, even more builders, users, and institutions have contributed to the ecosystem's growth. Hyperliquid's vision is to be infrastructure to house all finance, and every year, that vision becomes more of a reality.
Most tech giants in the 2000s built their infrastructure and product as one entangled unit. Amazon had the foresight to separate out AWS as an API layer, of which Amazon retail was the first of many users. Today, AWS generates more profit than all of Amazon's other business lines combined.
Hyperliquid is built with the same philosophy. Housing all of finance requires thoughtfully designed, open financial primitives. Each primitive should obey the Unix principle of "Do one thing and do it well." Talented builders then have the foundation to chain these together to create magical applications.
HyperCore borrowing is an example to highlight this philosophy in action.
Most other platforms implement portfolio margin by marking an account's collateral to market value with an LTV haircut, creating borrowed assets without an explicit lender. This system is simpler to implement, but misses a golden opportunity for composability.
Hyperliquid instead begins with a borrow/lend protocol on HyperCore. Every borrowed asset is sourced from a supplier, so risk is isolated within the borrow/lend primitive instead of platform-wide. HyperCore's portfolio margin system is implemented as an orchestration layer that composes borrow/lend, with other primitives such as perps, spot, and outcome trading.
This decomposition has several nice corollaries:
1. Today's announcement of manual borrowing is not a new feature, but simply an extension of the underlying primitive. Borrowers on day one have access to 400M and growing of supplied liquidity.
2. Portfolio margin users earn interest on their idle stablecoin collateral. This is not a new feature, but a natural byproduct of composing trading with lending.
3. System safety is easier to reason about when perp and borrow/lend margining are independent.
In the same way that math theorems almost prove themselves when the right abstractions are defined, composable designs just feel right.
Someone recently shared this paper with me, which rigorously studies the execution improvement of visible TWAPs on Hyperliquid: "Trading in the Sunshine or in the Shade: Market Impact and Adverse Selection on Hyperliquid," by Davide Barone and Fabrizio Lillo.
In physics, theorists can say all they want, but the case isn't closed until an experimentalist comes with the cold hard data. So thank you to the authors of this paper for their hard work! The paper demonstrates that liquidity net tightens as onchain TWAPs surface, improving the average execution of the TWAP order.
This has been a deeply personal question for me. Even before building Hyperliquid, I've defended from first principles that transparent trading ought to improve execution for non-toxic flow. This is a corrollary of the efficient market hypothesis, but the amount of pushback always surprised me. I've quote tweeted a previous post where I make the argument in detail.
Transparency and equal access bring improved execution over traditional private venues. It's an honor to build with everyone to upgrade the financial system with onchain technology.
i put 5 figures of liquidity on @NestExchange in late 2025 and kept compounding $nest rewards into a lock.. my position is now worth 6 figures
shocked the user base is still so tiny