Stephen Dopp welcomes Empower’s Joe Smolen to The Glide Path for a look at recordkeeper consolidation, fintech competition and the trends shaping retirement, from private assets to pooled employer plans.
Subscribe on @Spotify@ApplePodcasts@amazonmusic
https://t.co/SRnwuV1fzh
Mayberry and Kimbrough go through the latest S&P Global U.S. PMI numbers: a very strong report with very strong inflation.
🎙️👉https://t.co/e5rD7yTYff
DoubleLine’s Jeff Mayberry and Mark Kimbrough discuss a volatile week for the markets, including what could prove a tech stock mini-run, on the latest Minutes. 🎙️👇
https://t.co/jvmcpo5g3r
Financial Services Review discusses DoubleLine Capital’s pursuit of opportunities amid “a secular transition into a world of higher interest rates, higher risk premia on G-7 sovereign debt and a break from 40 years of disinflation.”
https://t.co/Y8dNPJ4TAL
The BEA's July PCE revision wasn't new disinflation; it was a methodological reclassification that left consumer prices unchanged while cutting reported core inflation by 36bps, the largest such adjustment in recent history.
https://t.co/jc3Dgy2LWo
The Pending Home Sales Index – a forward-looking indicator of home sales based on contract signings – declined 7.3%MoM in September to 66.0, an all-time low.
High yield investors are asking 5.6x the extra yield on the weakest credits as on the stronger ones, one of the widest gaps in 30 years. So far, the weakness is concentrated in a small group of troubled borrowers rather than spreading broadly across the market.
https://t.co/rQRxviK97O
“Investors are thinking of putting money to work in lower-risk securities yielding 5%-6%,” says DoubleLine Portfolio Manager Eric Dhall, who sees “a connection between the Oct. 12-16 rally in fixed income and indigestion with the AI buildout.”
https://t.co/tgYhENMAPt
DoubleLine Allocation Strategist Ryan Kimmel notes “even though the cap-weight S&P 500 is down on the week” ended Oct. 16 “the equal-weight index is providing diversification.”
https://t.co/tgYhENMAPt
Answering the debate over the momentum in megacap tech and corresponding narrowness of stock market leadership, Dhall and Kimmel have authored a new paper on strategies to diversify investors’ equity allocations.
📰https://t.co/FjB9UCQR8T
🎙️👇https://t.co/3kWyICNPAE
Notwithstanding tech dragging the tech-dominated S&P 500 lower, DoubleLine’s Eric Dhall and Ryan Kimmel note a healthy broadening in stock leadership for the week while bonds, abetted by a short-squeeze on rate-hike betters, eked out plus signs.
https://t.co/3kWyICNPAE
DoubleLine’s Bill Campbell joins @BloombergTV to discuss AI credit risk, the case for higher quality credit and the belly of the curve and where we still see value in emerging market local debt.
https://t.co/2EIPxckLC7
France now pays more to borrow than its own banks do, which is deeply unusual because governments are normally seen as safer. With debt near 120% of GDP and interest costs set to double by 2030, the bond market is sending a stark warning about French finances.
https://t.co/Y7qgG6wGm4
DoubleLine Deputy CIO Jeffrey Sherman joins CNBC after a hot CPI print to discuss the Fed, stress in AI financing and our focus on short duration credit and the belly of the curve.
https://t.co/GzCOImAhpf
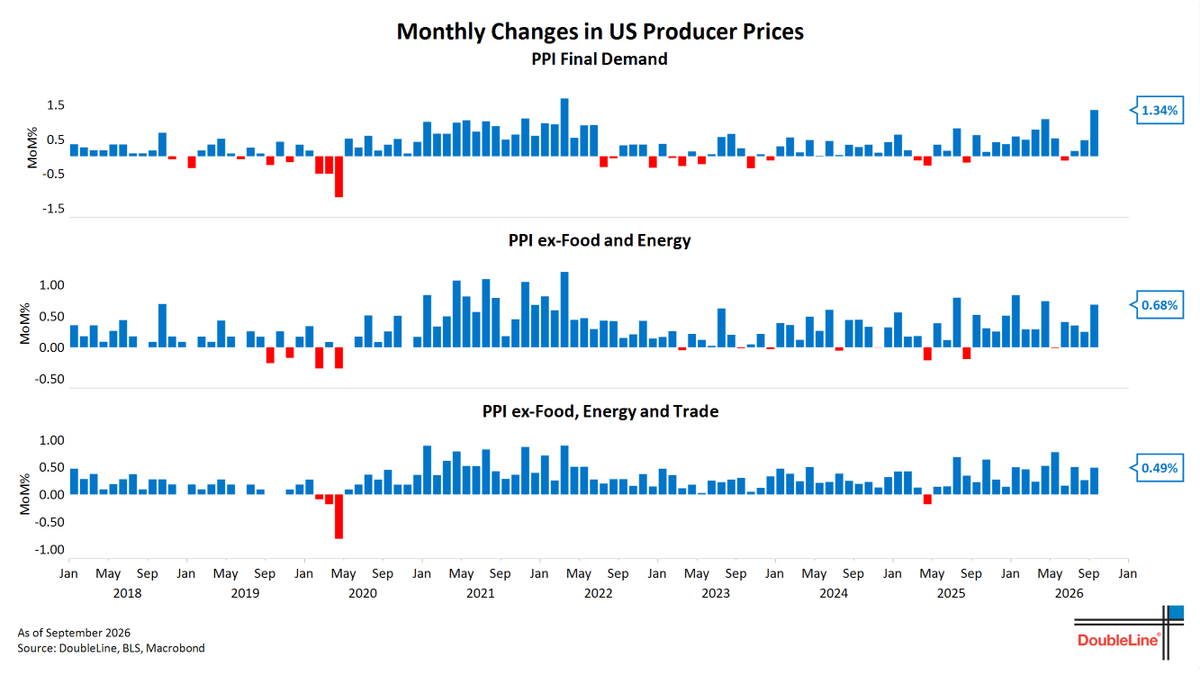
The September producer price inflation data was hotter than expectations. Final demand +1.34%MoM vs. +0.6% consensus and +0.47% the previous month. Year-over-year accelerated to 6.34% vs. 5.4% consensus and 5.6% the previous month.
Core PPI (ex-food, energy, trade) +0.49%MoM vs. 0.3% consensus and +0.26% the previous month. Year-over-year core PPI rose to 5.04% vs. 4.7% consensus.
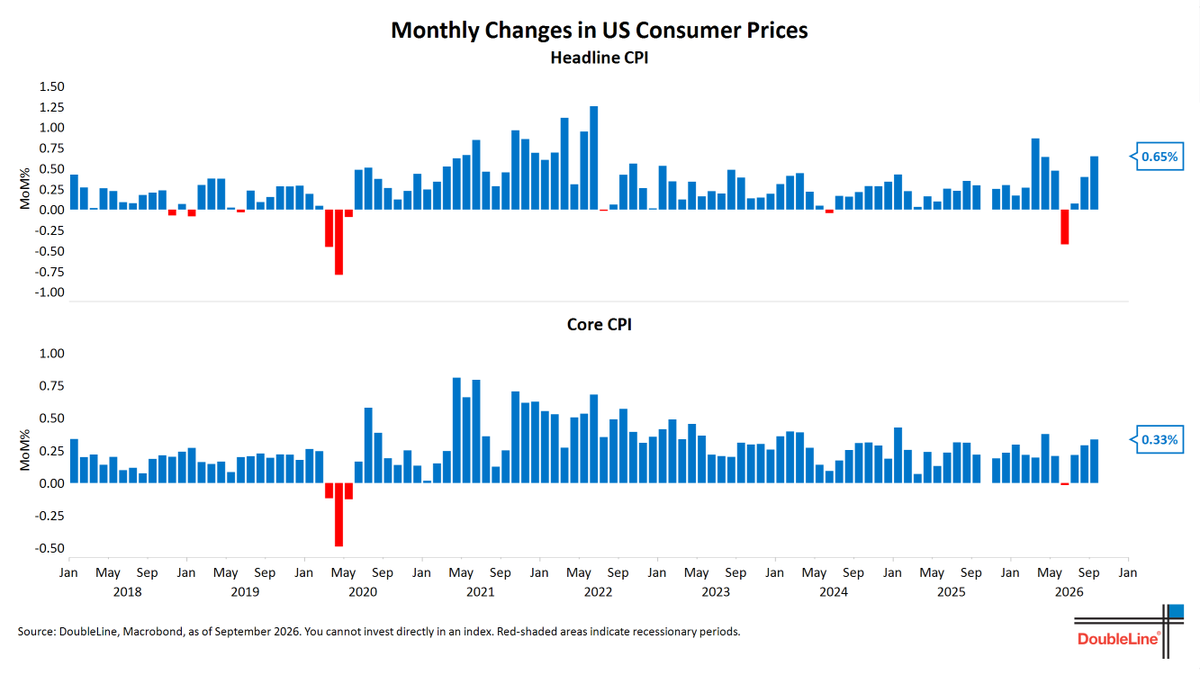
The September CPI report was hotter than expectations and inflation was broad-based, with headline CPI +0.65%MoM vs. 0.6% consensus, and the year-over-year pace rose +0.3% to 3.7%YoY vs. 3.6% consensus.
Core CPI was higher than expected, rising 0.33%MoM vs. +0.2% consensus; year-over-year accelerated to 2.6%YoY vs. 2.5% consensus, and 2.4% the previous month. Core’s 3-month annualized pace at 3.41%, 6-month annualized pace at 2.85%
Core services inflation accelerated to +0.37%MoM; +3.1%YoY; shelter a big driver rising to+0.39%MoM from 0.26% the previous month; airfares remained strong +1.16%MoM
Core goods inflation ticked higher to +0.25%MoM in September; +0.7%YoY; used cars and trucks accelerated to +0.67%MoM.
112 basis points. That's how far the 10-year yield has risen through September 2026, nearly matching the 110bp surge that peaked on Oct. 19, 2023, and marking seven consecutive months of higher yields, tying a 50-year streak.
https://t.co/70e6kEfOlV
DoubleLine's valuation and equal-weight equity strategies complement investors’ exposure to the S&P 500, which owes nearly 40% of its market cap to the information technology sector and more than 40% to just 10 stocks.
https://t.co/yC1K0aLPMN
Diesel and 30-year mortgages rarely share a narrative, but both are now approaching a 7 handle because the forces driving them higher increasingly trace back to the same war.
https://t.co/kQJrEbv4fn
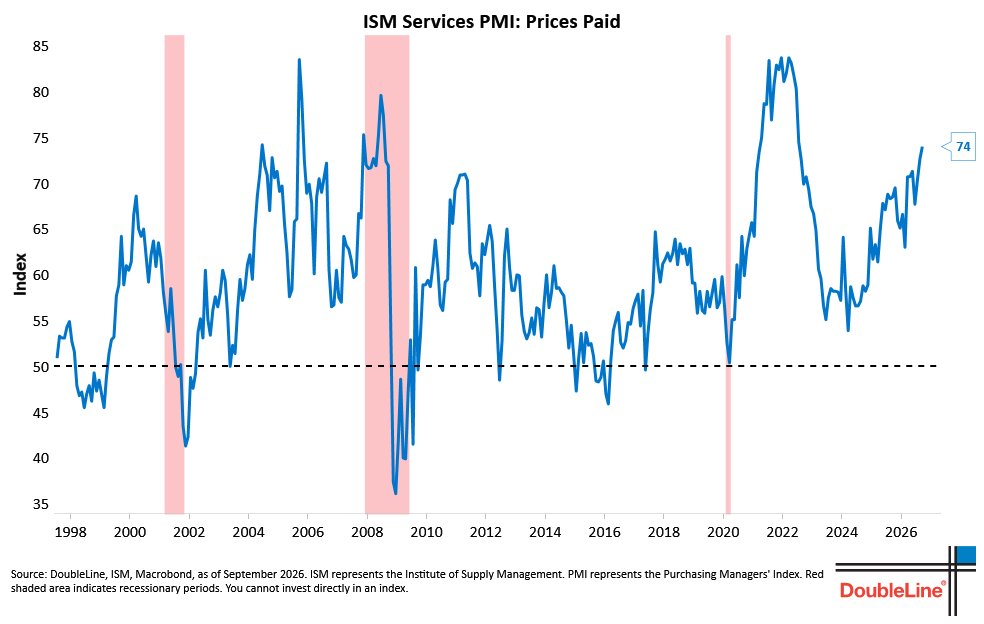
The September ISM services report came in strong and expansionary, with rising employment to address order backlogs, “but the hair on the report,” Mark Kimbrough notes, “is the prices metric pushed up to 74.0, the highest since July 2022.”
👉https://t.co/rhHAP9XtR1