@randomGump Not bad execution just unfortunate government policy changes. They have upgraded the German booths but are waiting to be certified. Japan is shifting to online applications which accept photos from phones.
Trading Update #MEGP $MEGP.L
-Slight miss, due to unusually hot summer weather
-Added "adjusted" to the PBT forecast which they didn't have before - Actual PBT a bigger miss.
-Capitalise £37m in shareholder returns at 10% gives £370m valuation, roughly what we are at today.
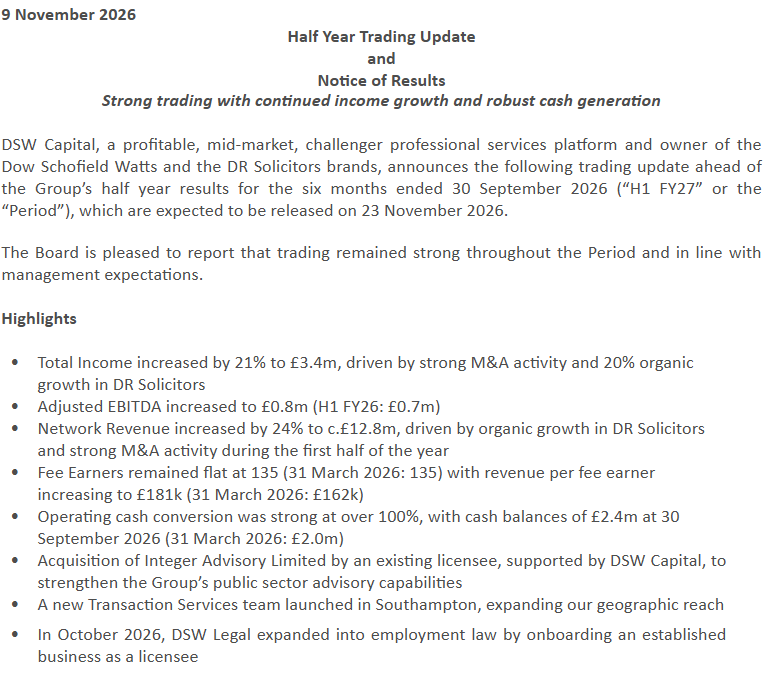
Solid Update #DSW $DSW.L
- Impressive 20% DR Solicitors growth
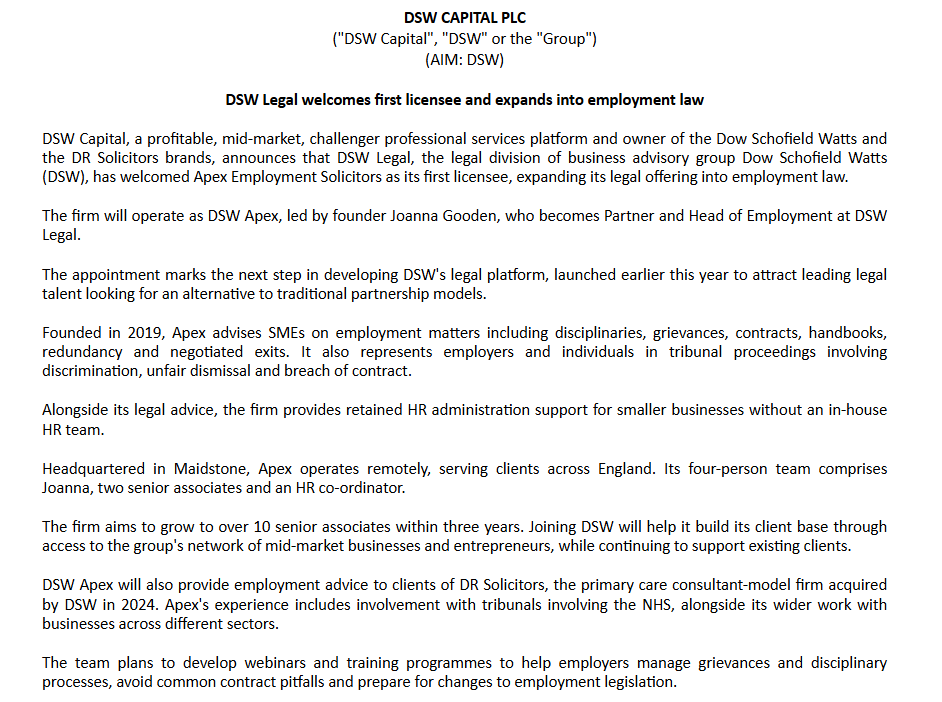
- Nice expansion of service lines
- No Fee Earner growth is a worry, but its being masked over by higher revenue per fee earner.
- 7% dividend yield, 13% FCF Yield.
@XIX_Value Well no, its essential they use the cash. If the cash sits there forever, then you have paid for that through your equity purchase with no return on that investment. So the only return you get for paying £11m of equity is £0.57m of FCF and therefore a 5% annual return.
Share price has been killed this year due to the shift to lower margin revenue, but relying on meta ads (indirect revenue) is not sustainable and I like the new strategy. I don't like advertising industry but this is too cheap 6x FY27 owners earnings, and growing 15%+.
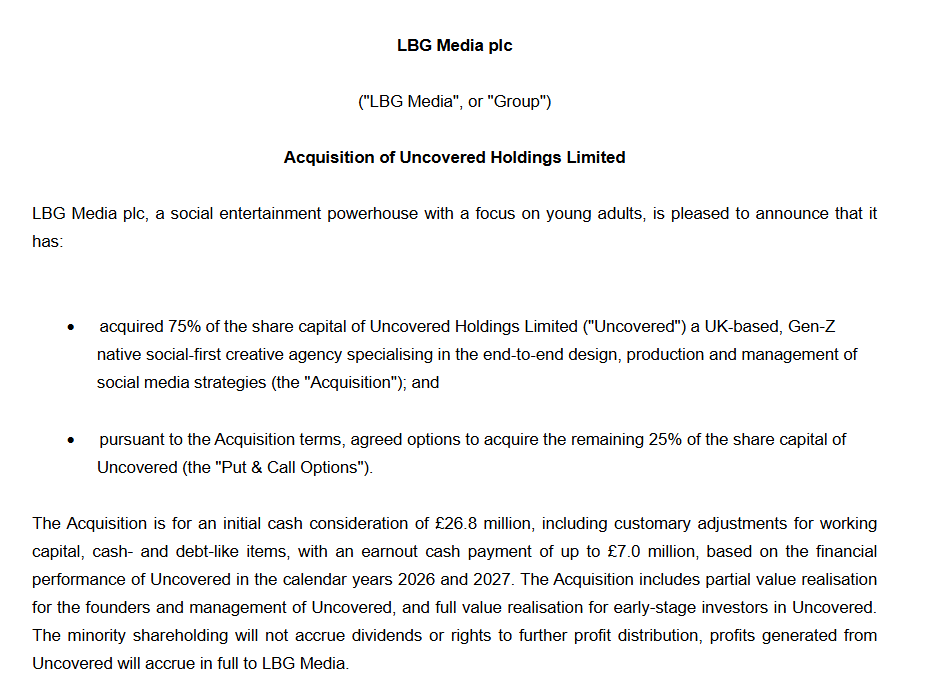
Acquisition by #LBG $LBG.L. LBG has made a pivot from indirect (higher margin) to direct revenue (lower margin). Direct revenue is normally on a retained basis with clients such as Google, Dominos etc, although lower margin it offers a greater degree of certainty of revenues.
Also while only owning 75% of shares, they own 100% economic interests, this allows LBG to use uncovered free cash flow to pay its own earn out, sort of vendor financing if you like, which is great for LBG as it is interest free.
@detector_trader Highest since 2017 not more than 2017, still forecasted for £570k PAT, which is still technically the highest since 2017. Also the £1m in cash isn't 'free' as it is needed as a buffer for the extremely high payables.
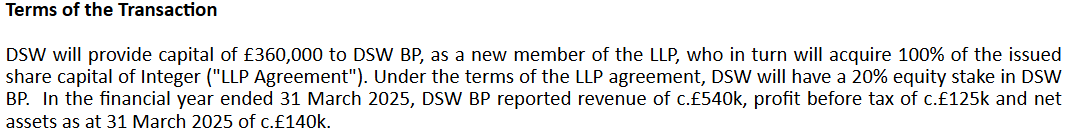
DSW Capital paid £360k to acquire 20% of DSW BP, which implied an equity value of £1.8m and valuation of 3x Revs, 14x PBT. This seems rich on the face but this is based on 1. Last years financials 2. Don't include any of the Integers financials.
$DSW.L #DSW provided £360k equity funding to support its licensee's acquisition of Integer Advisory Ltd. This expands DSW footprint in housing and public sector advisory. Lots of tailwinds in this sector but as with all government advisory, elections can impact timing etc.
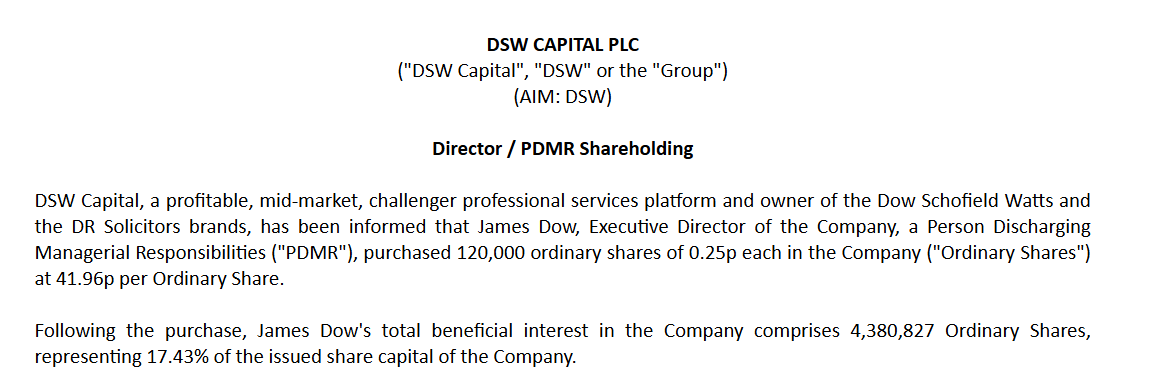
Big insider buy at #DSW $DSW.L
Legal services is the growth opportunity now. It seems M&A side has become more of a windfall in a good year and no so much damage in a bad year. Much more sustainable profits expected. 7.5% dividend yield when we wait.