We started @column with the insane idea to rebuild every component of the financial system from scratch. Today, I think we've finally completed that build.
We're releasing four new products, so any technology company can build at the frontier of financial services.
The London Stock Exchange will put its 100 biggest stocks onchain, with Kraken's parent company Payward.
In the coming weeks, the FTSE 100 will become xStocks. These are tokens backed 1:1 by real shares, trading 24/7 on exchanges, in self-custody wallets and across onchain apps in 110+ countries.
(Except the UK. Brits can't buy them yet. The FTSE, tokenized for everyone but Britain. That's because xStocks are issued by Backed Assets (JE) Limited, a Jersey company, and offered to Kraken clients via Payward Digital Solutions Ltd, which is licensed in Bermuda. They are not stocks, they're offshore unregulated instruments as far as the FCA is concerned)
xStocks is a product created by the Kraken parent Payward that turns regular stocks into tokens, and lets them trade onchain. xStocks did $40bn of volume in just over a year with nearly $20bn settled onchain to over 200,000+ holders.
The UK could get proper stock tokens soon. The LSE plans to list them on LSE 24, its new 24-hour venue. LSE and Kraken will explore shares issued natively onchain, with the same rights as traditional stock.
Tokenized stocks are coming globally, but there's nuances here.
In December, the SEC cleared DTCC to tokenize assets it already custodies. Approved wallets only. Sanctions screened. DTC keeps the power to mint, burn or forcibly move any token.
But that token stays inside the vault. The LSE version puts the token in your wallet. And native issuance asks whether the chain can be the register itself.
That's a completely different market structure.
London spent a decade losing listings to New York.
Competing on plumbing might be the fight it can actually win?
42 Best Coffee Shops in the World: Our 2026 Picks https://t.co/lz5oA9sPbn
Great selection of Coffee Shops in the World.
Which ones do you like and which should be added?
via @LuxuryColumnist
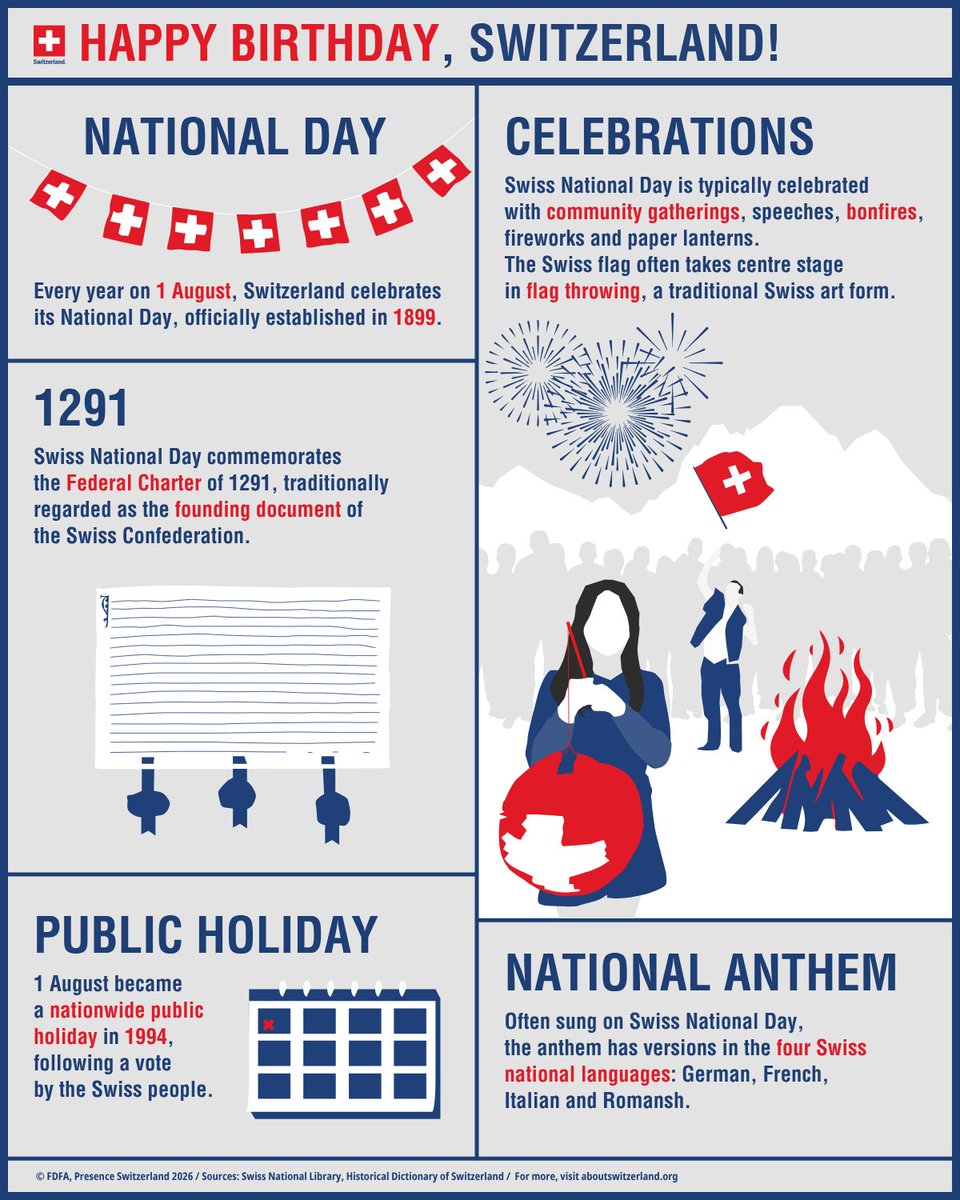
🇨🇭✨ Happy Swiss National Day!
Today we celebrate Switzerland’s traditions, diversity and innovative spirit — from our communities at home to Swiss connections around the world.
Wishing everyone a joyful 1 August! ❤️🤍
#SwissNationalDay#1August#Switzerland
Bonfires, fireworks, flags and four national languages: Swiss National Day is more than a celebration. 🔥 🎆 🇨🇭
It is a moment to honour Switzerland’s history, diversity and sense of community. 🤝
Discover what makes 1 August so special! ✨
Wow: Stripe and Advent have bid more than $53 billion to take PayPal private. 🤯
This is the biggest story in payments I can remember, and I write about payments for a living.
The details, per Reuters:
- $60.50 a share
- a 28% premium, backed by roughly $50bn in committed bank financing.
- Stripe and Advent would own PayPal 50/50 and keep the company whole.
- The first approach was April. PayPal hasn't responded yet.
The timing is poetic.
Last year was the first year Stripe's payment volume passed PayPal's. $1.9 trillion vs $1.79 trillion. The challenger passed the pioneer on volume, then went straight for the whole company.
Same volume, wildly different price tags. Stripe's tender offer in February valued it at $159bn.
PayPal peaked at $360bn in 2021 and just got bid at $53bn.
The gap is the growth rate: Stripe grew 34% last year, PayPal grew 7%. Growth is everything.
Advent's name in this deal tells you as much as Stripe's does. PayPal generated ~$6.4bn in adjusted free cash flow last year, so $53bn is roughly eight times cash flow.
That is private equity maths. Advent takes on the turnaround of a 23,800-person company.
And Stripe? Stripe spent 15 years building the merchant side of the internet. PayPal hands it the consumer side: 439 million active accounts, Venmo, and the yellow checkout button consumers know on sight.
If this closes, one company touches $3.7 trillion in annual payment volume. Around 3% of global GDP and would be by far the largest US merchant acquirer by volume.
My questions
- Can anyone fix the back end mess of PayPal?
- It's employee heavy, I image a lot of layoffs would be required?
- Is this actually a distraction for a very healthy growing Stripe?
- Would you keep bits and jettison others?
I get the attraction to the raw volume and assets. But underneath is a mess of company M&A and systems that never got fully integrated. Doing that is hard and not for the feint of heart!
There is no certainty it happens.
But someone just put $50bn of committed financing behind the idea that PayPal is worth more off the stock market than on it.
Discl: Stripe sponsors my podcast, opinions 100% my own
🚨 BREAKING: Erebor is at $4.05bn in deposits, per Bloomberg. Their March call report said $1.1bn.
Nearly 4x in a single quarter, for a bank that only got its full national charter in February. They're now in talks to raise at an $8bn+ valuation, up from $4.35bn in December.
Founded by Palmer Luckey. Backed by Founders Fund, 8VC and Lux Capital. They went from OCC application to full charter in roughly 9 months. Paxos, Ripple, Circle and Stripe have all filed for trust charters. None of them operates a full depository bank.
Three details buried in the Bloomberg reporting:
1. They added roughly 400 customers this quarter while deposits grew ~$3bn. Even if every new dollar came from new customers, the average account is north of $7m. A small number of very large depositors, nearly all above the FDIC cap.
Sound familiar?
2. Demand for crypto-backed lending came in *below* their expectations. The product winning is the boring one: a deposit account that stays open.
3. Luckey went out of his way to say none of this quarter's growth came from his own companies. When the CEO pre-empts that criticism, you know it landed the first time.
My read: after Chokepoint 2.0 and SVB, "we will bank you" is the product. The charter is the moat. The 24/7 stablecoin rails are features.
And yes, fast-growing, concentrated, uninsured, correlated deposits are exactly the shape SVB was. The difference so far: per the Q1 call report, Erebor holds zero loans. It's operating closer to a narrow bank than a lender.
$8bn on roughly $1bn of equity is ~8x book. JPMorgan trades at ~2.4x.
Investors are pricing a bank charter like software.
I founded Penta one of Europe's largest neobanks during the first wave of neobanking in 2016. We launched in 2018, and went from 0-60k customers, and a 9 figure acquisition 4 years later.
Here’s the playbook for how to build a neobank in the 2nd wave of neobanking:
From 0-1.
1. It’s all about distribution. If you don’t have an unfair distribution advantage you will lose. Advertising is not an unfair advantage.
2. Focus on a niche. Build a monopoly in that niche. Expand to other niches.
At Penta, we focused on companies that were incorporating, they needed a specific type of bank account. We made signing up take 10min, compared to 4 weeks. That was our initial PMF wedge.
3. CAC/payback period is critical. If you’re not paying your CAC back within a reasonable time frame (<12 months max) you’re going to hemorrhage cash.
4. Engagement and retention is your #1 metric. 10% is average retention/activation for D2C neobanks.
<25% for B2B neobanks. That is garbage. Users who are active are your real number of customers, not the ones who signed up and are dormant.
Optimize for >50% retention defined as a minimum of 2 transactions per month.
5. Your onboarding funnel is your most important acquisition channel.
It’s not only about top of funnel. Mid and end of funnel are probably more important if you have top of funnel even slightly even figured out.
The whole company should be focused on optimizing the funnel from visitor -> lead -> customer -> active customer. Read about AARRR.
6. Churn should be below 2%. Card programs enable high retention. Customers don’t switch banks, when’s the last time you switched banks? Make sure that aligns with your metrics.
7. Focus on the power users, then find more of them.
Break user engagement groups into 4 buckets, 25% least engaged, to the 25% most engaged/power users.
Focus only on the top 2 buckets while trying to convert the bottom 2 into the top 2 buckets. What behaviors do the power users have that the other buckets don’t?
Force that UX and those behaviors on the other 3 buckets, which makes more power users.
8. Focus on B2B niches instead of B2C, unless you have a unique problem in consumer you’re solving which enables a low CAC, better distribution, and better economics.
Most don’t. B2C is typically full of fraud and typically makes no money. FX worked in the first wave of neobanking (Wise/Revolut) but isn’t a USP anymore. Find a niche.
9. Get to scale in 1 geography. Not multiple.
From 1-10.
I’ve seen what a 0-1 looks like, and then what 1-10 looks like.
When companies hit scale, most plateau (ie: Brex, N26). Others like Revolut turn into $100B+ outcomes.
10. Your best new customers are your existing customers. Make your current customers happier. That also means higher NRR and ARPU.
11. Neobanks are card companies + deposits.
That’s what you do. Increase card spend which equals retention which equals higher deposits. Launch treasury products as a result. High yield keeps customers, and steals customers away from others. Steal customers.
12. Don’t get into lending until you’ve crossed a large number of deposits. Lending only works for your top 10% of customers, and only 20-30% of those will actually want a loan.
When launching a lending program, don’t lose money. Focus on quality.
13. Fire the bottom 10% of performers. Your company will swell and reduce speed and therefore quality. Keep the team sharp. This is a silent killer.
14. Don’t hire for experience, hire for hunger.
15. Move fast, test things, and fail fail fail.
The more you fail the more you’ll succeed. Neobanks that become large become comfortable and they stop launching products that fail. You need to fail if you’re gonna launch a breakthrough. Look at Revolut, they have 20 projects running at once, maybe 1-2 will survive but they’ll be a home run.
16. Most importantly, don’t focus on the competition. Focus on your customers. Talk to your customers every single day. You’re more likely to die of suicide than murder, so forget what others are launching or doing. Focus on your customers.
If you’re building a neobank, let me know what I’m missing!
🚨 BREAKING: 100+ companies just backed Open USD, a dollar stablecoin run by a new independent company, Open Standard. Zach Abrams is interim CEO.
Five-minute reaction (and personal views only.)
The instinct is to count the logos when you see a lot of them. The design choices matter much more.
- No mint or redemption fees by default
- No arbitrary caps when you scale from $10k to $10m
- Reserve yield shared by default (issuers used to keep it)
This is clearly about scale, and going after the larger, industrial-grade payments volume.
Open Standard runs like a financial market infrastructure. It remids me more of things like SWIFT, the card networks, the clearing houses. Owned broadly, governed by a board, a little "boring" on purpose.
---
Credible neutrality is the whole game.
One company's coin is a product. A coin a hundred competitors agree to share becomes a standard. The cap tables of SWIFT and the early clearing houses were the incumbents of their day in one room. This rhymes.
Look at the breadth too. Banks, card networks, crypto natives, fintechs, big tech, on one coin. A global PSP, a community bank, an international long-tail player. Everyone finds an animal in the picture that looks like them. That breadth is the ultra significant bit.
---
For stablecoins to get beyond their current use cases, we needed something that got rid of the penalties for scale (like mint burn fees) and could handle massive volume.
Today's stablecoin use cases are a rounding error against what's coming. with ~$300B in circulation. SWIFT instructs an average of 5 to 6 trillions a day. The card networks settle trillions. Capital markets, QUADRILLIONS. The prize is moving those flows on-chain, 24/7, with the settlement guarantees regulated money actually needs.
If you build payments, capital markets or treasury, this is the rails question of the decade.
Read the design choices first. The logo wall is the easy story.
Europe’s top 10 FinTechs are worth over $200 BILLION 🤯
And most of that comes from one country..
From the top:
• 🇬🇧 @Revolut — $75B
• 🇳🇱 @Adyen — $36B
• 🇬🇧 @Worldpay_Global — $24B
• 🇬🇧 @SumUp — $15B
• 🇩🇪 @traderepublic — $15B
• 🇬🇧 @Checkout — $12B
• 🇬🇧 Admiral Group Plc — $12B
• 🇬🇧 @Wise — $12B
• 🇬🇧 @FinastraFS — $10B
• 🇬🇧 ION — $9B
A highly concentrated landscape, with a few standout players across Europe.
📷 Source: https://t.co/NrPJKolnVG
Which of these do you think will break away even further from the pack?
And, what is going to be the next European FinTech to break into this top 10?