These charts by the great @crossbordercap are for all the people out there that have been pointing to the "record corporate earnings" we are seeing.
Yes, corporate earnings have usually been doing well in mid-term years.
However, judging from history, this hasn't automatically translated into S&P gains.
These have usually done poorly during mid-terms.
So, maybe you don't want to count on corporate earnings to justify your bullishness for 2026!
Props to @JustDeauIt for drawing my attention to these graphs
𝗕𝗮𝗰𝗸 𝘁𝗼 𝗦𝘁𝗮𝘁𝗲-𝗗𝗿𝗶𝘃𝗲𝗻 𝗠𝗼𝗻𝗲𝘆 𝗖𝗿𝗲𝗮𝘁𝗶𝗼𝗻
The continuous emergence of stablecoins will inevitably prove that banks are no longer at the center of payments and liquidity. Their deposits are less sticky, funding is more volatile, and their role as gatekeepers of credit shrinks.
Now, if banks are indeed being curtailed in their ability to extend credit, what happens to economic growth and the business cycle at large? After all, bank credit is the fuel that keeps the economy running.
This is where a more state-driven monetary system might increasingly take up the baton from today’s market-based credit money system. Government will have to fill in the gap and increasingly act as credit creator and allocator of last resort.
On a spectrum, credit creation moves further away from efficient market-driven “decentralization” and more towards less-efficient soviet-style “centralization”.
This is because government officials tend to allocate capital less efficiently than bankers — not because bankers are smarter, but because they operate under strict balance-sheet discipline, deal directly with customers, and face competitive pressures from other banks. These incentives force banks to allocate credit more efficiently than government agencies ever could.
Read more: https://t.co/VoMzJWrVqZ
Indeed, the setup for a "relief rally" is there!
-Similar setup to early 2022, when Russia invaded Ukarine
-Downside protection is being bid (1w, 1m, etc.) put to call skew is positive
-A 25bsp cut is only priced at less than 20% by the market. Given that 2 year inflation swaps are at 2.22%, January rate cut odds seem mispriced
Let's see if we get this move up to 50 WMA...
While it is true that banks can create loans irrespective of deposits, they need reserves to settle with other banks.
Bank deposits represent one of the many ways to fund a loan. In fact, it is a comparatively cheap way of funding it. Other ways of funding include borrowing reserves, raising wholesale funding, tapping the repo market or selling securities outright.
These options are more expensive and less stable, making credit extension harder at the margin. Deposits from a giant corporate depositor like stablecoin issuer are more concentrated and may move money quickly between banks or into other assets.
So, while credit creation does certainly not become impossible, it becomes more expensive, which can discourage credit creation at the margin.
Another “issue” for banks’ profitability to extend credit arising from increasing stablecoin proliferation is the fact that stablecoin issuers act as “collateral silos”. To this date, stablecoin issuers have been siloing short-term treasury bills to the tune of $180 billion. This not only traps high-powered collateral inside stablecoin vaults, but also likely reduces collateral velocity. Ergo, banks will have less Treasury holdings as collateral to repo or sell them to fund lending.
Because stablecoin issuers tend to hold deposits at a few large custody banks, it is smaller/regional banks, which will struggle more. Credit creation ultimately becomes more concentrated in big banks or in capital markets. The great “consolidation” among banks will keep going.
Read more: https://t.co/VoMzJWstgx
𝗠𝗮𝗻𝘆 𝘀𝘁𝗶𝗹𝗹 𝗳𝗮𝗹𝗹 𝗶𝗻𝘁𝗼 𝘁𝗵𝗲 “𝗻𝗼𝘁𝗵𝗶𝗻𝗴 𝗰𝗮𝗻 𝘀𝘁𝗼𝗽 𝘁𝗵𝗶𝘀 𝘁𝗿𝗮𝗶𝗻” 𝗰𝗮𝗺𝗽.
While we believe that in the long run, nothing should indeed be able to stop this train, meaningful slowdowns are still very possible over shorter horizons. In fact, periods of 6 to 12, and potentially even 18 months in which the market materially “hits the brakes” should not be ruled out.
And it looks like, as if these brakes are being hit now. Compared to the start of the last fiscal year (starts in October of each year), 2026 is already tracking slower. As the deficit tracker shows, the cumulative federal budget deficit through November 2025 was $458 billion, down from $624 billion over the same period of the prior fiscal year, a decline of nearly 27 percent.
Both charts below indicate that deficits are narrowing on an underlying basis, which means that the fiscal impulse is fading.
Read more: https://t.co/zbmb5XqDwD
@AugurInfinity
The Daily Degen - Friday, January 2nd, 2026
Ideas, Predictions, Opportunities, Airdrops, Macro, Videos, + New Projects!
Shout-out to mentioned projects and tickers: $BTC, $PENDLE, $JUP, $TON, $QUAI, $MSTR, $ETH, $FLUID, @Axios_finance, @QuaiNetwork, @quickscope_gg
Shout-out to brilliant accounts mentioned with <10k followers (make sure to give them a follow!):
- @ChristopherGLHF (general Chad-maxxed cryptobro'ing)
- @leviathan_news (fantastic news + defi livestreams)
- @ryanconnor (general crypto gigabrainage)
- @pahueg (one of best crypto/macro podcasts on YT)
And please RT/etc to support!
Link in next tweet 👇
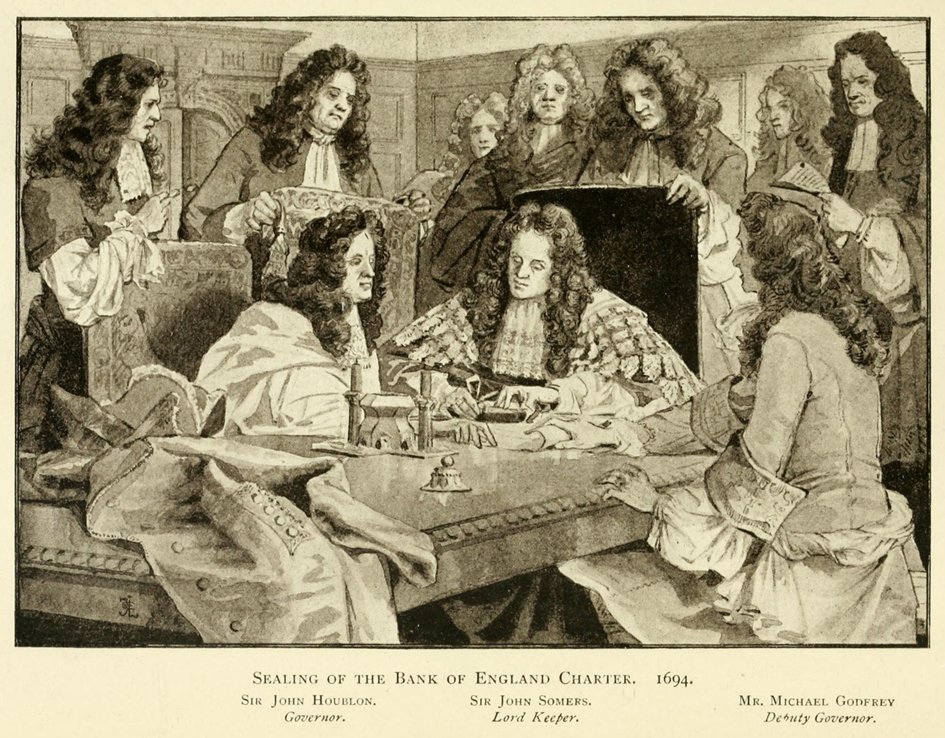
𝗧𝗵𝗲 𝗿𝗼𝗼𝘁𝘀 𝗼𝗳 𝗼𝘂𝗿 𝗺𝗼𝗱𝗲𝗿𝗻 𝗺𝗮𝗿𝗸𝗲𝘁-𝗯𝗮𝘀𝗲𝗱 𝗰𝗿𝗲𝗱𝗶𝘁 𝘀𝘆𝘀𝘁𝗲𝗺 go back to the late 17th century, when the Bank of England was founded.
With the creation of this “revolutionary bank”, as it was also called in its early days, bankers and merchants (creditors) joined forces with kings and rulers (debtors). The bank marked the beginning of an alliance between private and state interests, between creditors and the public debtor, or more generally between the market and the government.
Started as private bank to finance the sovereign, the Bank of England became the prototype for future central bank. Through a series of charters granted by the English crown, the bank consolidated ever more power.
The result was a continuous concentration of all monetary and banking affairs in the Bank of England. Over a century later, in the debate around the Peel’s Bank Act (1844), some argued that the free-market forces had led to the Bank’s dominant position. They put this argument forward to promote the total centralization of banknote issuance in the Bank of England, ignoring all the competitive advantages the charters had granted to the bank.
Over the course of the 18th and 19th centuries and into the 20th century, today’s market-based credit money system took form. In response to crises, many countries outlaw private banknotes and force the use of central bank–issued notes, creating the first separation between “public” and “private” money.
Commercial banks took over the responsibility of issuing deposits, thereby extending credit, while central banks became responsible for providing physical currency and reserves.
Today, we have a globalized banking system, which is complemented by so-called shadow-banks. Private credit creation is done by banks in a fractional reserve manner, meaning that monetary claims issued as liabilities by banks and shadows banks are only fractionally backed by central bank reserves.
However, this is rapidly changing as we speak. Enter stablecoins.
Read the full article here: https://t.co/VoMzJWrVqZ
Here's my episode with @ramahluwalia
https://t.co/bVtF51d4L4
We talk about:
-State of macro
-Fiscal Dominance and Government Spending
-Trade Deficits and Capital Flows
-Emerging Markets Opportunities
-AI: Bubble or Not?
-Bitcoin's Current Struggles
@BitBoxSwiss is the hardware wallet I personally trust and use!
To me, they are best in class! Get a 5% discount by using LNMS code!
https://t.co/dFzREA8SYS
𝗔𝗯𝗼𝘂𝘁 𝘁𝗵𝗮𝘁 𝗴𝗹𝗼𝗯𝗮𝗹 𝗰𝘂𝘁𝘁𝗶𝗻𝗴 𝗰𝘆𝗰𝗹𝗲 𝗶𝗻 𝟮𝟬𝟮𝟲…
To us, it looks more likely that the cycle is coming to an end (and is not accelerating). In fact, central bank decisions in Europe and beyond highlight a waning impulse for monetary policy action.
A glance at market rate expectations for G10 central banks shows that only three, the Fed, Bank of England, and Norges Bank are expected to cut next year. Others like the Swiss National Bank or Riksbank are likely to pause, while the Bank of Japan, the Bank of Canada and Reserve Bank of Australia might even be looking to raise rates.
Looking at the chart below, it is hard to escape the impression that the blue line, which tracks the share of central banks whose most recent policy move was a rate cut, is beginning to roll over. At the same time, the red line appears to be turning higher again, suggesting that globally rate hikes could be in store for 2026.
Such a trend would represent a headwind to the bull’s argument.
Read the full article: https://t.co/zbmb5XqDwD