Macro Equity PM | Dartmouth Fball ’08
“Be bold, and mighty forces will come to your aid.”
Views expressed are solely my own and not on behalf of my employer.
DratchCap Mkt Update. Some thoughts and self criticism.
Been a brutal couple of weeks. An equal-weight AI basket I track fell ~24% in seven sessions vs ~6% for QQQ, which was the worst 7-day window in five years, worse than DeepSeek or July. Thinking about my own mistakes, I did not respect price action and rates enough, especially given the financing reflexivity broadly. Index shorts did start to work but I did not press the way I should have. Another lesson re-learned.
In these types of environments I take things day by day and look for ways to improve the shape of the portfolio. Sometimes options structures line up well for that and can be good stock replacements. Stay in the game, reduce the tail.
Prior to this AM, things looked aggressively oversold. De-grossing has been material (see MS HF data today, last week 3-sigma event) w/ AI long/short near 5yrs lows.
From here, I think the bigger near-term risk is macro. People have been hiding in quality, and the systematic community is still long because the index has held up much better. If the quality rolls, there's plenty of room for the index to catch down.
Meanwhile, the tech demand indicators I'm tracking remain extremely strong. GPU availability is near its lows, rental rates are rising across chips and tenors, and TSMC is stepping up multiyear investment. Recent buildout data points (@SemiAnalysis_ today) are also encouraging. And my recent lab checks have been very strong too, with newer models driving demand and more capacity finally coming online.
At the same time, the market is treating funding as broken across the board. But the big platforms can still raise at prices that make sense given their ROI / ROE and strategic imperatives. A lot of the neoclouds are also financing against contracts and prepayments from those same customers.
Some valuations are also getting extremely attractive. Memory is a good example. Demand is compounding much faster than supply, pricing is going up, and yet the stocks trading near historical trough on fwd book w/ 30-50% type FCF yields.
As for the rest of the year, there is a Mountain of Worry to climb...
Strong megacap prints (soon) and better lab data could get people front-running the November seasonal (predictable AI era pattern). And that loop can feed FOMO into the Anthropic IPO. Expectations there have reset and HF positioning is now light in AI.
Add in the potential for the Fed to hold, power deals to start clearing post midterms, or some relief on the war and rates. We don't need everything to go right but a few will do.
I like to think of the AI buildout era as a super boom w/ mini busts along the way, often when price drives narrative. The mkt is more vulnerable to that than ever bc of new fast info channels (X), and the intangible and exponential nature of the tech. Human's aren't wired to think that way, and skepticism is always more cosmopolitan. On top of that a lot of the people making the big decisions are removed from the details and don't use the tech day to day, so when the tape turns they have limited first principles to fall back on. Staying the course during these moments has been right each time and I think that will prove true again.
Good luck out there!
I don't think it's a FinX / retail thing
I think PMs are just as susceptible
The issue is the sheer volume of information and the (perceived) need to process it in real-time
It started in 2020 when everyone went terminally online and it's only gotten worse as more investment convos have moved onto X
X on net is an incredibly powerful platform, but it's changed the way news gets processed in real-time and limbic systems weren't built for it
Pair that w/ algos and you've got a cocktail of volatility around every event
Lots of hedge funds and macro PMs got blown out during October
And the volatility is only going to increase as people outsource more investment thinking & judgment to AI
The under-underwritten thesis (b/c it was outsourced to AI) will crumble under the weight of a panicked limbic system every time
FinX is the wild west. Last night we learn the big spenders are trying to stuff themselves with HBM and extend LTAs. Today we have "omg this qtr missed 10% on capex!" My neck hurts...
"Capex came in light in the quarter" for the hyperscalers tonight is a misread. Goog had a delay w/ TPU v8i (see AVGO last qtr). MSFT changed definitions, add back new operating leases and it's spending the same. Silly.
"Capex came in light in the quarter" for the hyperscalers tonight is a misread. Goog had a delay w/ TPU v8i (see AVGO last qtr). MSFT changed definitions, add back new operating leases and it's spending the same. Silly.
All this new info today has me wondering what runaway RSI is worth? (Great take attached below as well)
ANT’s S-1 suggests it’s kind of a lot…
First, capability drives everything, from that beautiful rev per dollar of compute chart below to diffusion. As models improve, the opportunity cost of waiting to adopt goes up AND the cost of integration goes down. The part where the AI's own improvement helps make it easier to integrate ("hire itself") is lost on many. It’s partly why I think adoption is a “reverse bankruptcy” in waiting (slowly and then all at once).
Now imagine RSI shatters the open source “6mo behind” credo. Suddenly, open source and other frontier models are expensive in the context of the work they can’t do. Better share and pricing for the lucky winner…
But that capability gap also means negotiating power. ~1/2 of ANT’s revenue runs through marketplaces. My read of the S-1 puts the clouds’ current cut at ~40% of gross profit on those sales.
ANT’s already building out its own compute. Add a bigger capability gap and a war chest to fund more of that buildout, and that smells a lot like a lower vig for the clouds in the making. While we don't know the terms of each agreement, I think it's a good bet there's either sunsets, outs, or other renegotiation triggers.
Put all this together and RSI is potentially a legendary parlay.
Some napkin math. Rev / $ of compute was $2.08 in 2Q. Assuming other operating costs at 15% of revenue, a simple model gets ~$40 of operating profit per $100 of compute.
IF however RSI gets ANT to $4 rev / compute dollar and helps ANT negotiate the cloud’s gross profit share down to 10%, operating profit per $100 of compute grows 5x to ~$220 👀😵💫
The near-term margin warning and training focus makes sense in this context. They’re paying up for short-term compute while investing in the next models specifically to make this bet.
There may be other ways for them to win and demand obviously still has to show up to absorb all the eventual compute. But the RSI success case is extremely powerful if they can achieve it.
And if this all sounds insane… well, add it to the list ;)
(thanks to the AI Maxi homies for helping and inspiring).
Build a sustainable business economically serving inference with a minority of your compute
Direct the vast majority to research and training because you see accelerating progress, which makes each unit of existing compute even more productive
Achieve RSI, at which point compute loops, progress, and productive capacity of each compute unit accelerate even further
Structurally widens frontier gap to also-rans
Allows higher capacity to pay for a unit of compute than anyone else, because you earn differentially better returns on it
Gives you more compute than anyone else, which accelerates the loop even more
You have the best intelligence and it monetizes it in a power law fashion, sustainably
If you don’t believe this none of it works. But if you do there is only one real path.
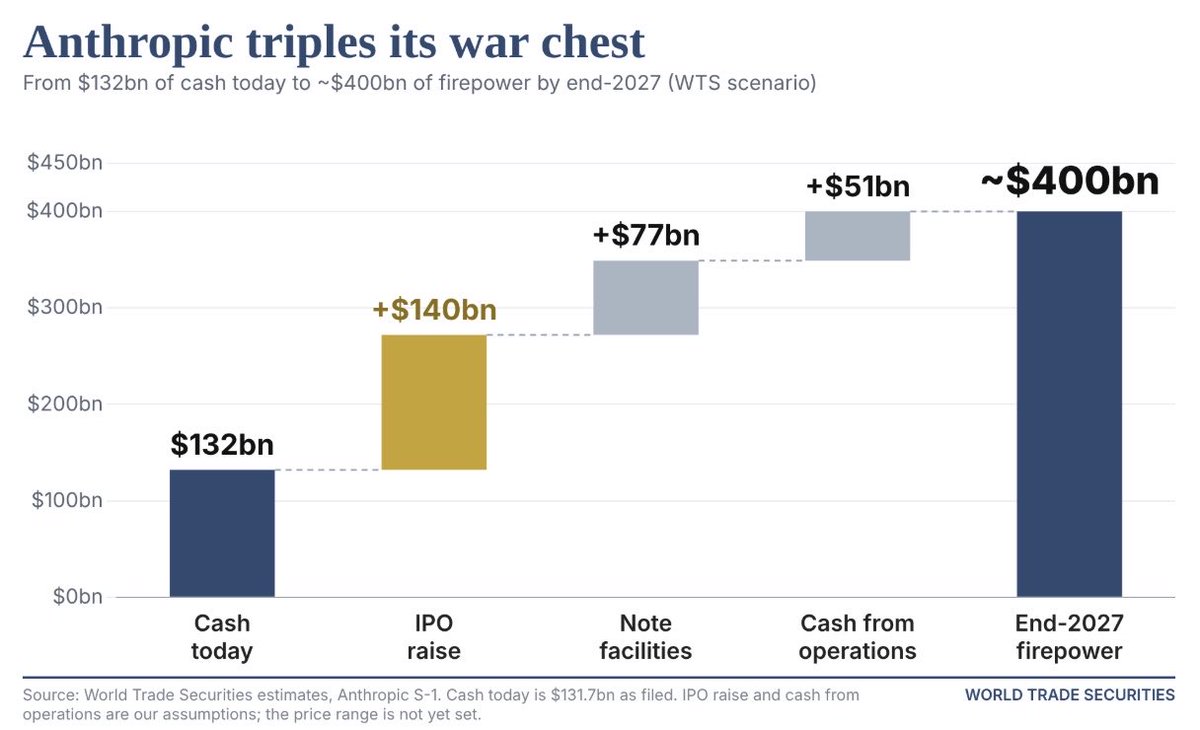
Anthropic already has $132bn of cash.
Add a ~$140bn IPO, $77bn of committed funding from Google, Amazon and Broadcom and cash from a business growing 14x a year and it could be sitting on roughly $400bn by the end of 2027.
That's more firepower than almost any company on earth, aimed at one thing and one thing only: compute.
In a race where the winner is whoever can build the most, Anthropic is about to have the deepest pockets in AI outside of Big Tech itself.
@JayaGup10 Spending on Anthropic is up substantially since the 5.5 family came out (on OpenRouter at least)
Also comparing price declines on output only is a bit odd considering cache makes such a massive difference in effective price. Just sayin.