Concentration Risk Is an Underwriting Decision
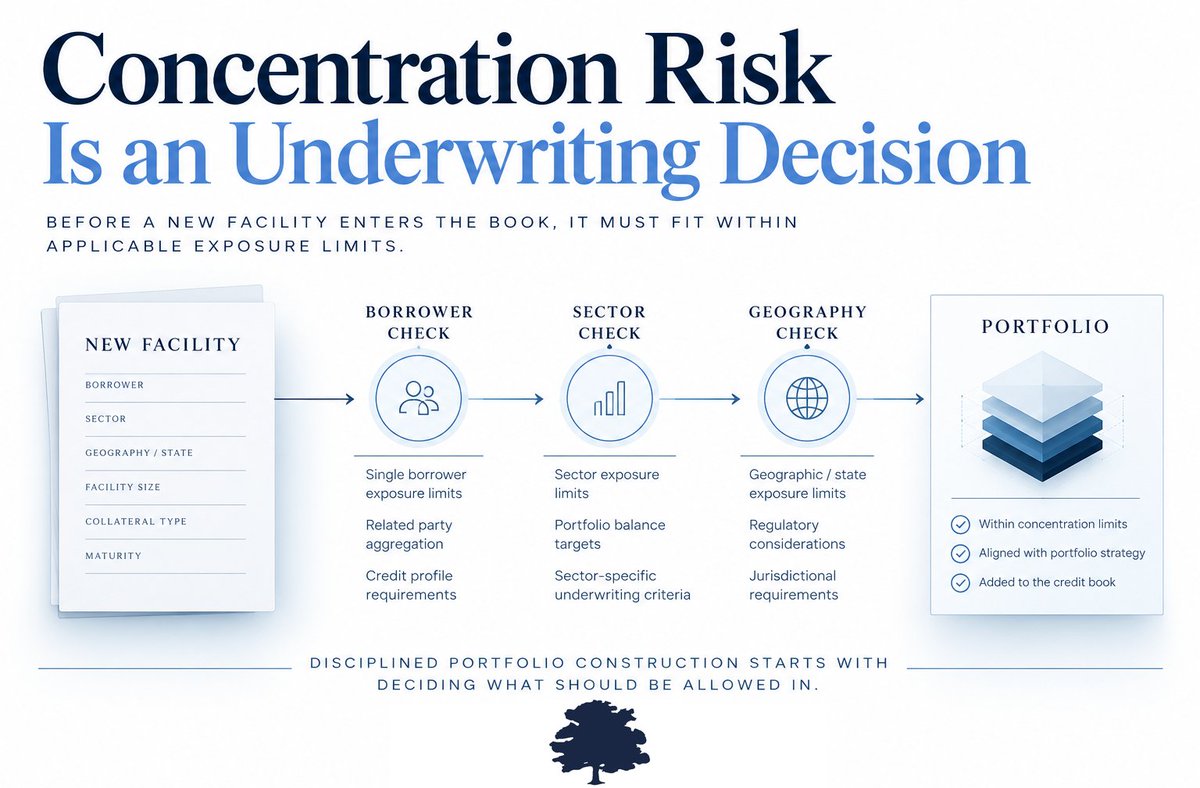
Concentration risk isn’t something you discover after the portfolio is built.
It starts at origination.
Before a new facility enters the book, the question isn’t only whether the individual loan looks attractive. It’s also what that exposure does to the portfolio as a whole.
Borrower concentration.
Sector concentration.
Geographic concentration.
At Forest Road Vault, those limits are part of the credit framework itself.
Because disciplined portfolio construction starts with deciding what should be allowed in.
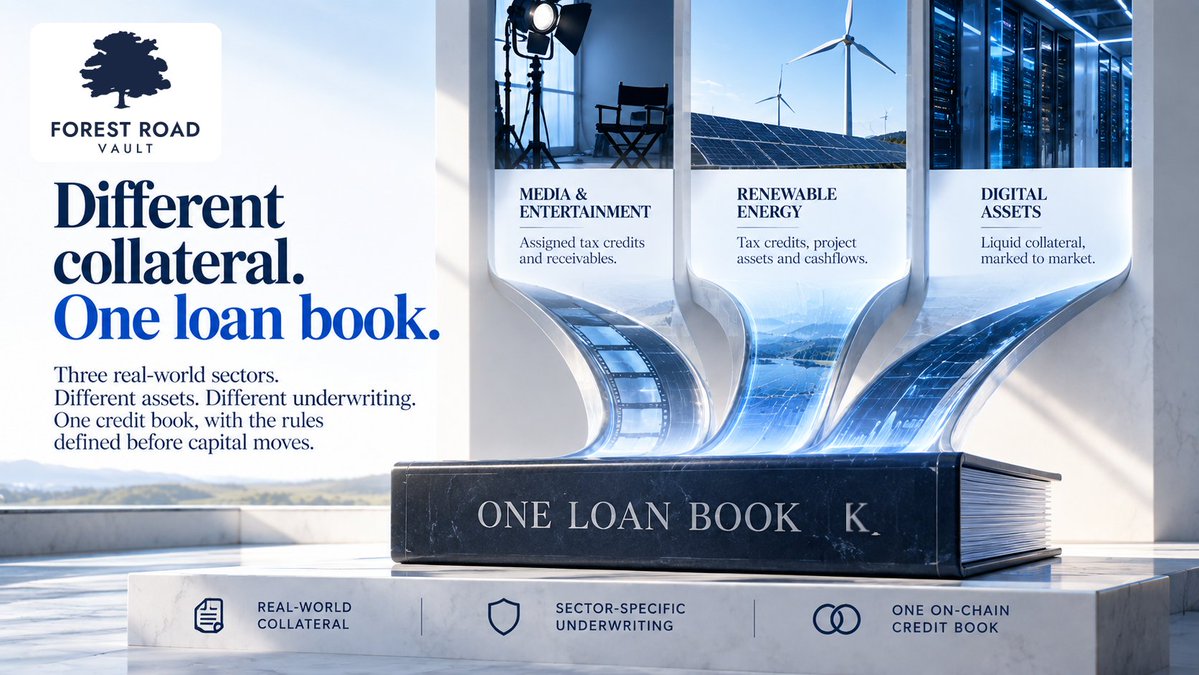
Different collateral. One loan book.
A film tax credit doesn’t behave like a renewable-energy project.
And neither behaves like liquid digital assets.
That’s why Forest Road Vault doesn’t force every loan into the same risk model.
Media & Entertainment: assigned tax credits and receivables.
Renewable Energy: tax credits, project assets and cashflows.
Digital Assets: liquid collateral, marked to market.
Different assets. Different underwriting.
One credit book, with the rules defined before capital moves.
A default and a loss are not the same event.
When a borrower misses obligations, the story isn’t finished. What happens next matters just as much:
Recovery efforts.
Collateral enforcement.
Restructuring.
Final write-offs.
At Forest Road Vault, unresolved defaults and realized losses are treated as different things, because credit performance should show both what is currently impaired and what was ultimately lost.
Default is an event.
Loss is the outcome after recovery.
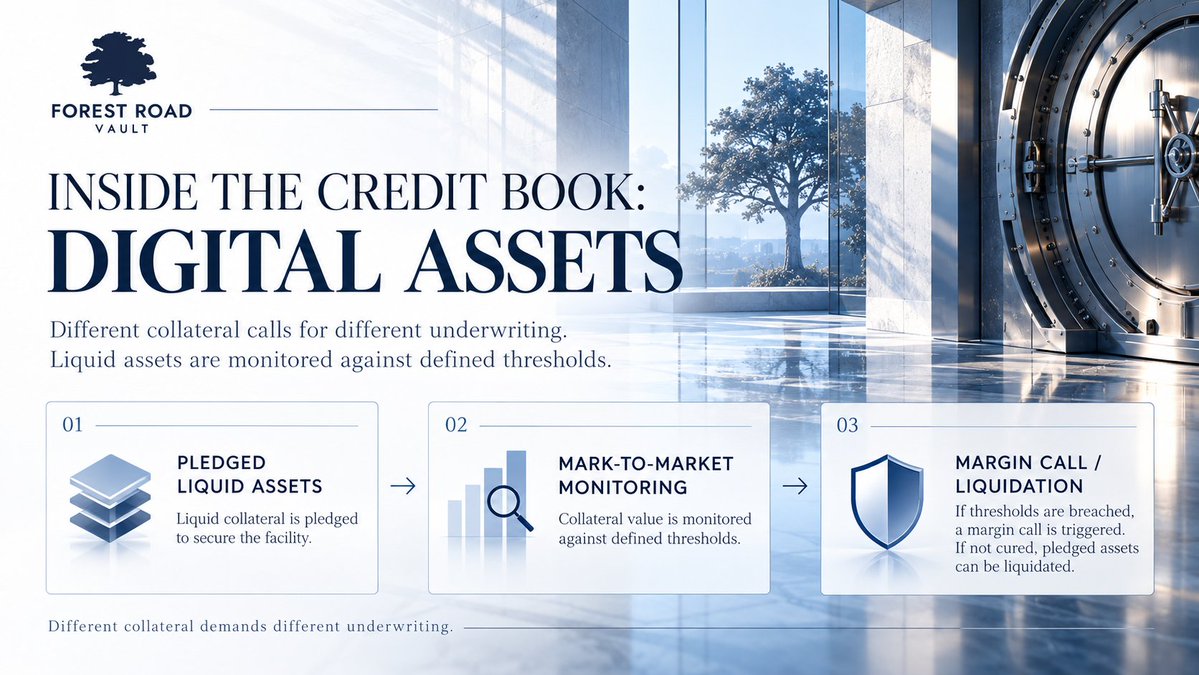
Inside the Credit Book: Digital Assets
Not every loan in a credit book needs the same collateral.
Forest Road Vault’s digital-assets lending is built around a different risk profile: liquid collateral that is marked to market.
The collateral is monitored against defined thresholds.
If its value moves far enough, a margin call is triggered. If that isn’t cured, the pledged assets can be liquidated.
Different collateral demands different underwriting.
The important part is making the rules clear before capital moves.
The road leads somewhere deeper.
Welcome to **Forest Road Vault** — where security meets the journey.
Secure
Grow
Keep moving forward
The vault is only the beginning.
@forestroadvault
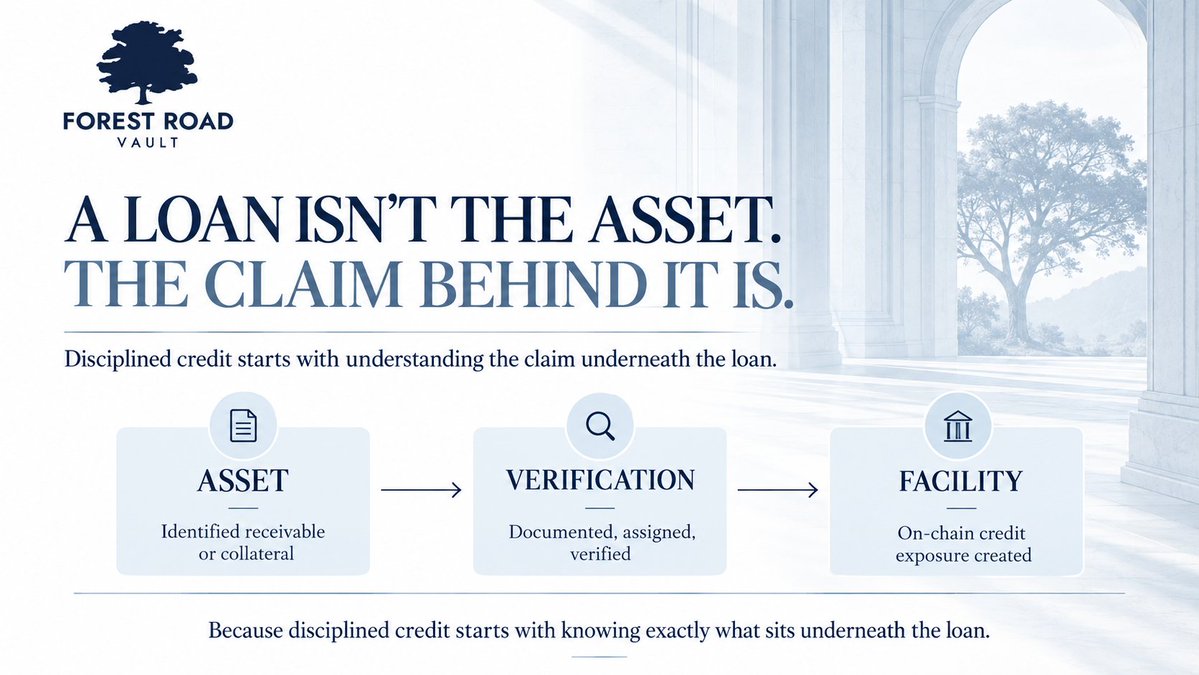
The asset matters.
A loan is only as strong as the claim behind it.
At Forest Road Vault, facilities are tied to identified assets rather than originated into a blind pool. For receivable-backed credit, that means the underlying claim is documented, assigned, and subject to the required verification before the facility is created on-chain.
Asset.
Verification.
Facility.
Because disciplined credit starts with knowing exactly what sits underneath the loan.
What does renewable-energy credit actually finance?
At Forest Road Vault, it means lending to small and mid-market renewable projects against identifiable sources of repayment:
Transferable tax credits.
Project cashflows.
Project-level assets.
Capital can support a project through construction and operation, while the lender holds security against the underlying claims and assets.
The energy may be renewable.
The underwriting still comes down to the same question:
What repays the loan?