@SylentTrade Instructions unclear I mortgaged my house to buy when you said it was getting bought out at $45/share. I’m down 35% my wife is starting to ask questions
I will not be tempted by the sultry wily lusty mistress that is $CORZ crime flow…
43k contracts traded today on the 10/16 $28C with a previous open interest of a whopping 67 contracts. Right off the 200d SMA derisked from earnings. What could go wrong?
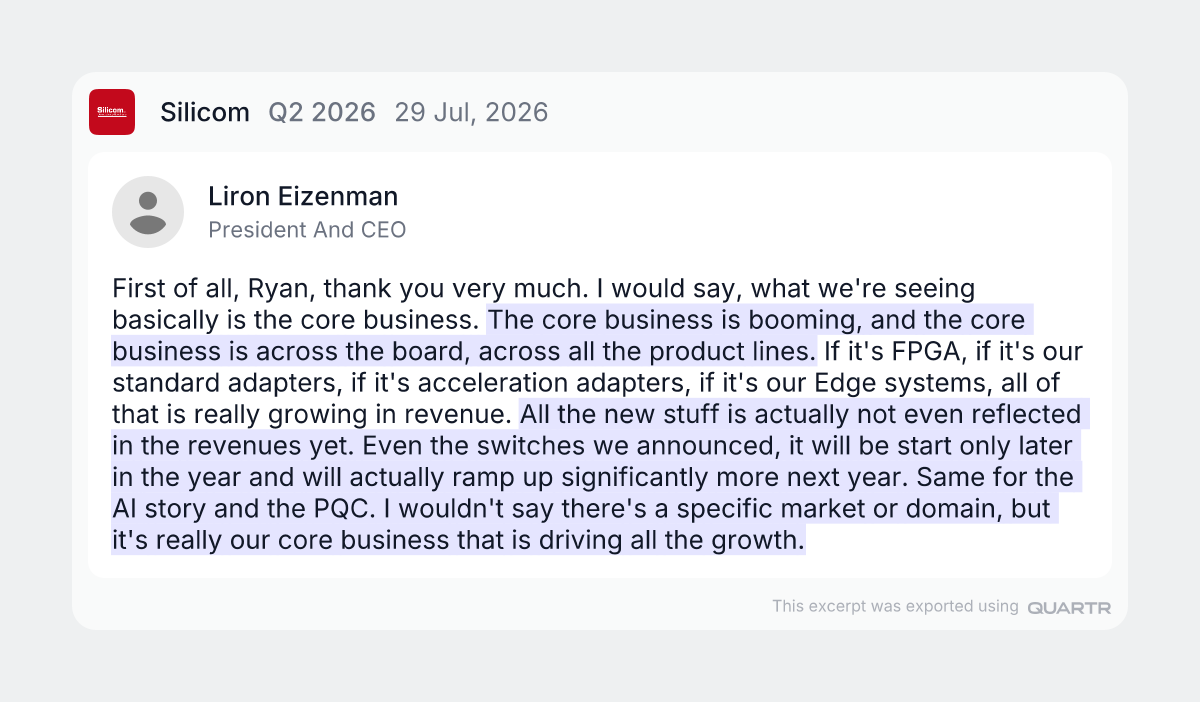
$SILC is trading at ~2.4 FWD P/S with their legacy core in cybersecurity, SASE/SD-WAN edge systems, and FPGA capture and acceleration cards running on all cylinders with 59% revenue growth while the most important growth verticals (AI inference, PQC, white-label switching) have yet to contribute to revenue and will provide meaningful acceleration as we go into H2 FY2026 and more materially in FY2027.
Silicom makes the network cards that go inside servers and the small boxes that connect branch offices to the internet. Silicom's engineers spend 9-12 months embedded inside a customer's R&D team building a custom part. When a customer qualifies it into their product, that's a design win and provides very sticky revenue for $SILC. The growth acceleration is clear enough: Q4 2025: +17%, Q1 2026: +33%, Q2 2026: +59%.
Their balance sheet is phenomenal. $SILC currently sits with zero debt and has ~$45M in cash sitting in its books. Management has clearly indicated that operating leverage is beginning to kick in; the numbers tell the story. In Q2, Opex as a % of revenue dropped from 47.7% to 35.0%, and management now expects non-GAAP profitability in H2 FY2026, which was "significantly earlier than they had originally anticipated"
$SILC is trading at ~2.4 FWD P/S with their legacy core in cybersecurity, SASE/SD-WAN edge systems, and FPGA capture and acceleration cards running on all cylinders with 59% revenue growth while the most important growth verticals (AI inference, PQC, white-label switching) have yet to contribute to revenue and will provide meaningful acceleration as we go into H2 FY2026 and more materially in FY2027.
Silicom makes the network cards that go inside servers and the small boxes that connect branch offices to the internet. Silicom's engineers spend 9-12 months embedded inside a customer's R&D team building a custom part. When a customer qualifies it into their product, that's a design win and provides very sticky revenue for $SILC. The growth acceleration is clear enough: Q4 2025: +17%, Q1 2026: +33%, Q2 2026: +59%.
Their balance sheet is phenomenal. $SILC currently sits with zero debt and has ~$45M in cash sitting in its books. Management has clearly indicated that operating leverage is beginning to kick in; the numbers tell the story. In Q2, Opex as a % of revenue dropped from 47.7% to 35.0%, and management now expects non-GAAP profitability in H2 FY2026, which was "significantly earlier than they had originally anticipated"
BREAKING: Equity options on specific assets will begin trading at 7:15 ET starting this Monday.
Here are the full requirements for eligibility for pre-market options trading:
-the option class has an average daily volume of 150,000 contracts or higher
-the underlying equity to the option has a $50 billion or higher market capitalization, and
-the underlying equity to the option has an average daily traded volume of 10 million shares or higher.
@ZaStocks RDDT is a money printer but if you’re really looking into the business ad revenue is more than 90% of their total revenue. These deals while newsworthy aren’t what really drive the overall profitability of the business. The data deals and premium subs are just the cherry on top
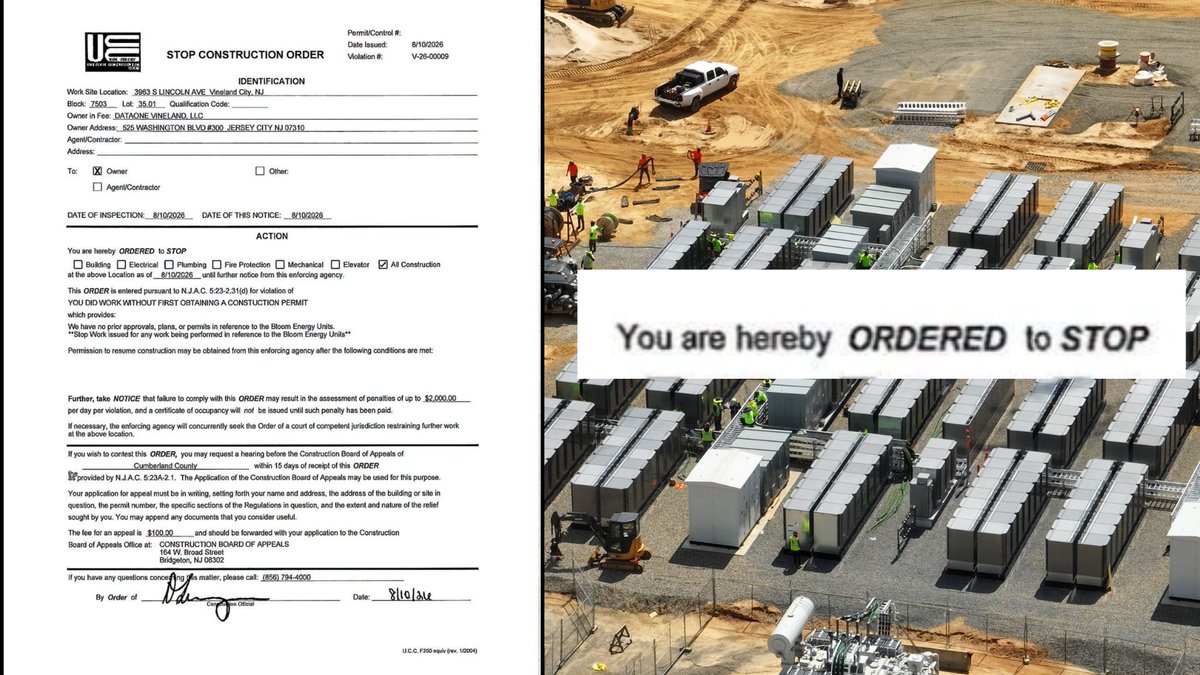
NEW: Vineland City officials issued a STOP CONSTRUCTION ORDER on Aug 10 at the Nebius/DataOne data center in Vineland, NJ, citing installation of Bloom Energy fuel cells with "no prior approvals, plans, or permits."
$NBIS $BE