The Silicon Stack Podcast | Ep. 2 Featuring @PaulBPrager
I sat down with $WULF CEO Paul Prager. The Naval Academy grad who has transformed TeraWulf into one of the fastest-growing pure-play AI/HPC data center platforms in the U.S.
We discuss:
• The 20-year Anthropic deal
• Statewide data center moratoriums
• Power generation (BTM & FTM)
• Overseas expansion plans
Morgan Stanley on $WULF - “Addressing the biggest misconceptions”
PSPs are often confused with neoclouds.
1. PSPs enter into 15-20 year leases, rather than 2-3 years for neoclouds
2. Powered shells built by PSPs are less capital-intensive ($9-14/watt, rather than $30-50/watt for the neoclouds)
3. PSPs take no chip risk, they are simply landlords
We believe it is instructive to compare PSP stocks with real estate stocks. Many real estate investors use discount rates and cap rates that are much lower than those embedded in PSP valuations.
For example, in our base case for WULF (441% upside to our price target), we use a 9% equity discount rate and 7% terminal cap rate on contracts that we expect the company to sign over the next few years.
Morgan Stanley on PSPs: We view this as an opportunity to own stocks with the underlying, high quality value not reflected in current valuations.
$WULF: $65
$CIFR: $51.50
$MARA: $10
$HUT: $275
$GLXY: $43
$APLD: $41
$RIOT: $35.50
BofA sees $NBIS exiting the quarter with 675 MW of connected power and ~525MW of active power, representing a meaningful step-up from the 170MW active at the start of 2026.
The primary focus will be Nebius’ ability to achieve its year-end target of 800 MW to 1 GW of connected power, particularly potential delays at Vineland.
$NVDA CEO Jensen Huang on neocloud concerns: “This is gonna get solved because demand is so good.”
He sees the real issue as multi-month lag from GPU delivery to revenue and the massive capital float required.
Huang wants to shorten the supply chain so operators can stand up data centers faster.
JP. Morgan: The global Server market is
estimated to expand to $506 bn in 2026 from $284 bn in 2025, implying +78% YoY gowth.
Estimated 31% CAGR from 2026-2030
$NVDA $DELL $SMCI $HPE $ANET $CSCO
SPOT COMPUTE TRADING AT 3-4X LONG-TERM PRICING:
Spot and short-term deals are trading at $40-50M/MW: ($SPCX $NBIS $CRWV)
Long-term IG deals sit between ~$10-16M/MW: ($IREN $ORCL $NBIS)
Near term scarcity is extreme
JP. Morgan on $SPCX neocloud business:
“CEO Elon Musk addressed neocloud pricing dynamics with the belief that value of compute per watt will increase in tandem with the increase in intelligence per watt. As more compute capacity comes online and models improve, intelligence per watt will improve, ultimately leading to higher pricing on neocloud contracts.”
Current short-term neocloud contract pricing north of $50/W; pricing to increase alongside intelligence per watt; positive pricing datapoint for neoclouds but capacity build could displace other providers.
Senior Vice President at Cast believes the long-term risk for neoclouds like $CRWV is that hyperscalers are aggressively developing custom silicon (internal accelerators) and self-building at massive scale, which may eventually reduce their dependence on third-party GPU lessors after 2028.
“It's early on in the custom silicon game relative to the valuation that we're giving GPU providers in neoclouds today. I think if you're assessing how the AI inference could erode the market share, it's still the biggest long-term threat, but it shrinks CoreWeave's share of AI compute rather than the GPU market's absolute size, at least for the rest of this decade. The threat is concentrated in exactly the place that CoreWeave relies on, hyperscaler overflow demand and inference, which is both the fastest-growing workload and where older GPUs go for their second life. Frontier training for labs that don't own chips is probably the most protected part of that market.”
The expert from this post is a Vice President focused on AI ecosystem and cloud alliances at an AI infrastructure company, he has spent the past decade working in cloud and AI infrastructure, including enterprise sales roles at Amazon and Microsoft.
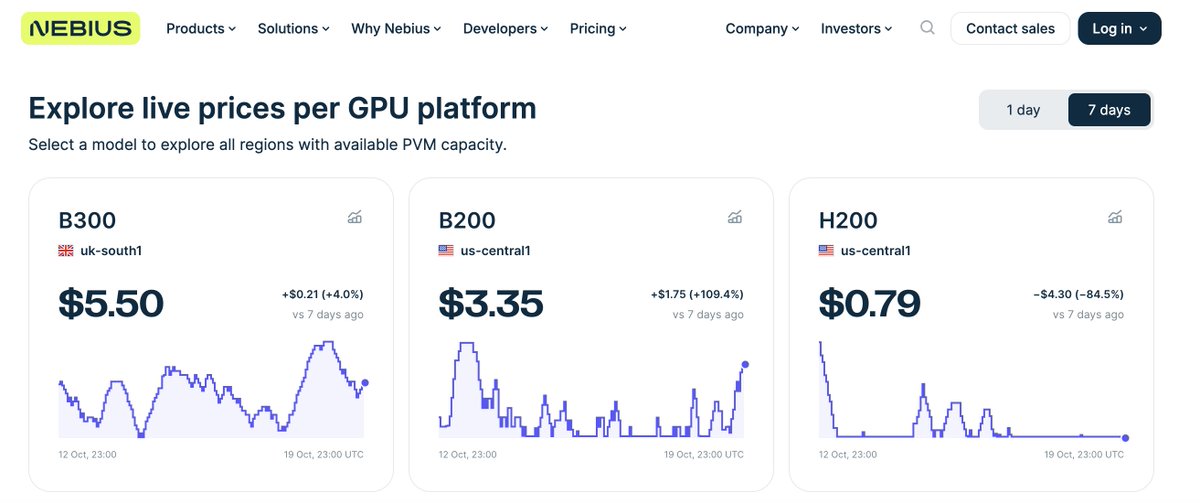
@DoctorMinted Yes live is different than on-demand PAYG. Pricing wasn’t meant to be comparable to the original post but GPU pricing as a whole has its parallels
AWS currently prices B200 capacity blocks at roughly $12.36 per GPU-hour and B300s at $14.04, implying a neocloud discount of roughly 30%-45% on comparable current-generation hardware
$SPCX $CRWV $NBIS $IREN
Source: William Blair (9/30/2026)