Australia’s energy transition is already underway and investors have an important role to play.
We were pleased to host @honmattkean for a wide-ranging conversation on climate policy, clean energy and responsible investing.
Watch here:
https://t.co/iIn1lOiWNg
#ResponsibleInvesting #EnergyTransition #CleanEnergy
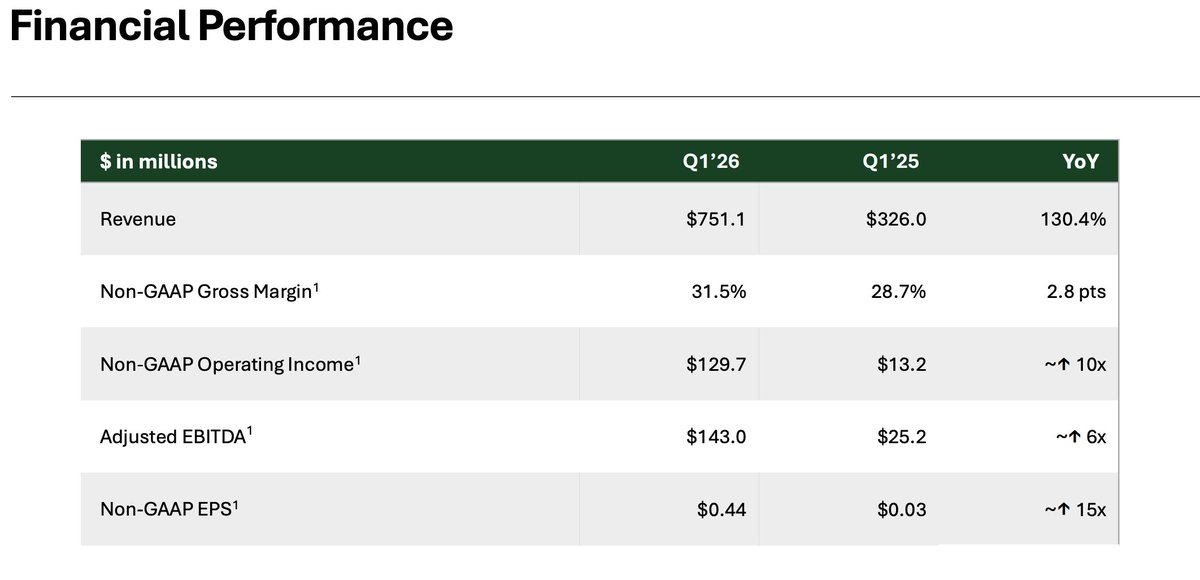
@Bloom_Energy Q1 FY26 is a statement quarter for clean energy:
• Revenue +130% YoY to $751m
• Operating income ~10x ($13m → $130m)
• EPS ~15x ($0.03 → $0.44)
• FY26 guide raised to $3.4 to 3.8b
Fuel cells are now core AI data centre infrastructure.
Oracle 2.8GW. AEP 1GW. Brookfield $5b.
Clean energy is not a trade-off.
@amazon + @AnthropicAI just doubled down.
-- Another $5B into Anthropic (up to $25B more)
-- Total commitment: $13B invested, stake worth ~$60B
-- Anthropic to spend $100B+ on AWS over 10 years
Amazon isn't an e-commerce company anymore. It's the AI infrastructure layer.
The energy transition isn't just a climate story. It's an energy security story.
In our latest video, @jaimirch unpacks where the real long-term opportunities are in climate solutions — and how we separate the durable business models from the noise.
What we cover:
→ Why energy security is the new transition thesis
→ How AI data centres + transport electrification are supercharging clean energy demand
→ The companies actually enabling decarbonisation across power, transport & data
https://t.co/j1mMDxNqYw
@HUB24_Ltd Q3 FY26: $4.0B net inflows (+9% organic), total FUA $151.7B (+22% YoY), 5,549 advisers (+11%). First for net inflows nine quarters straight. Market share now 9.7%. The platform migration in Australian wealth continues.
TSMC Q1 2026: $35.9B revenue (+40.6% YoY), 66.2% gross margin (beat guidance by 120bps), net income +58.3%. Fourth straight record quarter. Q2 guided $39-40.2B. AI demand "extremely robust." The most important company in tech keeps delivering.
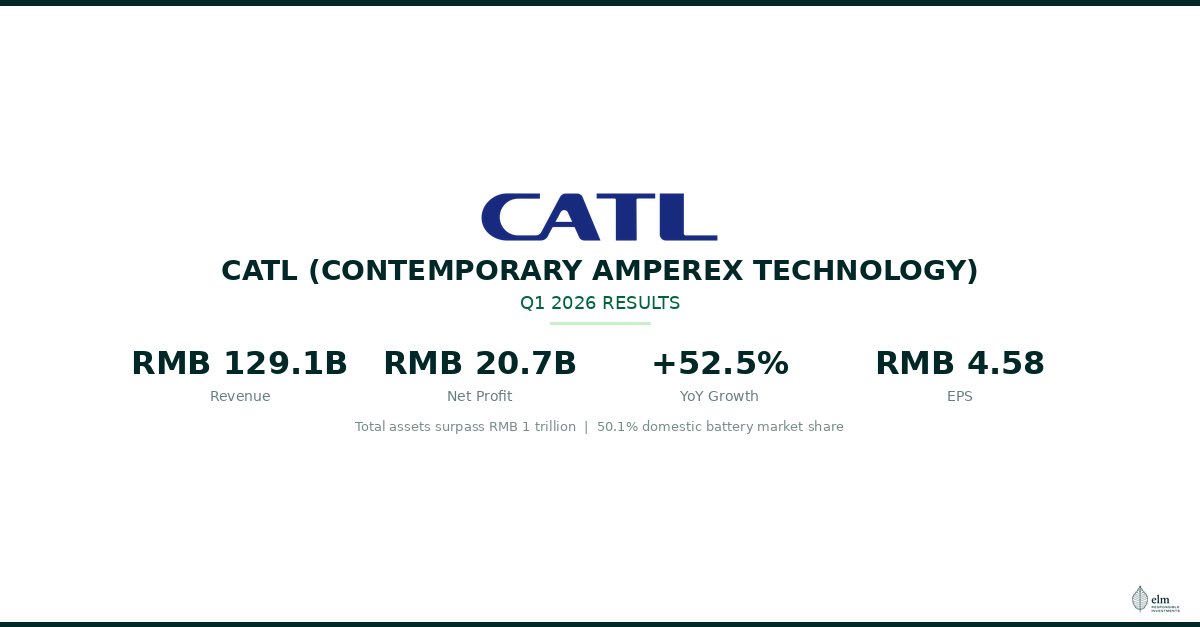
CATL Q1 2026: Record revenue of RMB 129.1B (+52.5% YoY), net profit RMB 20.7B (+48.5%). Total assets top RMB 1 trillion for the first time. 50.1% domestic battery market share. The electrification wave is accelerating, not slowing.
ASML Q1 2026: EUR 8.77B revenue, 53% gross margin, EUR 7.15 EPS -- all beats. Full-year guidance raised to EUR 36-40B. CEO Fouquet: "Demand for chips is outpacing supply." The AI infrastructure cycle has legs.
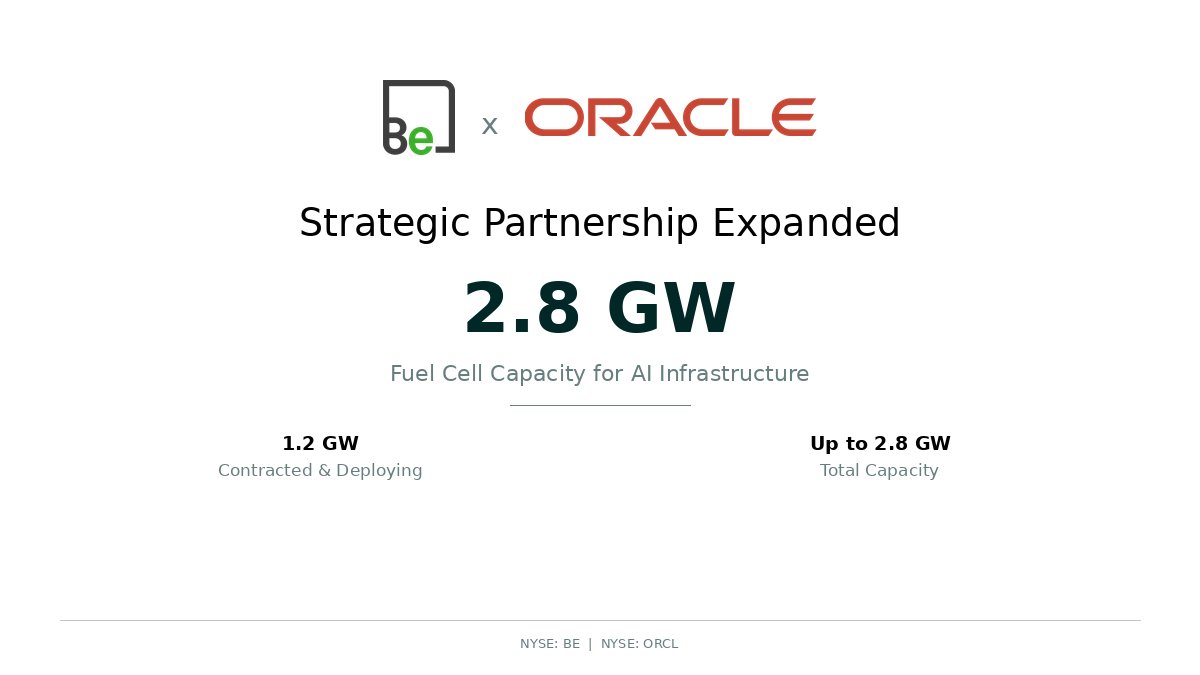
Bloom Energy x Oracle partnership expanded to 2.8 GW of fuel cell capacity for AI infrastructure.
What stands out from a sustainability lens:
→ Bloom's solid oxide fuel cells generate power without combustion
→ ~50% less CO2 vs the U.S. grid on natural gas
→ 99.9%+ reduction in NOx and SOx
→ Carbon-neutral on biogas, zero-carbon on hydrogen
→ 6.3M tonnes of CO2e avoided since 2011
1.2 GW contracted and deploying now. BE +15% after hours to ~$204.
AI needs power. Bloom is delivering it cleaner.
$BE $ORCL
#BloomEnergy #Oracle #AI #CleanEnergy #Sustainability
Everyone braced for an inflation disaster. The PPI just told a different story.
CPI (Friday): 3.3% YoY, highest since May '24. Gasoline +21.2% in one month.
PPI (today): +0.5% MoM vs ~1.2% expected. 4.0% YoY vs 4.6% forecast. A big miss to the downside.
The Iran energy shock is real. But it is NOT transmitting into broader wholesale prices:
Core CPI: +0.2% MoM, 2.6% YoY
Core PPI: +0.2% MoM
PPI services: flat
Food: unchanged in CPI, down in PPI
Businesses are absorbing cost pressure, not passing it through. Trade margins fell 0.3%.
The pipeline is mixed. Diesel +42% upstream, but natural gas -51.7%. Not uniformly building.
Fed implications: can't cut at 3.3% headline. Don't need to hike with core behaving and PPI cooling. Higher for longer holds, but emergency tightening just got less likely.
Headline noise. Core signal. Know the difference.
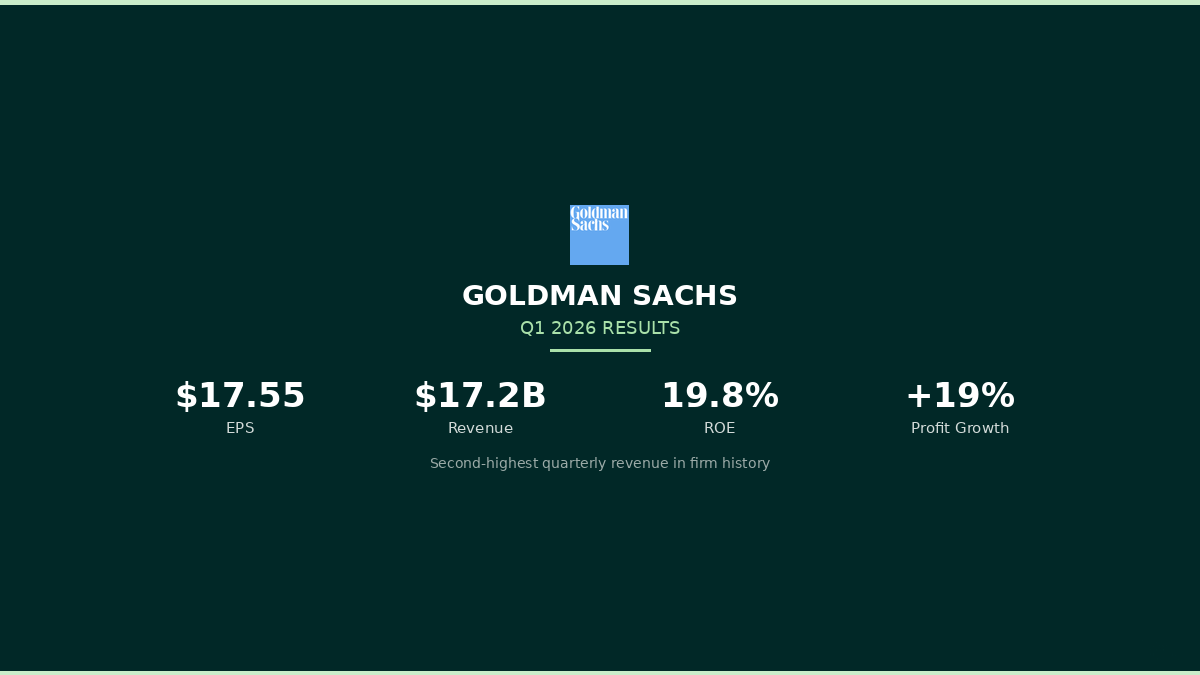
Goldman Sachs Q1 2026 — record results, but the macro warning signs are real.
The numbers:
• Revenue: $17.2B (+14% YoY)
• Profit: $5.63B (+19%)
• EPS: $17.55 (beat by 7%)
• Record equities: $5.3B
• Advisory up 89%
The warning:
• US recession odds raised to 30%
• GDP growth slowing to 1.25–1.75%
• Unemployment heading to 4.6%
• Energy shock + fading fiscal support
Solomon: "The geopolitical landscape remains very complex."
Record Wall Street profits alongside rising recession risk. That’s the paradox of 2026.
#GoldmanSachs #Q12026 #USEconomy #WallStreet #MacroOutlook
We are pricing most AI startups wrong.
SaaS era pricing model was based on the typical growth profile of a SaaS company:
some R&D -> first sales -> early scaling -> more R&D investment -> enterprise scaling
Where margins would eventually go up to 80% (with most of the cost being sales and marketing).
AI startups are VERY different, since even the best ones pay the "Inference Tax" where 40-60 cents on a dollar would go to infra, foundational models, cloud, silicon, and power. Everyone's margins within the AI stack are akin to industrial manufacturing - thin and scale dependent (with the notable exception of Nvidia which has a 75% margin and readily invests the oversized proceeds into the application layer or lends to hyperscalers to spend on more of their equipment)
The value accumulates in owning users' behavior, being their first or second screen, and everything else upstream is increasingly commoditizing. We are in a market where 16 companies have a frontier model. More companies can serve inference in a cloud. More companies can find lots of land with water and electricity for datacenters. Jensen put it nicely - think of a datacenter as a modern day's factory: electron go in, intelligence goes out.
So your "AI agent for banking AML and compliance" is not a SaaS. It's a silverware customization service trying to build a brand. But the spoons are mass produced in a factory from sheet metal, coming from mills, which get ore from mines. Metal and electricity come in - consumer emotions (and some utility) come out.
However, this doesn't mean that paying a SaaS multiple for an application layer/agentic AI startup today is wrong. But let's be honest - we're not paying a premium for the huge terminal value (as with SaaS), but rather for a much bigger revenue growth potential.
Never before in history we saw a 5 people team in SF routinely challenging $100B incumbents disrupting their business models and offering the market expansion to $500B. Never before we've seen companies like Perplexity adding 50% to $300M ARR in a month or Higgsfield growing to $300M from 0 in a year. They don't build their spoon factories or steel mills. They deliver customer value expanding their markets tenfold.
So for now SaaS multiples would do. The "bubble" will not burst (although some pockets of overpricing might correct). But we should change the way we approach valuations for the future.
(read about this and more in our annual State of AI report) here:
https://t.co/WPdTM9HUGv
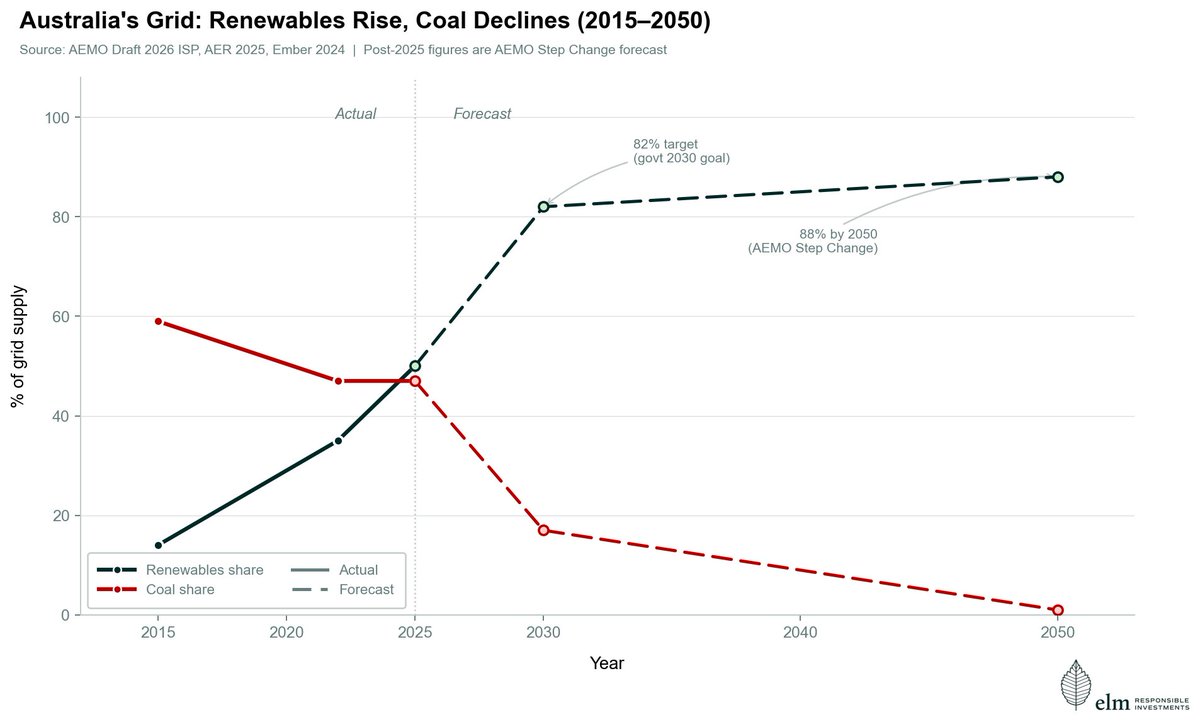
Renewables just crossed 50% of Australia's grid for the first time. By 2050, AEMO's own plan has that number at 88% and coal at zero.
That's not a climate story. That's an energy security story.
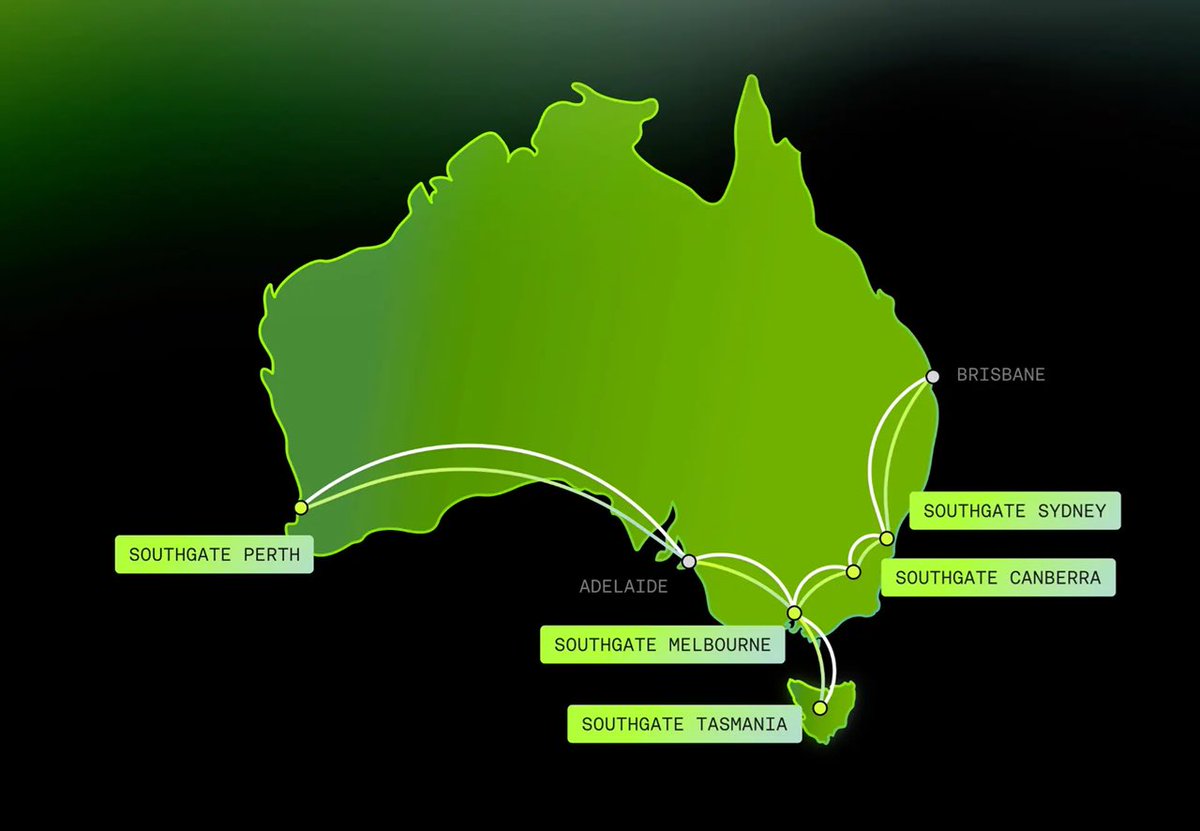
🇦🇺 AUSTRALIA: AI Cloud Firmus has secured $505 MILLION in equity investment
The investment will support the firms deployment of AI infrastructure based on Nvidia Vera Rubin
It will also support the Southgate data center project with Nvidia and CDC Data Centers
Aussie compute 📈