@sectorstories That said, one cannot rule out an even more increased preference for local brands going forward. Which would represent a structural change to the luxury market vs. past decades.
1/4 $RMS: we are not there yet. Fair value = €1,000/share.
Q3 sales growth of +4% cFX. On this trajectory investors should expect near-term operating deleverage (slightly buffered by stronger Leather performance). After a few years of over-earning, margins will mean-revert...
Un pays ne se défait pas en un jour. Il se défait par une lente accumulation de renoncements, chacun jugé trop coûteux à affronter sur le moment.
Une décennie perdue est un drame. Deux seraient une faute impardonnable.
Ma tribune dans @LesEchos ⤵️
« S’il advient que la médiocrité marque, pourtant, ses faits et gestes, j’en éprouve la sensation d’une absurde anomalie, imputable aux fautes des Français, non au génie de la patrie. »
“Vieille France, accablée d’Histoire, meurtrie de guerres et de révolutions, allant et venant sans relâche de la grandeur au déclin, mais redressée, de siècle en siècle, par le génie du renouveau ! »
Mémoires de Guerre, Le Salut, De Gaulle
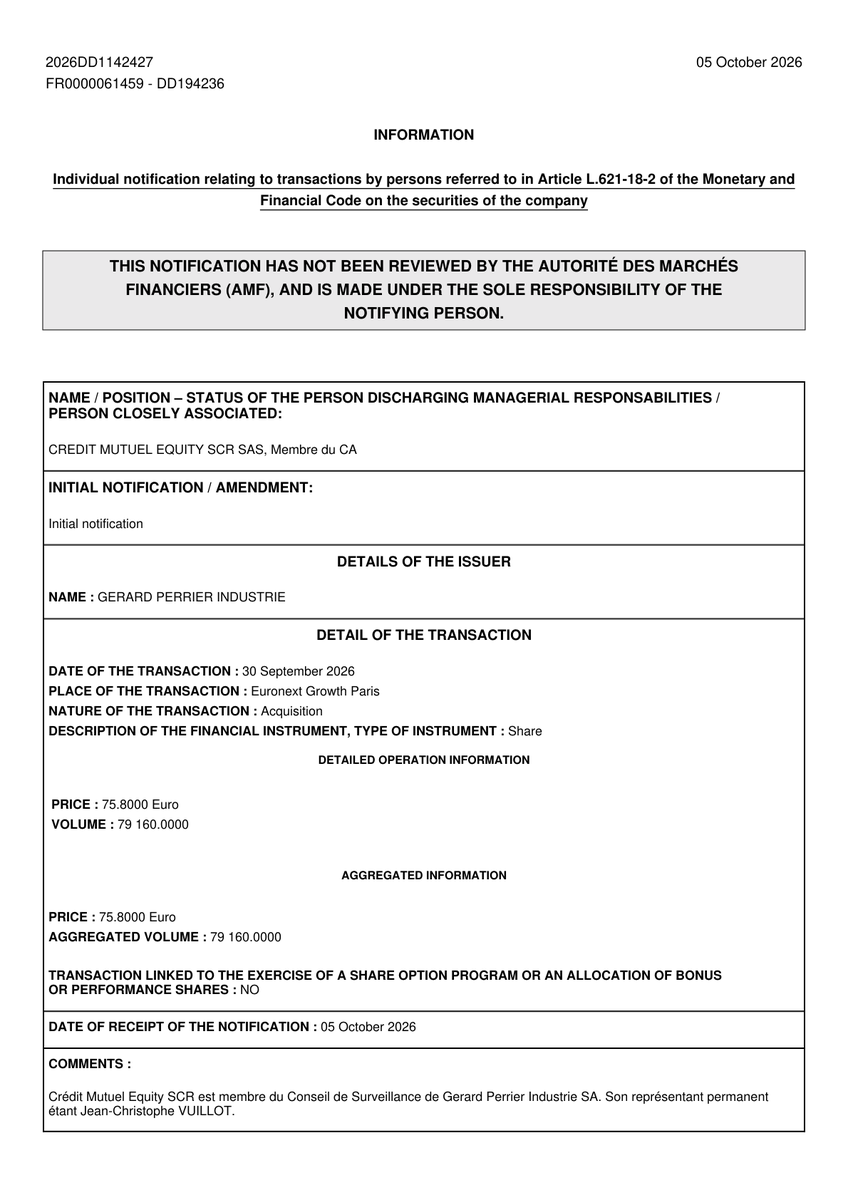
When such a patient PE fund, already a shareholder at family holdco level, also accumulates shares in the opco, one can assume they might be reasonably comfortable with the group’s outlook. $ALPER.PA Gerard Perrier Industrie
🔔 GERARD PERRIER INDUSTRIE
📈 Achat de 79 160 actions à 75.8 € (Total de 6 000 328 €)
👤 Jean-Christophe Vuillot
📋 Membre du CA
🏢 CREDIT MUTUEL EQUITY SCR SAS
📅 Le 06 octobre
@memyselfandi006 François Perrier, through its personal holdco, had also purchased some shares in December at roughly the same price. He also joined Precia’s board recently.
When Le Professeur speaks, the world listens. Different dressing room, same authority, same wisdom, same class. Arsène Wenger, forever an Arsenal legend ❤️
Don’t forget the French government has historically been one of the best at financial repression. It can obviously no longer some of the tools available in the 70s for instance. But its civil servants can be hugely creative.
That’s exactly what happens when Japanese holders liquidate their French OAT positions to buy JGBs. The problem with French debt is that it’s now almost 60%-owned by foreign residents. Domestic banks and insurers might be strongly « incentivized » to « replace »them shortly...
Listen up, freaks: we’ve got AI, labour law, being rude about the French, and the Nazis ALL IN ONE piece. What else could you ask for?
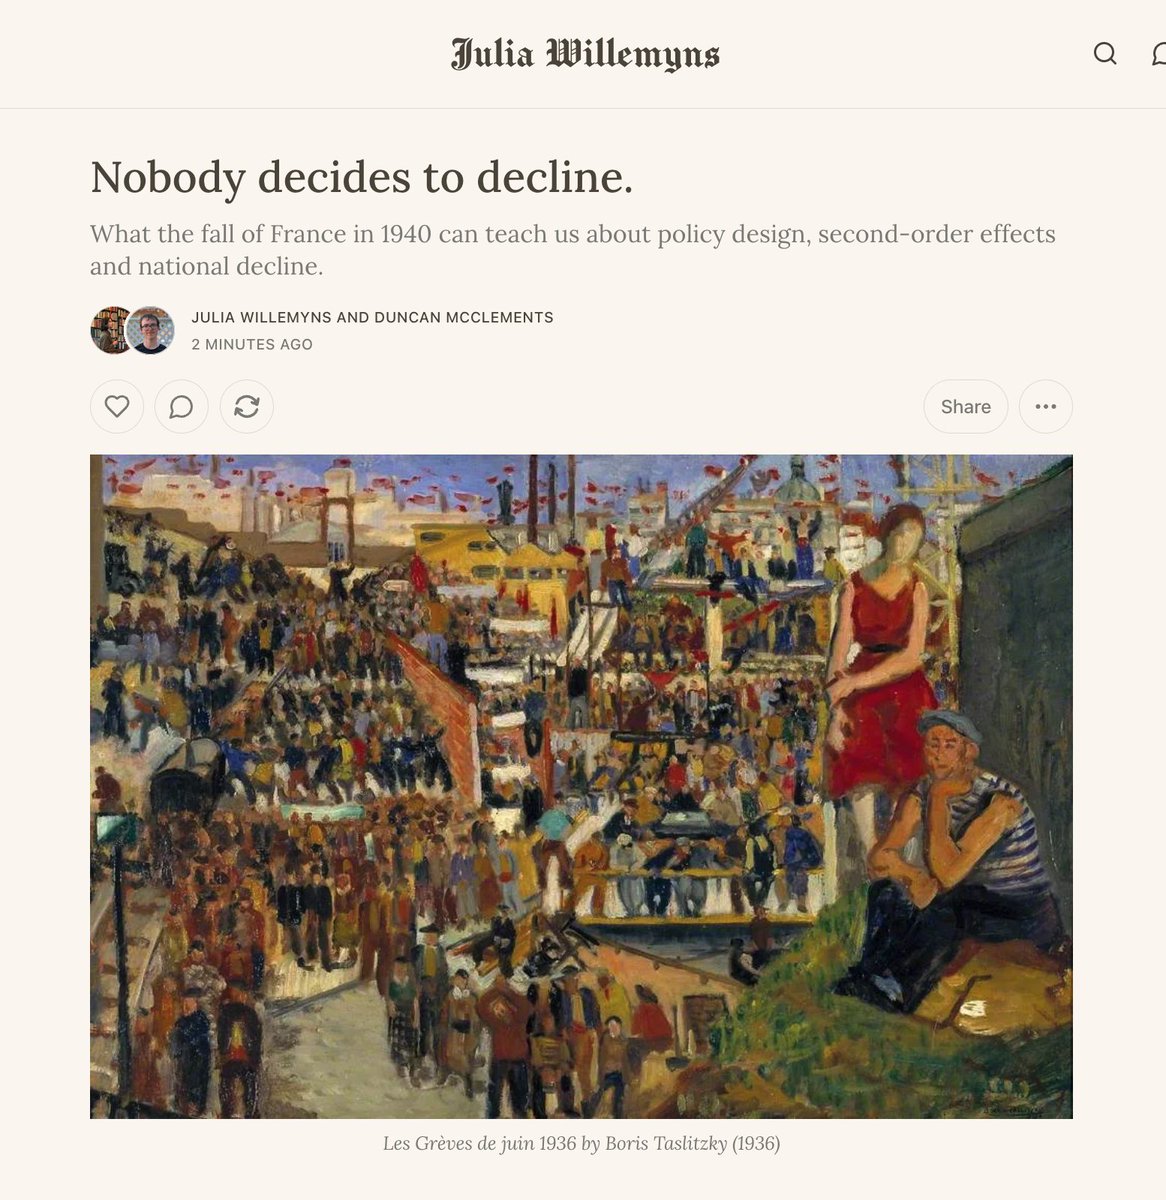
New essay with @DuncanMcClement on what the fall of France in 1940 can teach us about policy design, second-order effects and national decline.
https://t.co/flAm2SS4K3
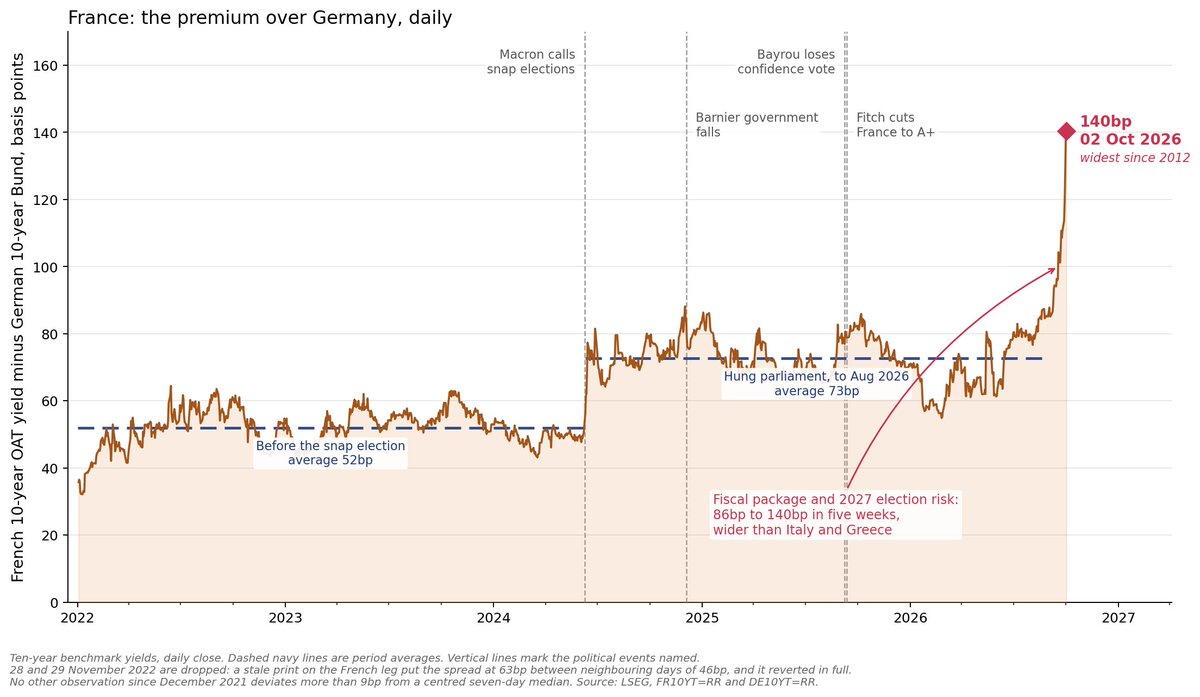
Why France, why now? Over the last couple of years, the French political class has been signaling to the bond market that its pensioners/boomers are the de facto senior claimants on the French Treasury's revenue. And that's not what bond investors wanted to hear, especially now that they're being asked to absorb a much larger share of issuance than a couple of years ago.
https://t.co/6xMTlWWxt9
« S’il advient que la médiocrité marque, pourtant, ses faits et gestes, j’en éprouve la sensation d’une absurde anomalie, imputable aux fautes des Français, non au génie de la patrie. »