Too much capital is lost in familiar stocks
(nostalgia investing)
🆓 Free weekly: the value traps.
🤝 Members: the ignored longs + frequent updates as long as I cover them.
No crash letter / fear pitch.
Written opinion. You decide.
Stocks only.
👉 https://t.co/oGMchsYzpd
@sp3cul8r I still don’t understand why so many people think IPOs would be free gifts to the public, when they clearly aren’t.
if everything was so great, the company would not need to go public to begin with.
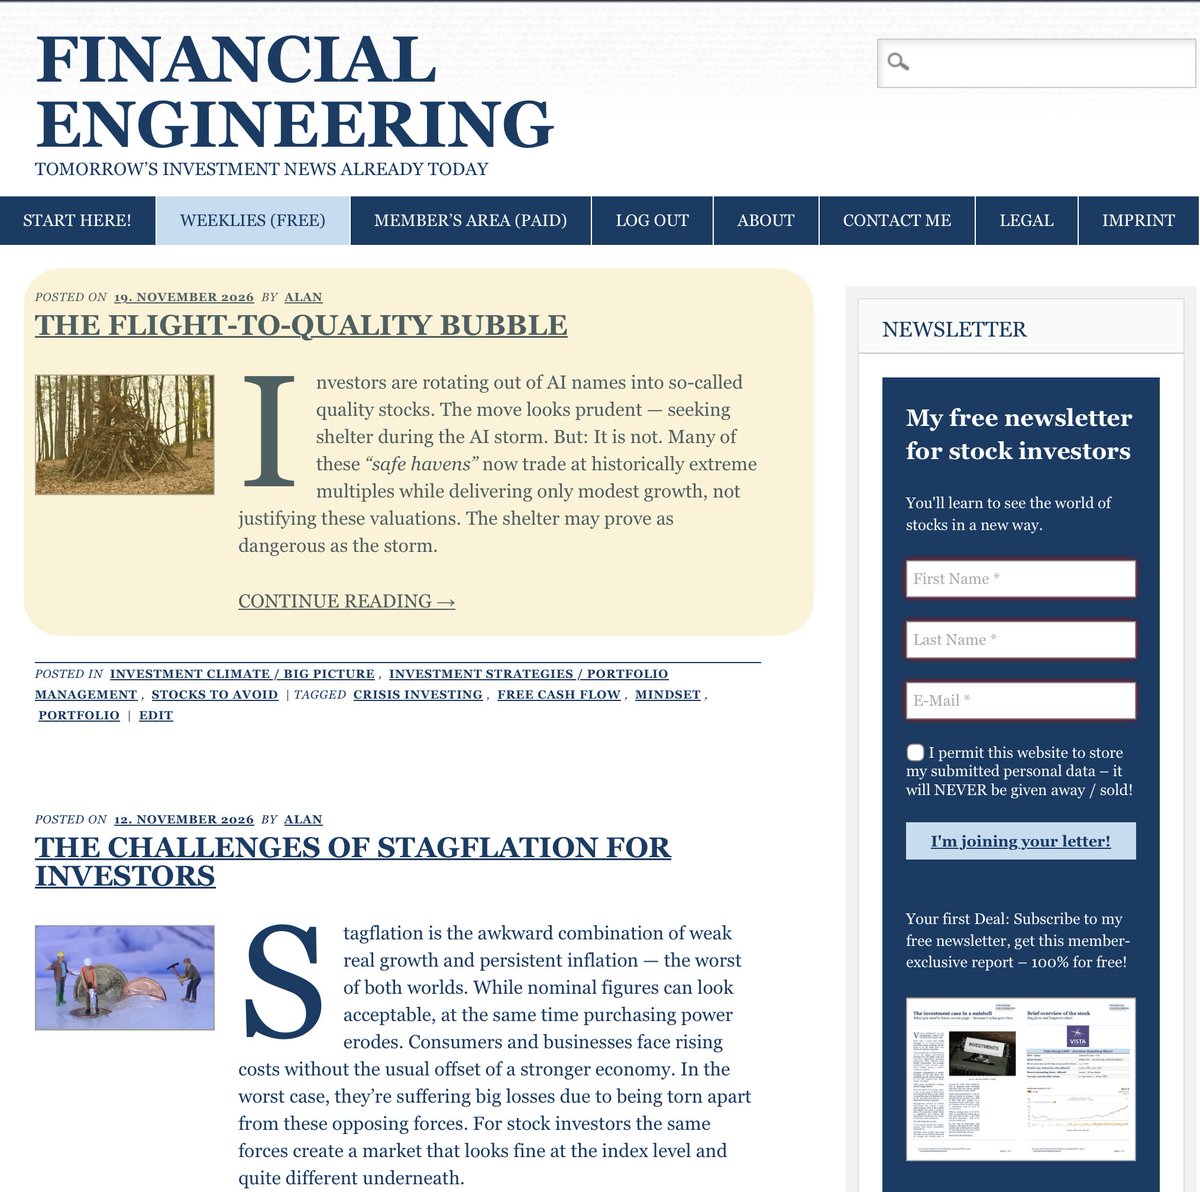
The flight to quality looks prudent. It is not.
The Consumer Staples ETF $XLP has made new all-time highs. It is dominated by
Walmart $WMT at 46 times earnings
and Costco $COST at 53 times.
The shelter may prove as dangerous as the storm.
https://t.co/ob5F8pPkbR
this is a massive correction from Paladin Energy $PDN, catching the majority of investors on the wrong foot.
a material reduction in expected production output and – even more important – the risk of dramatically higher costs plus lower realized prices.
with much uncertainty + the risk of having to buy from the spot market, this could be a disaster, at least in the short-term.
that's how a bull market in a commodity can bypass a miner…
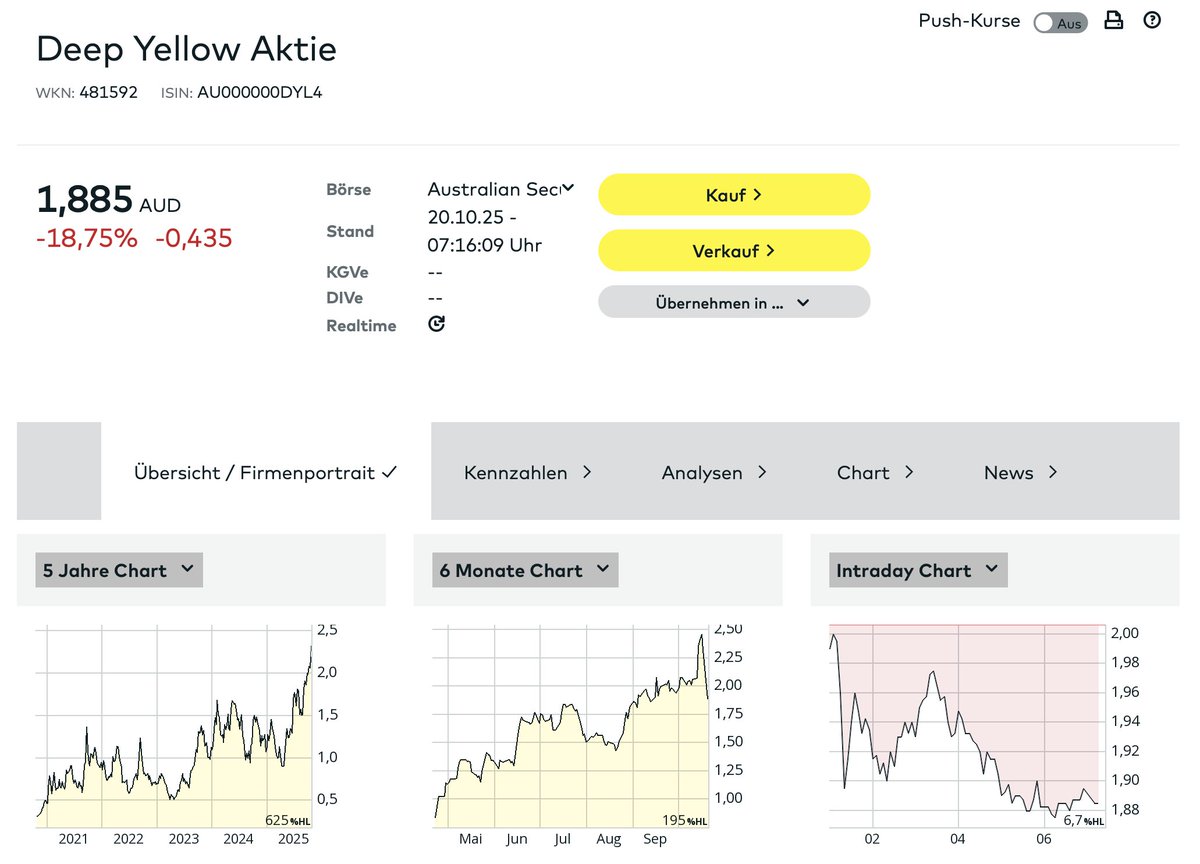
@FreiburgCoffeeC I wrote about this in October 2025, when the CEO of Deep Yellow $DYL.AX left overnight: I simply cannot warm up to uranium miners.
1.89 AUD then, 0.68 AUD now.
https://t.co/qB4wIfpQOs
WOW!
Deep Yellow $DYL.AX turns deep red after a sudden + strange CEO-step down w/ immediate effect.
almost –20% overnight.
I simply cannot warm up w/ uranium miners.
had a nice time from 2021–2024 with Yellow Cake $YCA, but miners… 🤔
Nvidia had another small piece of news yesterday that got completely overshadowed by earnings.
It sold 25% of its Intel shares, cashing out roughly $5.5 billion.
The surprising part is that $INTC only fell 0.5% today. $5.5 billion worth of stock hit the market and nobody even blinked.
The math gets even more interesting. In 2025, Nvidia invested $5 billion in Intel. Now it has sold just a quarter of that stake and already recouped $5.5 billion. The remaining three-quarters are still in its hands.
In other words, the investment has already paid for itself. Everything left is pure profit.
Looking at it together with the earnings, Nvidia returned $28.1 billion to shareholders this quarter (buybacks plus dividends) and still has $227.3 billion in unused buyback authorization. The cash from selling Intel stock simply adds a bit more ammunition.
My take is that Nvidia is not just selling shovels. The shovel factory stock it casually bought on the side has also turned into a money printing machine.
Sometimes the most profitable investment is the one you make on the side.
@SamIAmtheREMan@Mr_Neutral_Man Price helps.
Debt decides.
When Gladstone Commercial $GOOD cut its dividend in January 2023, I wrote that more such "surprises" would come.
16.69 USD then, 9.83 USD now.
https://t.co/4mjEED5xtP
With $CUZ, my members and I did well during the office panic in 2023/2024.
@junginrente Es wird mehr solcher "Überraschungen" geben.
Auch $GOOD hat gekürzt.
Für mich ist das nicht überraschend.
Habe gestern Zum Thema #Zombie-Unternehmen geschrieben:
https://t.co/D2vaecjr1J
Auch einige "Lieblinge" werden da nicht drumherumkommen.
Marcus Braun CEO of Wirecard bought tens of millions of shares of Wirecard to show confidence to the market
Meanwhile he took a loan of 150M eur with Deutsche with his shares as collateral - he enjoyed a nice life…during the downfall Deutsche had to liquidate the shares to recover what they could…eventually everything went to zero.
Not the same case here of course but just as a reminder the cofounders of Coreweave sold $3.3B worth of shares since the IPO in 2025. $30million bonds purchase is peanuts.
@FitchRatings The "elevated leverage" part is the one to read twice.
A potential recession could do the rest.
Better buildings don't fix a weak balance sheet.
https://t.co/GudUjXJzUY
Another dividend cut, though not a prominent one.
But nonetheless, we can take a lesson.
It's $OPI or Office Properties Income Trust, an office REIT that cut its dividend by 96% from 0.25 USD to a symbolic 0.01 USD.
The reason? Let the company explain it:
"Given the deterioration in market conditions since we last addressed our dividend rate in the first half of 2023, we believe it is prudent to further reduce the dividend to increase our liquidity and financial flexibility when addressing future leasing costs, capital expenditures and debt maturities. This new dividend rate will immediately increase OPI’s liquidity by approximately […]"
---
The stock is down by 33% today.
You see it, bad market conditions, weak balance sheet, problems with liquidity.
As I sad numerous times: do your due diligence.
But there are also winners. Even though office is a tough market with really bad sentiment – there indeed are winners to be found.
Here's my free article with valuable background information: https://t.co/R8p0cmE5vj
A producer carries costs, capex, dilution and delays.
The commodity carries none of that.
Buy the producer only when the price leaves room for all four.
Uranium miners are falling hard this week, while the uranium story still sounds great.
Owning the commodity story is not the same as owning the producer.
Two of my notes, uranium — and fertilizers 👇
Mosaic $MOS, November 2024:
"for me the market is oversupplied. any growth comes from higher output", fairly valued at best.
the oversupplied story changed.
what did not change were the ongoing struggles and challenges for Mosaic.
28.34 USD then, 19.93 USD now.
https://t.co/lxBD4OH0fe
@tclaugus2 for me the market is oversupplied. any growth comes from higher output which is a dangerous situation to be in.
absent of a political event, I am highly skeptical on $NTR and $MOS for the moment.
they're fairly valued at best. better to have them substantially below book value
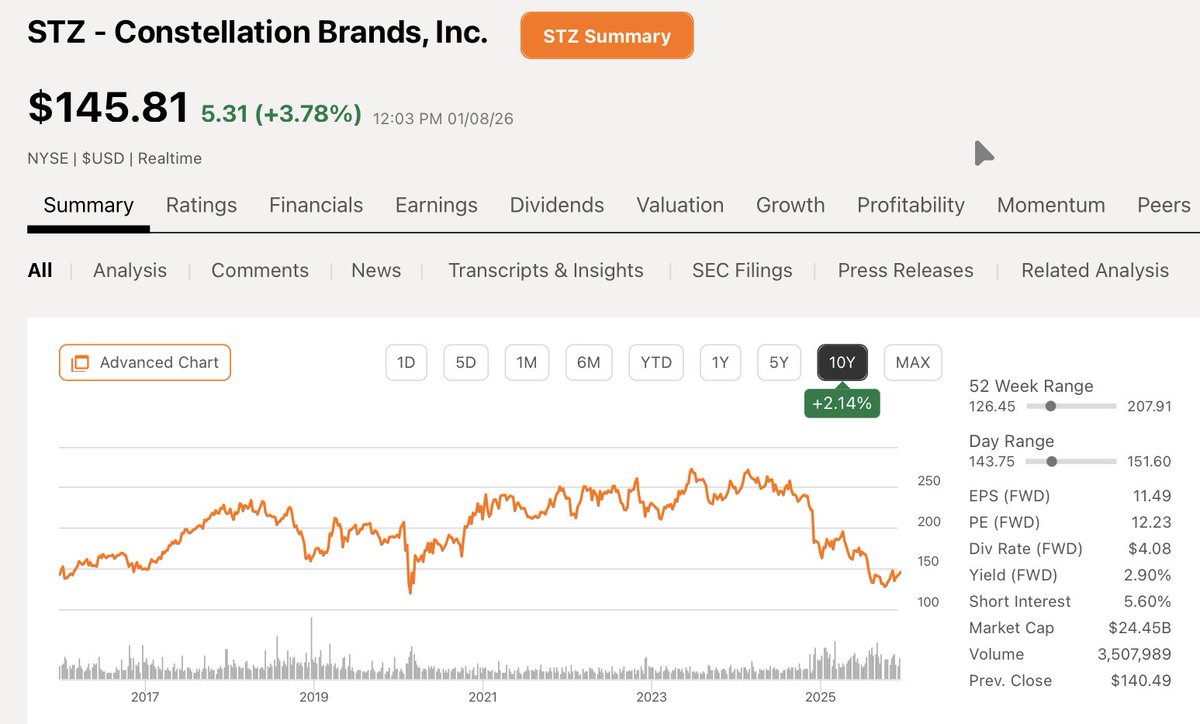
Constellation Brands $STZ:
the Sands family sold 65 million USD of shares at 145 USD on 16 Nov.
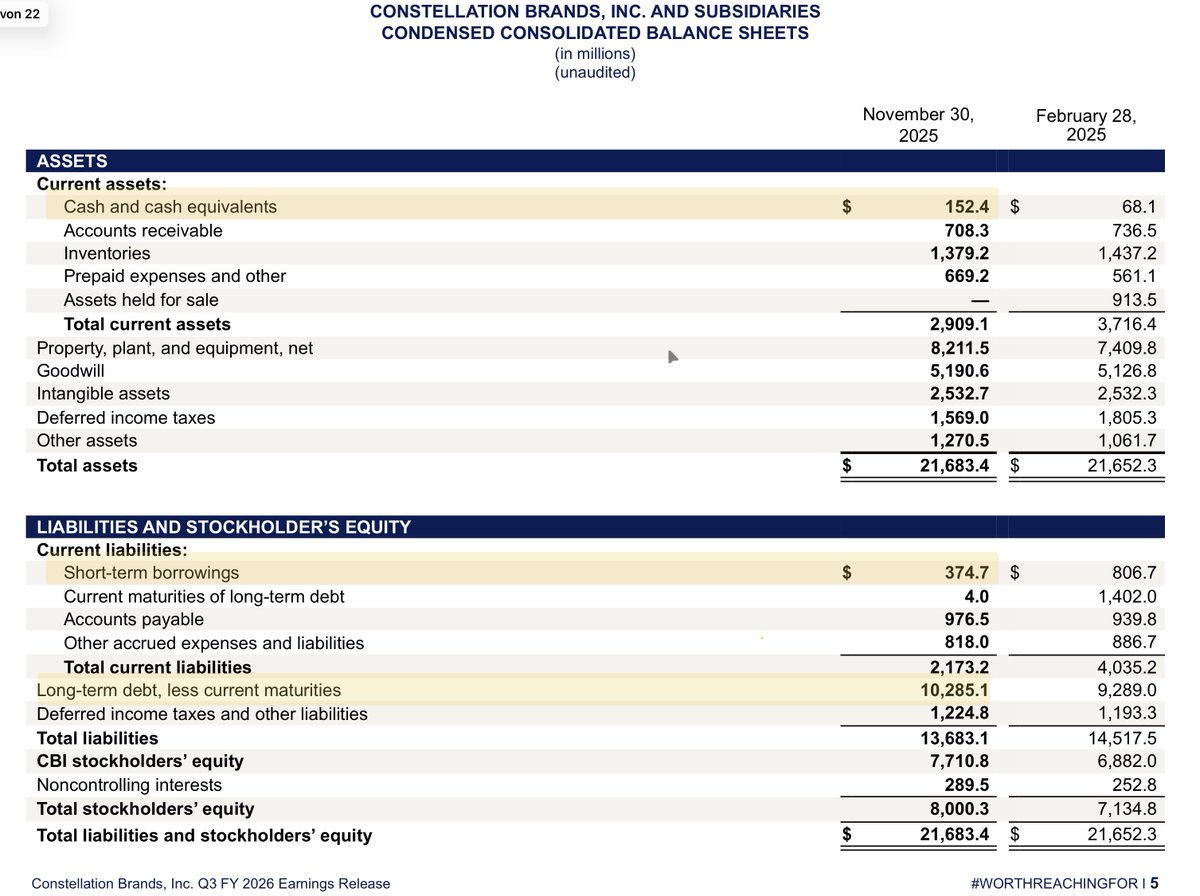
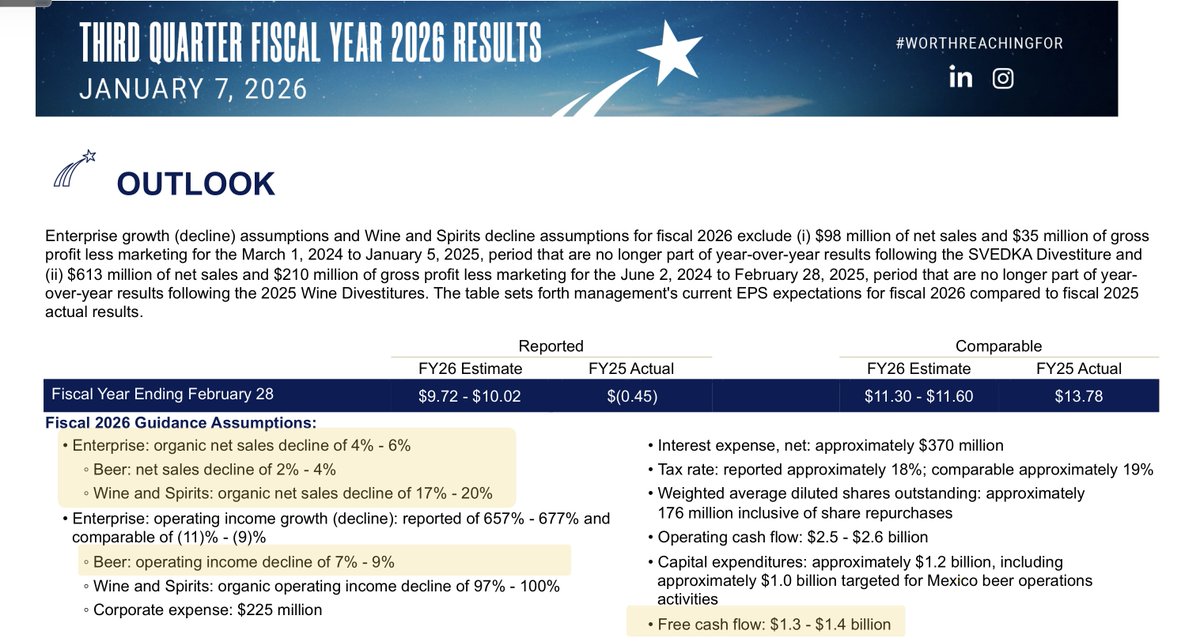
In January I asked: cheap at an EV of 34 billion USD on 1.4 billion USD FCF, for a shrinking business?
148 USD then, 113 USD in September, 144 USD now.
https://t.co/RtWd7YtxtS
$STZ
insane. The stock got almost cut in half.
this alone for many seems to be a sign to jump in, bc “the stock is cheap”.
is it really — EV of 34 billion / 1.4 billion FCF?
with a shrinking business which I believe is structurally affected, not just a cyclical correction?
Whirlpool $WHR, May 2026:
"do NOT invest based on past performance
-> this includes track records + so called dividend histories"
45 USD then, 26 USD now.
Dividend cut since.
Bankruptcy possible.
A dividend record describes the past.
Cash flow pays the next one.
https://t.co/YfeCxokKKj
$WHR Whirlpool, home appliances maker, has shown what I’ve been preaching for long.
-> do NOT invest based on past performance
-> this includes track records + so called dividend histories + also these useless titles
all the above can quickly become irrelevant when circumstances change.
Northern Dynasty $NDM.TO ($NAK), February:
North America's largest undeveloped copper deposit, and a "high-risk, high-reward coin flip".
I stayed sidelined.
2.04 CAD then, 0.82 CAD now.
A deposit is not a stock until it is permitted.
https://t.co/XQF6h8Fvox
4/4
High-risk, high-reward coin flip:
multi-bagger potential vs possible collapse from regulation.
I weigh the massive copper prize against salmon risks and stay sidelined — but the setup is intriguing.
Read the full deep dive on Pebble's case here: https://t.co/sGuDiMTOQz
$NAK
Paladin Energy $PDN.AX placed new shares at 7.80 AUD last week. Today: 6.19 AUD.
October 2024: I preferred physical uranium via Yellow Cake $YCA.L over Paladin,
"with much less execution risks."
Since then: Paladin −39%, Yellow Cake −5%.
https://t.co/T2f60iSic6
@FL17112012 I closed the case for my members of my blog.
but what is very interesting, with Yellow Cake I outperformed for example highly-celebrated Paladin Energy $PDN – with much less execution risks.
https://t.co/0sFJcpuNz9