Ok i’ve been rereading @naval this week and honestly half of his stuff is better investing advice than most investing books
so here are 15 lessons from naval that every investor should hear. some of these hurt a little 🧵
Yesterday I came home, and water was coming out of the ceilings in all rooms of my apartment.
Estimated damages? €50.000/€70.000.
I'm grateful I am all-risk insured for everything inside and outside my house.
A significant headache, but fully covered for storm damage.
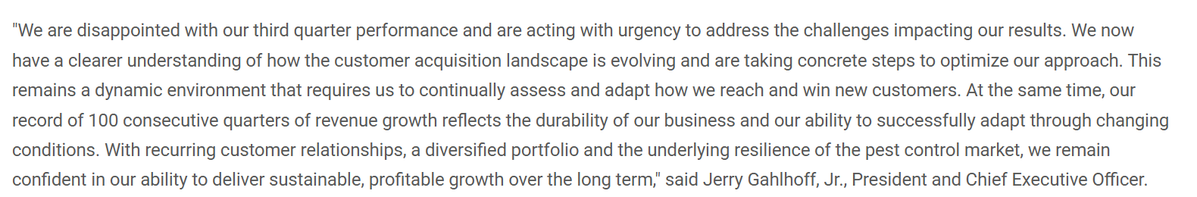
Rollins $ROL Q3 26 management comments 👇
This is the kind of thing you want to read in a difficult situation: there are not trying to hide the difficulties...
Results were slightly under expectations but organic growth was still above 4%
I remember calling out $NVO at $60, saying the bottom was near and the business would turn around.
Oh boy, I was soooo wrong. That's on me :)
I'm sure anchoring bias was at play here, and look where it brought me. Another good reason to not blindly follow anyone here.
Genuine question here
$CSU is in the VMS. However, this pool is finite. At some point, they would need to go into HMS, right? As Constellation grows, it must do more and bigger deals, and to do them, it increasingly moves into larger, more contested, and less moat-protected territory.
What would the future of $CSU look like then? Can it still be the ''compounder'' it is today?
There's a difference between giving AI your own draft to make it clearer, tighter and more consistent, and just typing "write me xyz."
If management wrote the outline and had AI polish it, I don't mind. The problem is when nobody thinks it through and they just read out whatever the AI hands them.
$NFLX biggest risk is YouTube $GOOGL.
I honestly think these two can run a peaceful duopoly over streaming and long-form content.
There will always be a loyal following for Netflix with their specials, and the same for YouTube with their specials and creators.
This micro-cap is going to shake-up the entire market.
No analysts coverage, strong earnings growth, competent management, and playing into a extremely potent secular trend.
You can read it via the link in my bio. 🔗
“Q3 churn, both globally and in the United States, improved year-on-year. It is better than forecast. It is already industry leading. The ultimate determinant of are we delivering that value is the reaction to price changes. Those recent price changes that we did, including in the United States, have gone well.”
And
“Netflix subscribers are paying the least per hour of viewing compared to other SVOD offerings in the country. In some cases, they would have to pay more than double per hour for a competitive service.”
Were said in the last earnings call of $NFLX. This should make you very, very bullish.
Just saying.