Scott Bessent, at his confirmation hearing in Jan/2025 to be Treasury Secretary: "the tragedy going on in Ukraine is one of the greatest tragedies of my adult life ... I believe that the sanctions [on Russia] were not fulsome enough. I believe that the previous administration was worried about raising US energy prices during an election season... if I'm confirmed and if President Trump requests ...I will be 100% on board for taking sanctions up."
Mark Warner (D-VA): "I very much appreciate your willingness and I hope you will be an advocate for keeping those sanctions on and actually advancing them even further."
https://t.co/kceZaeZdKf
Expired: AI will take your job.
Tired: A human working with AI will take your job.
Wired: A human working with an unreleased model at an AI company will take your job.
🇺🇸 US AI imports have *doubled* in just one year, from roughly $500bn to over $1,000bn annualised.
In August, AI related goods imports represented 27% of total imports (up from 10% in the last decade), or 3.3% of GDP (up from 1.3%).
Stirrings of a sovereign -bank loop?
France's banks are very large, 3 times French GDP. In August, insuring their debt via CDS cost the same as German banks. Why, if the banks hold few (4% of assets) bonds? The link is the state guarantee: we still don't have European deposit insurance!
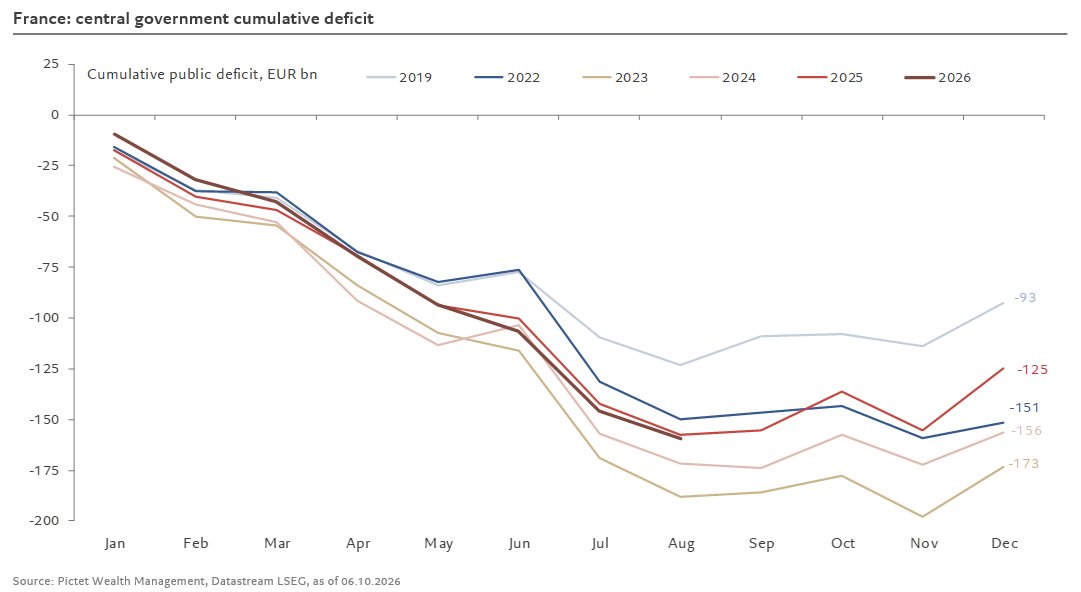
🇫🇷 French budget execution remained broadly stable through August (€159.6bn deficit vs €157.5bn in 2025). Fiscal revenues rose €6.4bn but spending rose €13bn (interest burden, defense, energy). This year's revised deficit target may be achieved, but the hard part lies ahead.
We’ve not reached the stage yet where Le Spread make all the headlines of the French media though. Nothing like Lo Spread in Italy back in the days.
And no, the ECB is not going to step in at these levels.
Closer to the beginning than the beginning of any kind of resolution.
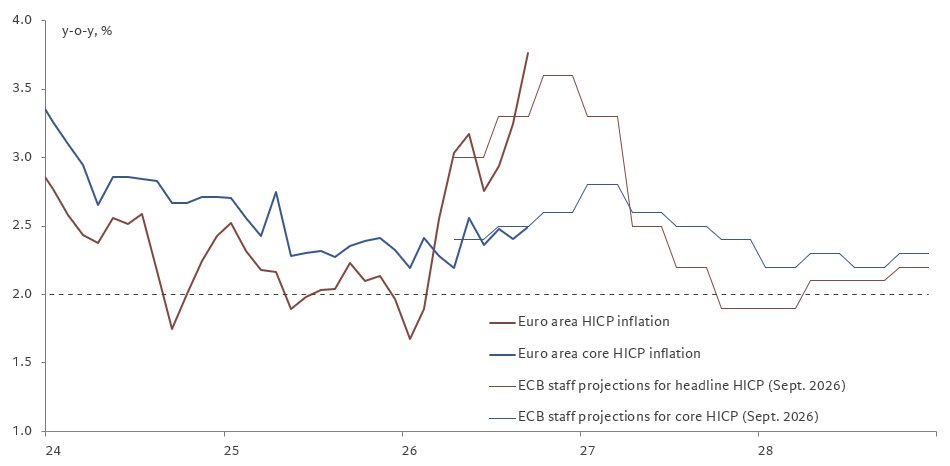
🇪🇺 No good news on the European inflation front, and the longer it lasts, the worse it gets.
But at least core inflation was in line with ECB staff projections.
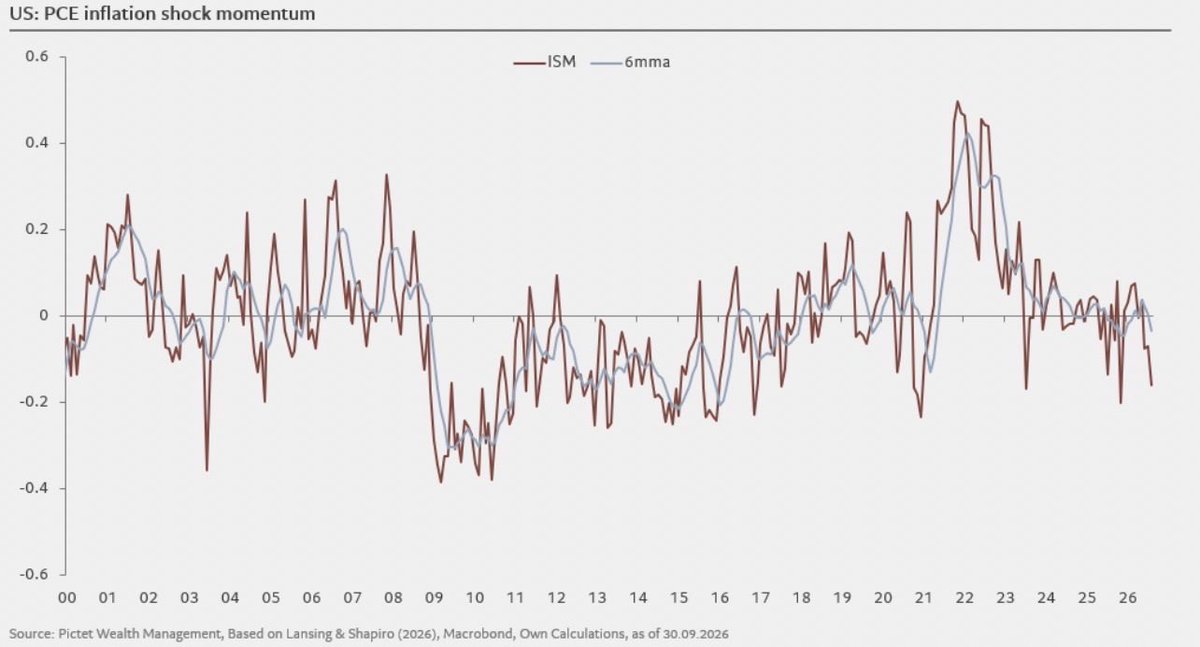
🇺🇸 As a result of the soft PCE and the revisions, the Inflation Shock Momentum Index based on the San Francisco Fed model improved significantly through August.
The AFT estimates that borrowing needs will rise to a record €340bn in 2027 (up €28bn from 2026), against the backdrop of a 5% deficit, rising interest burden (€73bn, up €10bn) and larger redemptions (€190bn, up €19bn). https://t.co/8iEzNvkRwV
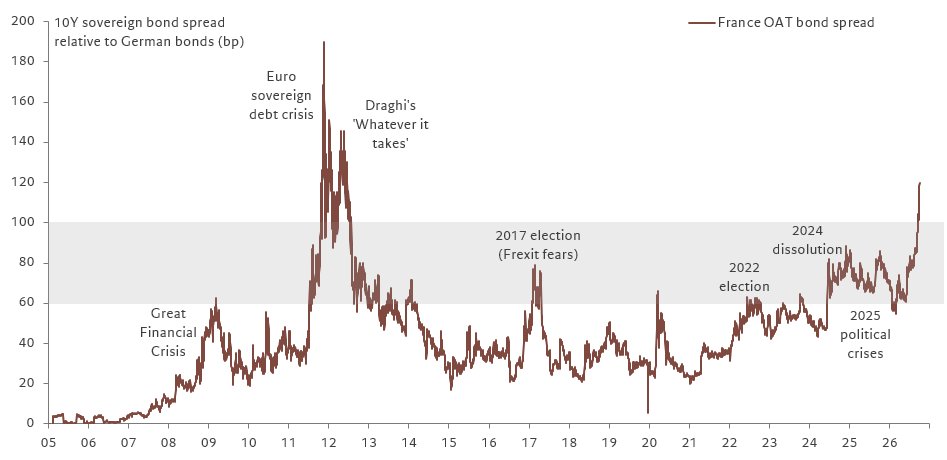
🇫🇷 Le Spread enters a new regime as the rates sell-off hits the weakest links.
OATs facing a perfect storm of political radicalization, shifting opinion polls, weak growth, large deficits and borrowing needs (which the Treasury estimates will rise by €28bn in 2027, to €340bn).
🇪🇺 Euro area PMIs defying oil and political gravity, partly driven by rising AI and defence spending. Yes, inflationary pressures are rising again, but PMI gauges look contained and risks of second-round effects remain limited.
Interesting that the SEP seemingly did not incorporate the BEA's revisions, but Warsh noted that core PCE looks like it will be 3.2%. Under the old methodology, it was tracking at 3.4% in Aug, so seems like the Board staff's est of the BEA's revisions is about -20bps.