My latest research on statistical arbitrage - pairs trading in #stock#futures has just been published with @SpringerNature in Asia-Pacific Financial Markets Journal. https://t.co/TrwKMRL12f
Read here: https://t.co/xfoPUuvGxo
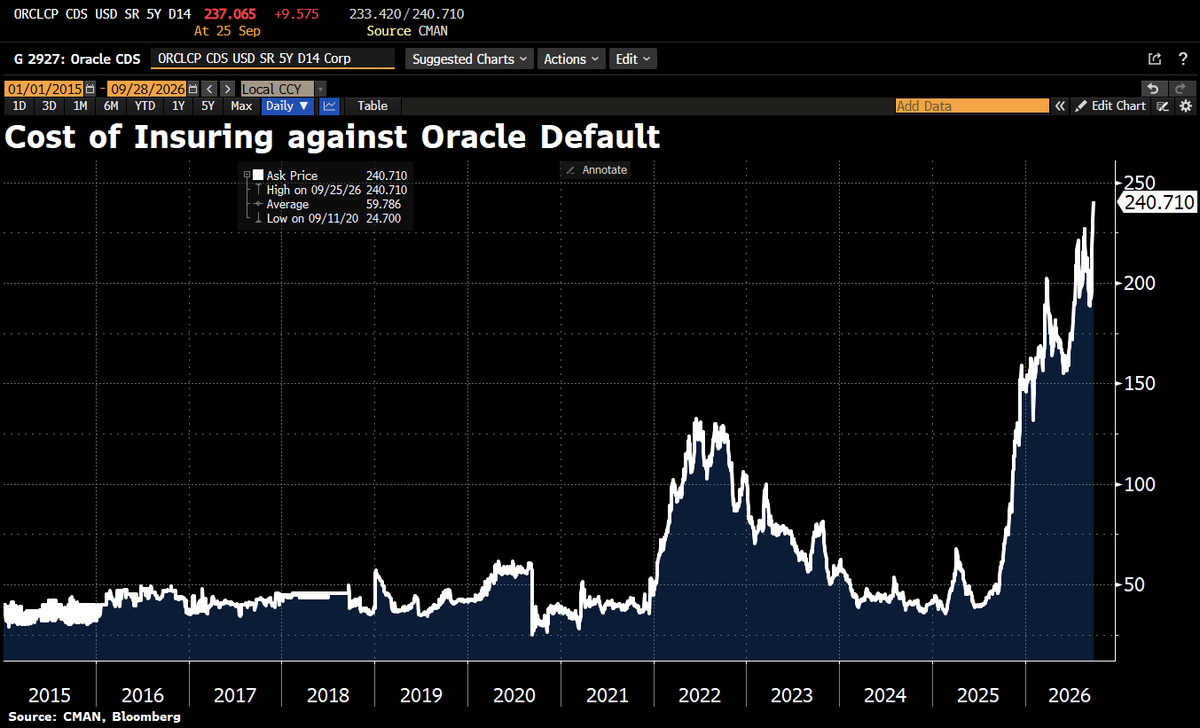
OUCH! The cost of insuring Oracle against default has surged to a record after its force majeure notice for Project Jupiter rattled AI data-center debt markets. 5y CDS quoted at 240.7bps imply a 19.1% probability of default by end-2031, assuming 40% recovery. Almost 1 in 5!
Oaktree Capital Management Co-Chairman @hmarksofficial urges perspective on interest rates: "These are not high rates," he says. "These are some of the lowest rates of the last 50 years." https://t.co/AH3bqRJTem
Breaking news: The 10-year US Treasury yield hit 5% on Monday for the first time since 2023, as surging oil prices battered government bonds across the world. https://t.co/zKfBS0eAY7
Martin Armstrong made a very interesting comment in an interview
He mentioned that central banks buy GOLD despite negative carry because you don't hold your adversary's paper into a conflict. That implies price-insensitive official-sector demand that persists regardless of real rates.
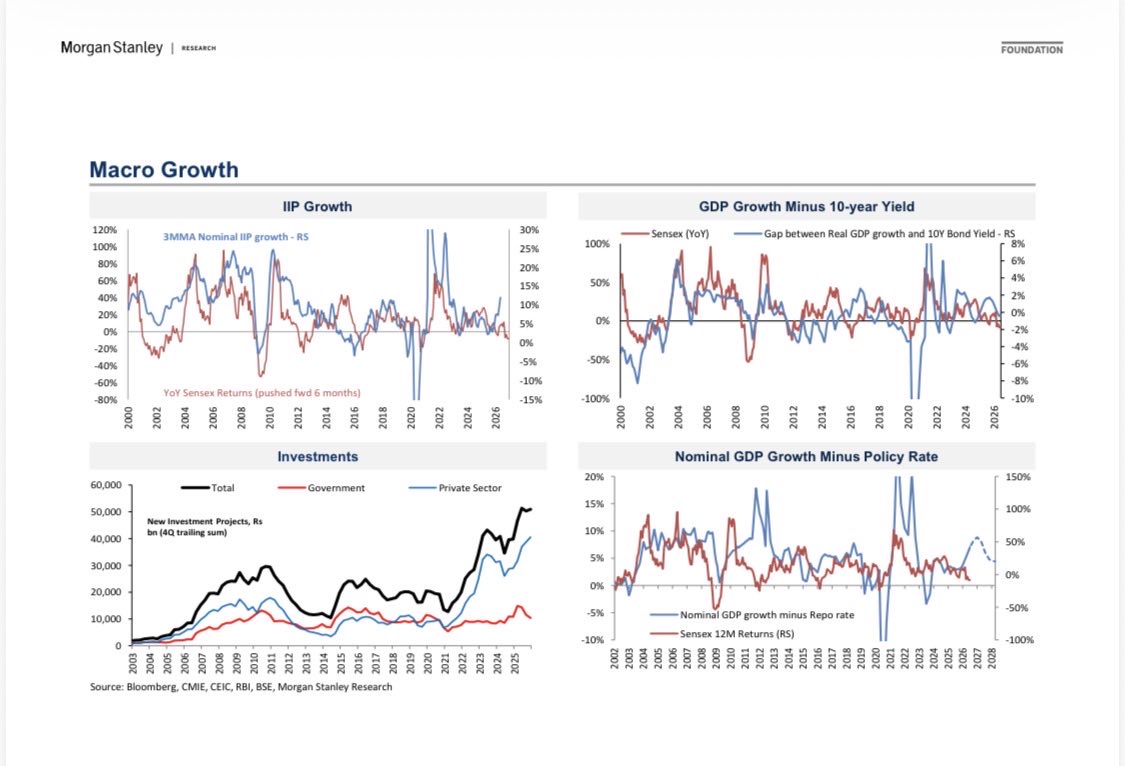
As expected, with the fiscal headwinds fading and monetary headwinds (falling credit growth till 1HFY26) becoming tailwinds (credit growth accelerating), GDP growth is surprising on the upside, and should help push up consensus trend-growth estimates to 7%-plus. That is, with a neutral fiscal and monetary policy, the economy should still register 7.5% growth.
In this light, I was shocked to see the ill-educated and egregiously wrong claims made by some that if the 'original' base of June-2025 quarter was used, growth in the June-2026 quarter would be much lower.
The new series introduced in Feb-2026 cleaned up the data and also significantly improved the methodology. For those who track this for a living (and I used to be one such till 45 days ago) - the downward revision in the base was known in March (see our note published on 1-Mar):
https://t.co/3KCHsbIUV9
As our note acknowledged, the new series increased credibility of estimates of real output.
That claim is so obviously wrong that several logical rebuttals have already been made. But bad information tends to travel further than good information, and so it is important to reiterate and reinforce the argument.
That such claims got traction is itself surprising, given that easy-to-track and not-possible-to-fudge indicators of economic activity have been so robust. While June-quarter data was strong, that momentum has picked up:
- personal vehicle (cars, SUVs) dispatches grew 35% YoY in August despite just 9% growth in exports. Even two-wheeler growth is now >20% (though helped by strong exports).
- And if that was consumption, commercial vehicle dispatches grew >40%.
- tax collection growth has picked up meaningfully. This is as real as it gets.
- Credit growth continues to surprise on the upside (albeit on a low base). Last year most believed the then-weak credit growth was a demand problem, whereas we steadfastly stated it was a supply issue - it has for now been addressed.
- indicators of construction are robust.
Hopefully, now there will be fewer people asking "why private sector investment is weak," given that there is clear evidence of investments.
That said, there is still slack in the economy, as seen in weak real-wage growth. It may take several quarters of above-trend growth for that slack to tighten, and bring back sticky inflation pressures.
Strain is spreading across private credit portfolios, with signals of stress in the market reaching levels last seen in 2017, according to an FT analysis. https://t.co/hGWTQ6Ccx2
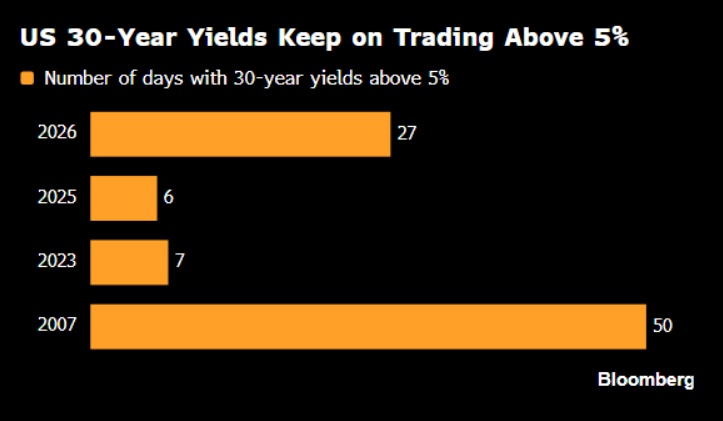
Gold is almost at $4,400, while the US 30-year yield is rising to 5.25%.
Gold has no cash flow, so rising rates are bad for gold. Except when the Fed is losing control of long-term rates. Then it is extremely bullish for gold.
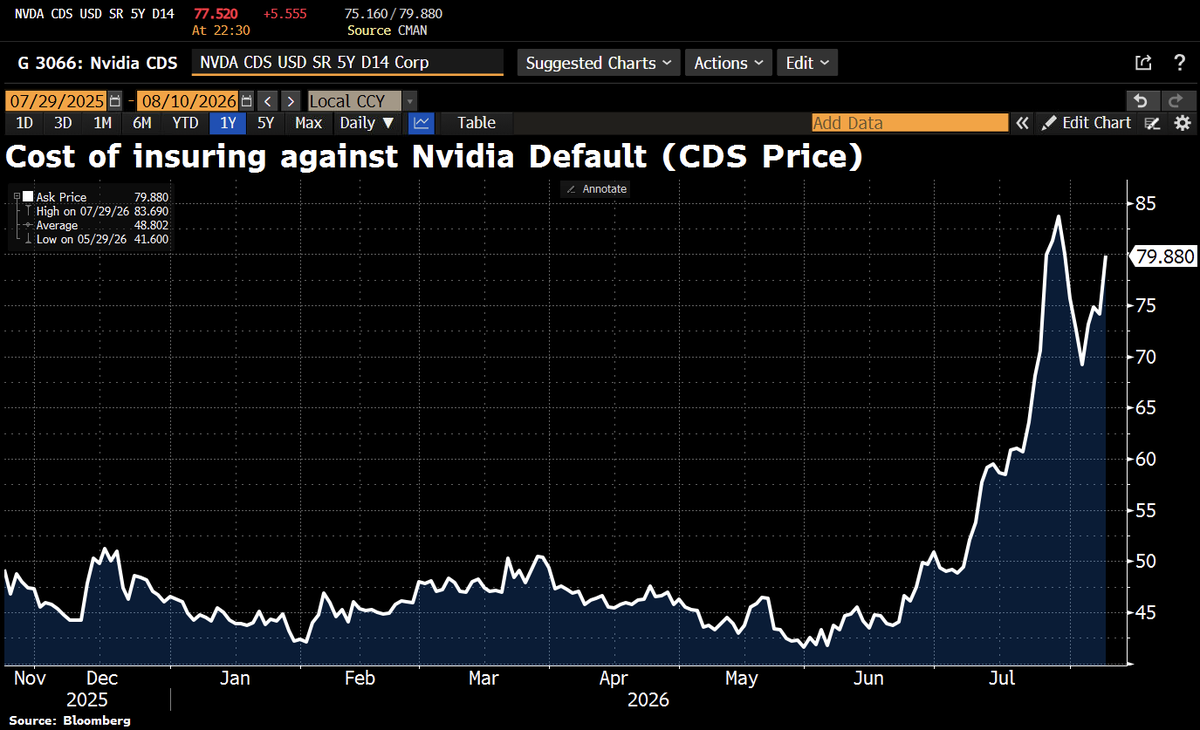
$500bn of Wall St money to help Nvidia's customers buy Nvidia chips. Jensen calls compute "an investable asset." This is the chart nobody put in the press release. NVDA 5Y CDS jumps by almost 6bps. The cost of insuring Nvidia debt has doubled since late May, from 41.6 to 77.5, just shy of the July 29 record at 83.7. That seems strange, b/c Nvidia is generating $500bn in additional demand w/o drawing on its own balance sheet. But it also shows that leverage in AI financing is continuing to rise. https://t.co/5tRowlFUtw
A closely watched gauge of risk in holding the debt of companies at the centre of the AI boom is rising rapidly, underscoring growing jitters over Big Tech’s vast spending on data centres, chips and computer memory. https://t.co/MOqkAUSm8T
When the report card for July is out, there would be blood on streets.
Between MAG7, AI, semis, chips and South Korea.. I gather some funds are down 30% + MTD.
On my next letter to Santa Claus, I'm asking for 24/7 high-res satellite imagery of the Middle East.
And because I had being naughty, Santa can add a lump of coal. I won't say no to that if it comes as an extra.
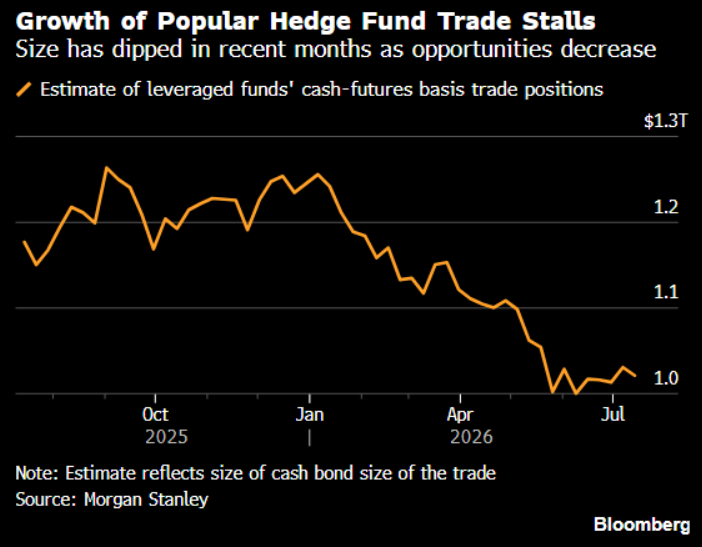
Watch the long bonds. Treasuries pressured by AI's debt explosion, rising inflation vol, (per the great chart from @Bloomberg's Simon White). Basis Trade's shaky state, #oil back near 100, many factors, many charts. Not sure how much longer PE and PC can hold their breath.
Alphabet's 100-year Sterling debt has lost more than 7% since its issuance in February. This isn't entirely surprising given the duration, UK-related political risk and glut of Alphabet-related debt sales this year. (1/2)
What does that even mean- Singapore NRIs pay withholding tax to whom. You mean individuals deduct 10% tax and give to govt. That would reduce interest payment to the GIFT city based entity, not increase cost for NRI. Anyway looks like complete nonsense to me.
It looks that anyone negative on India currently tries to prove that FCNR and other flows not happening so that confidence is shaken and that is why you are getting new negative stories on this FCNR scheme every day.
Yes nature is healing.
I am getting increasingly confident that We should get ready for 11-12% nominal gdp growth over next couple of years.
Corporate earnings are function of nominal gdp growth and not real GdP growth.
US President Trump:
"... I want to thank China, President Xi, he stayed neutral, totally neutral, and I appreciated it; and I want to thank Vladimir Putin, he was very neutral. They could have made it much more difficult for us..."
I have found the key to happiness is gratitude. The thankful are by nature humbled by the grace of others and cognizant of the miracles that surround us every single day.