20+ yrs in finance. Ex-J.P. Morgan analyst. Stocks & businesses. Follow my daily stock notes. Here to share & learn with investors across industries. 👇
Firmly bullish $TSLA into earnings. SpaceX merger talks and a stronger tech tape are fueling interest. No deal is agreed.
Hold $380–382 and close above $390: I'm watching $400, then $410–420 if $400 clears.
Earnings after the bell can reset the setup. Respect the gap risk.
@glennyboiboi Check out some of my recent posts on where I think the market is headed when you have a minute. Hope they’re helpful for your trading! Feel free to share what sectors or stocks you’re watching, too. I might be keeping an eye on the same ones
@BullTheoryio Even with Musk's headline $1T revenue forecast, staying cautious around local risk factors is key, a flush to lower prices is still very much on the table
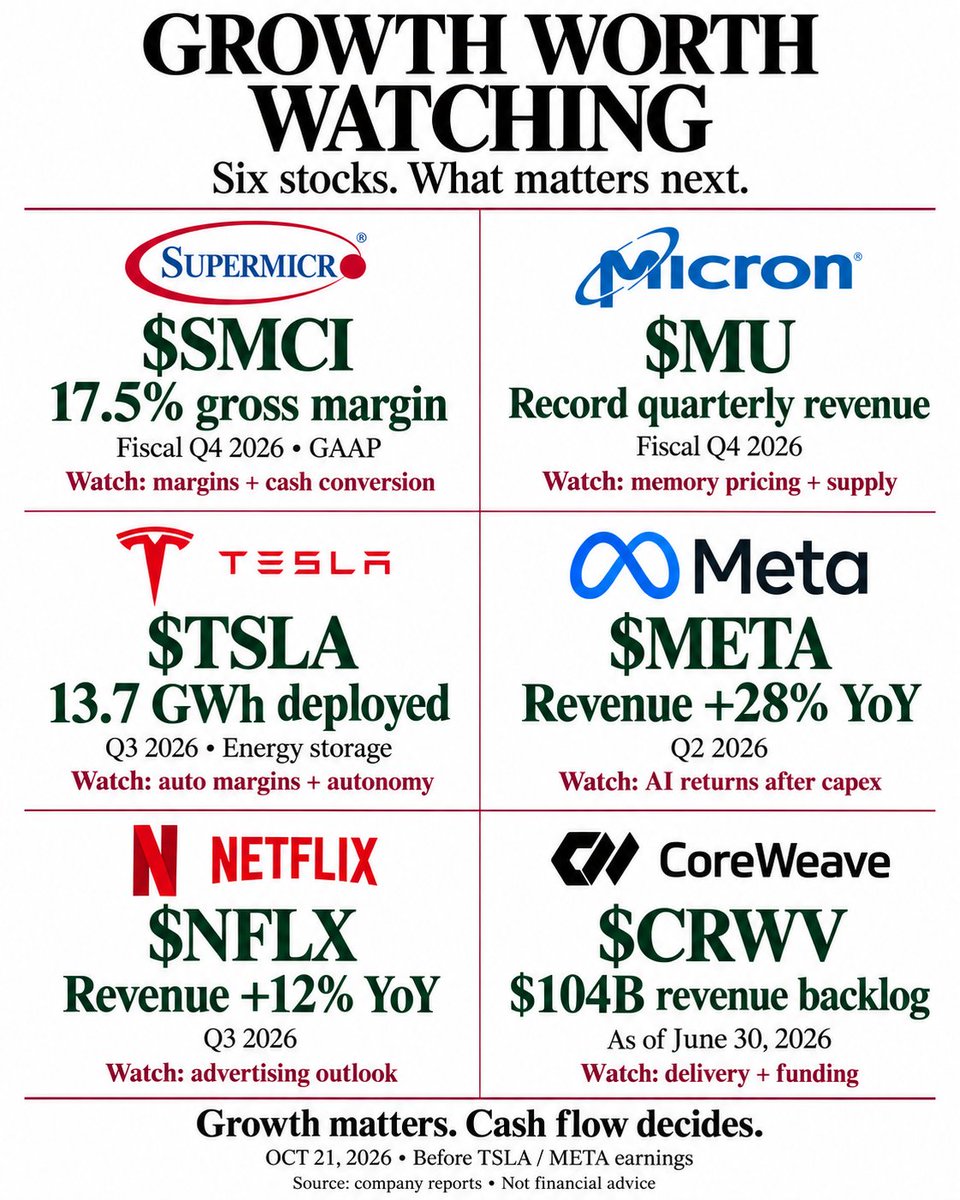
Six stocks on my screen. The question isn't who benefits from AI. It's who turns growth into cash—and what I'm paying for it.
$SMCI
Fiscal Q4 revenue reached $11.1B, with GAAP gross margin improving to 17.5%. That's meaningful progress beyond simply shipping more servers. The next test: sustaining margins while keeping inventory, receivables and funding needs under control.
$MU
Record fiscal Q4 results strengthen the AI-memory thesis. I like the demand exposure, but memory is still cyclical. I'd value it on sustainable earnings, not assume today's pricing and margins last forever.
$TSLA
Q3 energy-storage deployments reached 13.7 GWh. That's a tangible business alongside the autonomy opportunity. For earnings, I'm watching automotive margins excluding credits, cash flow and deployment economics—not just delivery volume or robotaxi headlines.
$META
Q2 revenue grew 28%, but operating income fell 8%. That gap matters. AI can improve ad performance, yet infrastructure spending and depreciation can absorb the benefits. My focus: whether incremental revenue produces stronger cash generation after capex.
$NFLX
Q3 revenue grew 12%, with a 34.6% operating margin, partly helped by expense timing. The lowered advertising outlook complicates the bullish case. Pricing power and cash generation remain attractive; renewed confidence needs evidence of durable growth.
$CRWV
Roughly $104B of backlog at June 30 supports the demand story. But Q2 net interest expense was $640M against $2.58B of revenue. Backlog isn't cash, and adjusted EBITDA isn't cash left for shareholders. Financing and execution are central to the thesis.
My lean: MU and META deserve the closest fundamental work. SMCI has improving operating evidence. TSLA and CRWV need more assumptions to go right. NFLX needs its growth outlook to regain credibility.
Constructive on the opportunities. Selective on valuation.
#Stocks #Earnings #AI
As of Oct. 21, 2026, before TSLA/META earnings.
Not financial advice.