OMG! PEOPLE!!!! Learn the facts about Social Security!
SS was NEVER meant to live off of. It was meant to be a SUPPLEMENT to an individual’s funds, savings, and outside support in their final years of life. The original intention was, at MOST, 40% of their living expenses.
Today, only 40% of Americans have retirement savings significant enough to live off of when supplemented with SS.
When the retirement age was originally set at 65, barely HALF of Americans ever lived that long. The expectation was also that most of those still alive would only need it for a few more years until death.
Today, even though the retirement age has only been raised to 67, almost 83% of Americans reach that age and live well past it. The average life expectancy is 78.5. This is significantly more than the original projected 40% of retirees staying alive when SS first started, and instead of a supplement to bridge the few extra years before death, it’s now covering more than TEN YEARS past the set retirement age!
Complicating the program further is we have more adults drawing from SS than we have putting into it.
To sum up:
* 83% of Americans are living to “retirement age” and living 11 years on average past it
* Majority of Americans don’t have a financial plan that covers the remaining 60% of living expenses beyond supplemental SS funds, with many falsely believing SS alone is meant to provide a livable income. It’s not.
* We don’t have enough younger people to keep funding the large number of long-living “retirees” drawing from SS
*If we really wanted to do SS as it was originally intended, we would set the retirement age to 78 and educate citizens on how to save in order to fund 60% of their living expenses after retirement.
Life don hard reach the point where CREDIT ALERT no longer gives us joy. 😭💔
Once money enters our account, we don’t even smile anymore. Na to calculate who we go pay, which debt we go settle, and the expenses we still need to handle.
No be say money no dey enter, na say money no dey stay.😔
God abeg, make we experience the kind of financial breakthrough wey go make us celebrate credit alert again, not calculate debt. 🙏❤️
Not Every Loan Is Good for Your Financial Growth.
Some loans can help you build wealth, while others can keep you trapped in a cycle of debt.
Borrowing money to invest in a productive business, acquire an income-generating asset, or improve your skills can create opportunities for financial growth. However, taking loans to impress people, maintain an expensive lifestyle, buy unnecessary things, or gamble with borrowed money can damage your financial future.
The problem begins when your income is spent repaying debts instead of saving, investing, or building assets. High interest rates, late payment penalties, and repeated borrowing can make it even harder to move forward financially.
Before taking any loan, ask yourself three questions:
- Will this loan help me generate income or improve my future?
- Can I comfortably repay it without sacrificing essential needs?
- Is the benefit worth the total cost of borrowing?
Remember: Just because you qualify for a loan doesn't mean you need one. Learn to distinguish between borrowing to build wealth and borrowing to satisfy temporary desires.
Build the habit of living within your means, saving consistently, and investing wisely. Your goal should be to make your money work for you, not spend your life working to repay debt.
Financial freedom is not about how much money you can borrow; it's about how wisely you manage what you earn.
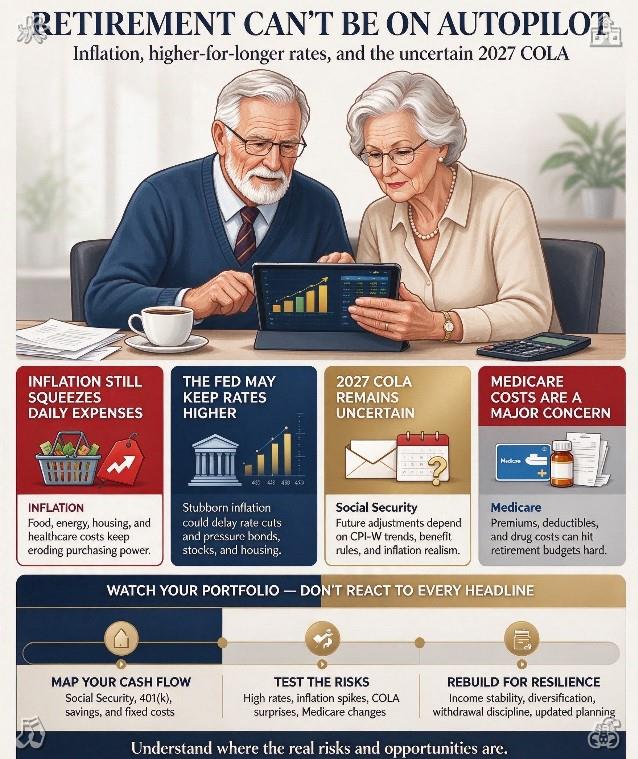
Retirees: inflation is squeezing budgets, the Fed may keep rates high, 2027 COLA is uncertain, Medicare costs are a concern. If you rely on Social Security, 401(k), savings, you can’t ignore markets. Monitor your portfolio, not headlines. Retirement isn’t autopilot.
2027 Social Security COLA may rise to 3.5%, above the expected Medicare Part B premium increase. But other rising costs may eat up the rest of COLA. https://t.co/PojozTK7G5
Three years ago, I used my mother’s name to take out a $42,000 loan.
She never gave me permission.
I had lost my job, my marriage was falling apart, and I was convinced that if I could just survive six months, I would recover financially and put everything back before anyone knew.
I forged her signature on the paperwork.
I thought I was saving myself.
Instead, I put my mother in debt.
When the bank eventually contacted her, I confessed.
She was devastated.
But she paid the loan.
She never told my siblings what I had done. She simply told everyone that she had made a bad investment and lost money.
I spent the next three years trying to rebuild my relationship with her.
I thought we were okay.
I had no idea she was still keeping track of what I had done.
You're single with no kids or business, but you're busy taking loans from different loan apps. What are you using the money for?
I know things are hard, but trying to stay debt free is a form of self control everyone needs to master. If you can't control it now that you're single, it'll only get worse as your responsibilities increase.
I used my girlfriend's savings to buy her engagement ring.
She doesn't know yet.
We had been together for six years, and she had been asking me when I was finally going to propose.
The problem was that every time I saved enough money for a ring, something happened.
Her mother needed help.
Her younger brother's school fees came up.
Our rent increased.
And somehow, I always ended up using the money.
I never blamed her for it because I knew she would do the same for me.
Then one day, she told me she had started saving secretly.
She said she wanted to have enough money for us to start our married life without depending on anybody.
She showed me the account.
There was a lot of money in it.
I was proud of her.
Then I made the stupidest decision of my life.
I withdrew some of it.
Not because I wanted to spend it on myself.
I wanted to finally propose.
I bought the ring she had once pointed at in a jewellery store and said,
“If you ever propose to me, don't buy me anything bigger than this.”
I planned everything.
on the brightside i will be saving so much money in the next few months lmfao no more money on postszn things and also no more sofi trips for the rest of the year :p
Nasdaq listed it, Solana moved it. A drone defense company did more volume onchain than on its home exchange, while Fiserv plugged in 90+ banks and credit unions. Q3 app revenue hit $365M, the tenth straight quarter Solana has led.
Here’s everything that happened this week:
📰 Headline News
- @Fiserv’s digital asset platform launched on Solana, enabling Roughrider Coin transfers across 90+ banks and credit unions
- @openstandard’s OUSD launched on Solana, with reserves at BlackRock, Lead Bank, and BNY
- Solana led app revenue for the 10th consecutive quarter, generating $365M in Q3, up 42.6% QoQ
- Tokenized Powerus ($PUSA) shares did more volume on Solana than on Nasdaq, day after listing via @sunrise and @Backpack Securities
📰 Launches
- Solana’s tokenized-equity holders reached an ATH of 1.2M, with 775K joining in September
- @sunrise brought Coinbase’s wrapped Cardano asset, cbADA, to Solana via @Chainlink CCIP
- @domaprotocol opened Frontier on Solana via @Loopscale, bringing tokenized domains onchain
- @FermiTrade launched an onchain perp DEX with verifiable first-in, first-out order matching
- @Sirius_Protocol went live with private spot and perps trading, keeping positions off the public feed
- @cloak_ag launched private payroll with spreadsheet uploads and one-click payouts
- @metaplex introduced MPL-3643, a standard for permissioned RWAs and tokenized securities with built-in compliance
- @BackpackOnchain added Solana v1 transaction support for more complex trading routes and DeFi interactions
- @jup_mobile introduced the Claynosaurz x Jupiter Card with 2% cashback, full FX fee rebates through 2026
- @DecryptMedia and @MyriadMarkets introduced The Information Exchange, connecting news and markets
- @useKled unveiled Kled V3 for collecting real-world consumer datasets in under 72 hours, powered by Solana payments
- @flint_trade_ announced its onchain perp DEX on Solana
- @proto_xyz previewed markets for trading exposure to rental GPU power usage, targeting Q4
- @DGLD_Official teased a Solana expansion for its token backed by physical PAMP gold stored in Switzerland
- @solana_devs introduced Solana Scholars, offering funded three-month research internships for PhD students
- @joinfrontier wrapped its Seoul edition, with Solana Summit Singapore next on October 6
- @SolanaEvents confirmed the next wave of Breakpoint 2026 speakers
📰 Milestones
- Solana’s September app revenue reached a nine-month high of $180M, accounting for 32% of revenue across chains
- Solana led spot DEX volume for the fifth consecutive quarter with $197B in Q3, up 16.6% QoQ
- @xStocksFi recorded $1.8B in September trading volume on @Raydium
- @Raydium crossed $6B in cumulative tokenized-stock trading volume
- @byreal_io surpassed $5B in total trading volume on its first anniversary
- @nansen_ai hit weekly ATH for x402 transactions on Solana, with payment volume exceeding all other networks combined
- Tokenized stocks pledged as collateral on @kamino exceeded the scale of any other chain by more than 3x
If you enjoyed this week’s newsletter, please share it with an RT.
Artwork by nub
Natalia Silva vs. Wang Cong for the Women’s Flyweight Championship is the MAIN EVENT of UFC 332! 🚨🔥
#UFC332 | Saturday | 🎥 Stream TNT Sports on HBO Max ▶️ https://t.co/5IdgcENAWm
💳 $XLM JUST PROCESSED A RECORD WAVE OF REAL-WORLD SPENDING
Tracked stablecoin card spending topped $1.1 BILLION in September.
Around $69.3 MILLION of that activity was processed on Stellar.
This isn’t money sitting idle in wallets.
It’s stablecoins being spent in the real world.
That is exactly the kind of adoption $XLM was built for.
Stablecoin card spending hits a record 789 million dollars in September reported today.
Everyday global commerce is rapidly integrating stable digital assets.
Swap noncustodially to keep absolute control of your keys.
Trade securely.
#Crypto#Swap