#WATCH | Young earners should prioritise repaying loans, securing adequate insurance and building a regular savings habit before focusing on investment returns, says @harshroongta, founder and principal officer of Fee-only Investment Advisors.
https://t.co/K2TTQ85CoQ
📢 NISM Investor Education Webinars | 29 October 2026
Financial goals evolve with life’s milestones. Are you prepared to plan your wealth for the future?
Join NISM’s upcoming Investor Education Webinars for valuable insights into financial planning and investment decision-making .
📅 29 October 2026 | 4:00 PM – 5:00 PM | Hindi
आपका निवेश आपको मंज़िल तक तो पहुँचा ही सकता है, पर क्या आपके पास इतना सब्र है कि आप पूरे सफ़र में टिके रह पाएँगे?
Speaker: Harsh Roongta , चार्टर्ड अकाउंटेंट एवं पर्सनल फाइनेंस एक्सपर्ट
📺 Webinar will be hosted LIVE on the NISM Investor Education Webinar YouTube channel.
🔗 https://t.co/6BMqrqW0G8
🔗 Register here: https://t.co/CvwFapz5Ka
Empowering investors through knowledge.
@harshroongta Harsh ji,
You mentioned it perfectly,My sen citizen inv facing issues of sign mismatch while going 4 a update after updating name in pancard,aadhaarcard & bank trying 2 comply with d regulations
Some soln need 2 b provided in such cases.
Kindly throw some light on such issues.
@harshroongta You just hit the nail on the head… wish politicians holding sensitive positions listen and implement it and not talk about it when out of power. So many families are distressed coz of lack of uniform inheritance laws and opaque rules
@harshroongta *market reforms*
A suggestion,why not MITRA,send registered post on the address available with the mutual funds and company. It will help to family members to know about investment. They can search by taking help from local bodies.9460411116
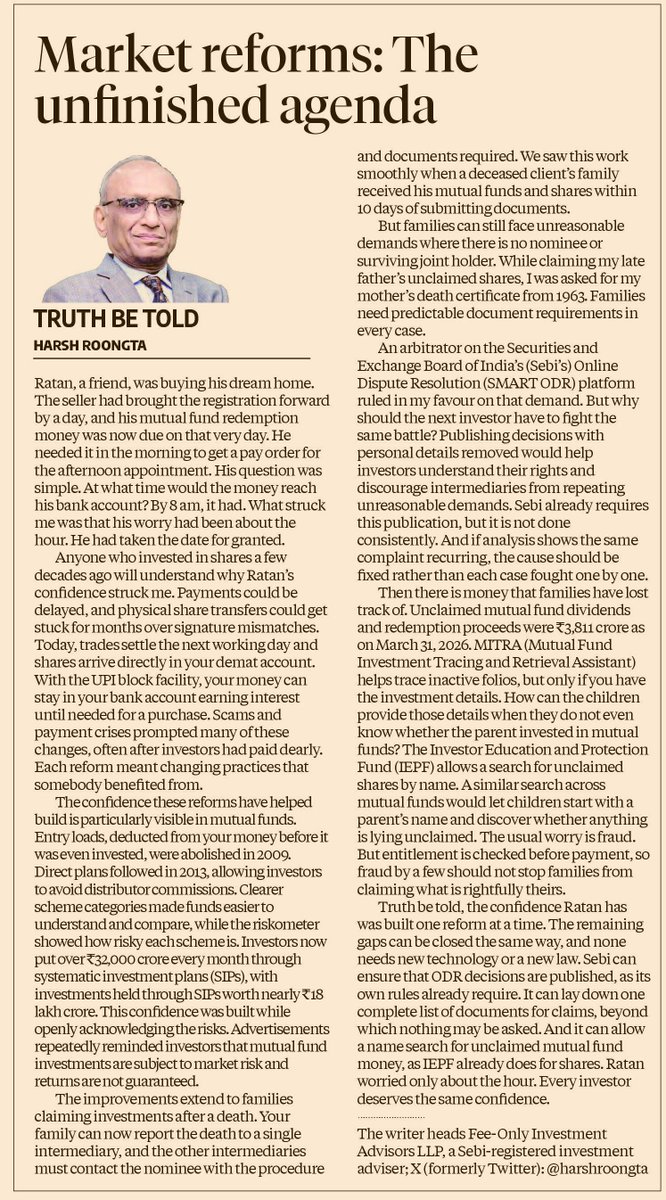
𝗧𝗵𝗲 𝗰𝗼𝗻𝗳𝗶𝗱𝗲𝗻𝗰𝗲 𝘄𝗲 𝗻𝗼𝘄 𝘁𝗮𝗸𝗲 𝗳𝗼𝗿 𝗴𝗿𝗮𝗻𝘁𝗲𝗱
A friend was redeeming mutual funds to pay for his new home. His only worry was what time the money would reach his account. He took the date for granted.
Anyone who invested a few decades ago will know how remarkable that is. Payments could be delayed, and share transfers could get stuck for months over a signature mismatch. Today, trades settle the next working day, shares arrive directly in your demat account, and the UPI block facility lets your money remain in your bank account earning interest until needed for a purchase.
Every reform stepped on somebody’s toes, and there were a great many toes to step on.
The reforms deserves recognition precisely because we now take so much of it for granted.
A few further steps can extend that confidence to families claiming investments, investors seeking redress and those tracing forgotten money. None needs new technology or a new law:
• Enforce the existing requirement to publish ODR decisions, with personal details removed. Why should another investor have to fight a battle already won on the same grounds?
• Set out complete document requirements for each type of claim after a death, beyond which nothing more may be demanded.
• Allow a name-based search for unclaimed mutual fund money, as IEPF does for shares. How can a family supply investment details when it does not even know an investment exists?
Ratan worried only about the hour. Every investor deserves the same confidence.
My latest ‘Truth be told’ column in @bsindia (Business Standard): https://t.co/8mBIVUvH6Y
#Investing #MutualFunds #InvestorProtection #SEBI @saurabhsmittal@securingLives@smtahil
@harshroongta "Most mis-sold product in India" needs no context either, sadly 😅 The tell is always the same: if the pitch leads with returns instead of cover, it's not insurance being sold to you.
#Opinion | Four reforms to enhance trust in insurance sector
Putting policyholders first requires changes in how #insurance is sold, priced and regulated. @harshroongta proposes four reforms, from commission-free plans on Bima Sugam and fee-only advisers to greater transparency on complaints against insurers and intermediaries.
#PersonalFinance
https://t.co/HQ5bmZsnfB
“𝗧𝗵𝗲 𝗺𝗮𝗻 𝘄𝗵𝗼 𝗮𝗻𝗻𝗼𝘂𝗻𝗰𝗲𝘀 𝗮𝗻𝗱 𝗽𝗮𝘂𝘀𝗲𝘀 𝘁𝗮𝗿𝗶𝗳𝗳𝘀 𝗼𝗻 𝘁𝗵𝗲 𝘀𝗮𝗺𝗲 𝗱𝗮𝘆”, “𝗧𝗵𝗲 𝗺𝗼𝘀𝘁 𝗺𝗶𝘀-𝘀𝗼𝗹𝗱 𝗽𝗿𝗼𝗱𝘂𝗰𝘁 𝗶𝗻 𝗜𝗻𝗱𝗶𝗮” 𝗮𝗻𝗱“𝗖𝗹𝗮𝗶𝗺 𝗱𝗲𝗻𝗶𝗲𝗱”.
Even without any context, you will recognise the person referred to in the first phrase. Unfortunately, you will also recognise that the other two phrases refer to life insurance and health insurance respectively. And that is the problem.
My Truth Be Told column in Business Standard (@bsindia) looks at the far-reaching distribution reforms proposed by @irdaindia . It also gives four suggestions that can still put policyholders first, even if industry pressure stalls the commission reforms.
Read the article here or the image below : https://t.co/k4jeUDCEKJ
#IRDAI #Insurance #BimaSugam #TruthBeTold #HealthInsurance, #LifeInsurance
@saurabhsmittal@securingLives@smtahil@monikahalan
If This is a Bear Market, I Am Amitabh Bachchan
My column in @91basispoints
I have extremely vivid memories of January 22, 2008, when the Sensex fell more than 10% intraday and trading had to be shut down for an hour. And given that, if this is a bear market, I am Amitabh Bachchan.
Of course, a large section of the investors came in only post the pandemic. And they haven't really seen a stock market crash.
When memories of easy gains meet months of stagnation, can investors distinguish a market in crisis from one that is simply testing their patience?
The latest all-time closing high of the Sensex was reached on September 26, 2024. By October 1, 2026, the trough of this fall till date, the Sensex had fallen over 16%.
This fall is number 17 on the list of the top 20 Sensex falls. But more interestingly, up until October 1, 2026, this fall had been on for 735 days. It has now crossed 740 days. This is the second longest fall on the list of the top 20 Sensex falls.
The longest fall of 814 days was between September 12, 1994 and December 4, 1996. But in this case, the Sensex fell close to 41%.
When we consider these factors, the only conclusion we can draw is that the current fall has been rather long and relatively shallow. You can call it a sideways market. A market that’s not going anywhere. And so on.
But this is not a bear market.
If we look at the much broader Nifty 500 Total Returns Index it reached its last all-time closing high on September 24, 2024. The lowest level from that high was reached on February 28, 2025, a fall of close to 19% from the peak.
As of October 6, 2026, this index was around 7.6% lower than the all-time high of September 26, 2024.
https://t.co/MukoAWHaJe
By that logic @monikahalan , we should discourage people from quitting smoking because bidi workers depend on it for their livelihood. Just like the bidi workers may deserve support and alternative livelihoods but their employment cannot justify the harm to consumers.
In this question on livelihoods of agents and brokers, the fact that it runs on the premiums of crores of Indians is often forgotten.
Should consumers be cheated because somebody's livelihood is at stake?
The data in IRDAI's consultation paper maps what is really going on in the industry and links high commissions to consumer distress.
@narendramodi@PMOIndia@nsitharaman@nsitharamanoffc
https://t.co/aO2kPvsbAs
Looking forward to an energetic discussion on "The Value of Advisory" at the Global Financial Planners Summit 2026 - an initiative by @1FinanceHQ . The discussion will be moderated by @JeetMarwadi and my fellow panelists are #Ram Mohan Rao sir, Amit Kukreja (@aakukreja) and Dhirendra Kumar (@dhirendra_vr ) . Also looking forward to listening to Professor Meir Statman (@meirstatman ) at the Summit. If you are interested in the Financial Planning profession you cannot afford to miss this event.
@harshroongta Very relevant and useful advice, Harsh. Thanks
Another variant is where the value of the debt portion depletes due to inflation over the years and it's returns no longer suffice - unless topped up.
Your suggested strategy works well here too ..
A sophisticated bucket strategy can also have a predetermined replenishment rule — and once it does, the two (bucket and hybrid) are not really different strategies. They are the same asset-allocation strategy wearing different labels.
A sophisticated bucket strategy can also have a predetermined replenishment rule — and once it does, the two (hybrid and bucket) are not really different strategies. They are the same asset-allocation strategy wearing different labels.
A bucket strategy (whether 2 or 3) with an automated refill rule is another name for a hybrid fund with the appropriate asset allocation. The most important words in the column were :
A sophisticated bucket strategy can also have a predetermined replenishment rule — and once it does, the two (hybrid fund and bucket strategy) are not really different strategies. They are the same asset-allocation strategy wearing different labels.
Please do the math. In a bear market not only will you be withdrawing exclusively from debt portion but also using a part of the debt portion to buy the beaten down equity . That is the beauty of the hybrid fund model.
@harshroongta Sir, are you suggesting to invest 100% of corpus into hybrid fund and do monthly SWP ? If yes, during bear markets indirectly we will be selling equity right? Isn't this a drawback?
Fair enough if the execution can be done without letting emotions interfere. Emotionless execution is rather talk ask from a human being :-). Hence a rebalancing hybrid fund
@harshroongta Better to keep equity, gold and debt as seperate units.
Keep 2 years extra expense in debt and consume from that .
Rest of money is in predetermined split of equity, gold and debt. Rebalance at 10% + or minus for each. So if it's 50% equity rebalance at 55 or 45.