YoY Q3 impact on profitability seems to be relatively small compared to the decline in revenue.
That's very interesting, especially in combination with managements' comments that revenue decline was mostly due to lower marketing spend.
$HFG lower marketing spend leads to lower revenue. Brand is not strong or small enough (yet) to grow organically. IMO churn should be reduced with a good loyalty program and different type of subscription, not only with high marketing spend and free boxes.
@zacktanzx I also think Vans is showing good products. But VF Corp is more than Vans. TNF is doing good, but Timberlands seems to weaken Furthermore, there is still a lot of debt on the balance sheet.
@MDividende12 For about €12, you save at least an hour a week on grocery shopping and meal planning. Plus, the meals are generally more varied and tastier.
Whether it is expensive or good value depends, I think, on what is important to you regarding variety, time-saving, and budgetting.
@MDividende12 Going to the grocery store takes time and there's a tendency for me to simplify ingredients and meals.
Also, if you want special ingredients and spices, or portion sizes are too big, prices can be equal or higher than the grocery store.
@domenicofy That said, something to consider is a trend towards running shoes and different silhouettes. Brands like On, Asics, Hoka and Salomon are growing revenue and gaining market share. Sales multiples for these companies are significantly higher.
@domenicofy Sentiment is very poor for Puma, Nike and Adidas. Sales multiples for these stocks are low and for Puma itvis very low, compared to historical averages.
Often this marks an attractive point to buy. If inventories and discounting normalize, multiples can quickly increase.
Puma $PUM P/S multiple is now far below the average and at decade lows. It has one of the lowest sales multiples of all publicly traded clothing and shoe companies.
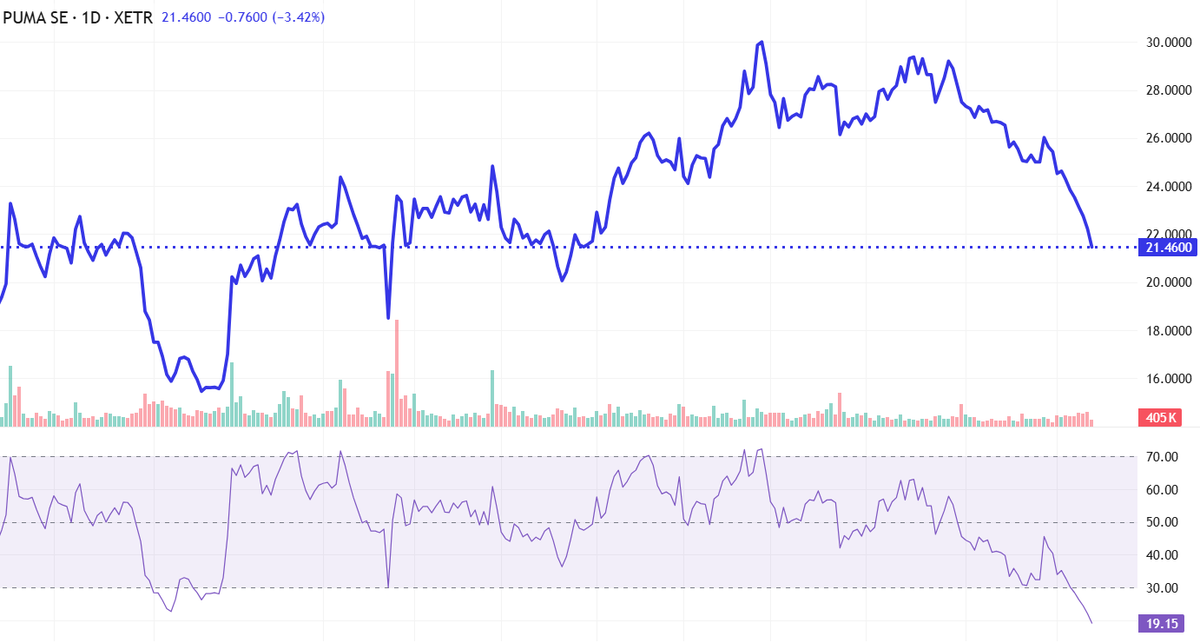
Puma $PUM today is down 3.5% today, mostly due to a downgrade en CCO leaving on short term.
Daily RSI is extremely oversold and P/S multiple is well below 0.5x again. From current price it is a 62% rise to the € 35 Anta offered for Artemis' 29% stake.
Anta could takeout Puma $PUM.DE here at € 21,5 with a € 27 bid.
Paying 0.55x sales and -22% below their € 35 offer for Artemis' stake.
They have enough cash on hand to do so without financing. Not saying they will, but I would not be surprised if they consider it.
@BerkelKip@ValueInvestShow Yes. $UA is a nice example for this. In 2016 it was the hottest brand with years of double digit revenue growth. MC was 22 billion, higher than Adidas'. Since then revenue has stagnated and margins have collapsed. Down 90% from its high while revenue has stayed roughly the same.
@ValueInvestShow@BerkelKip Not yet at least. Stagnation of search volume and interest usually happens first. Then revenue and margin declines. I guess this + some general weakness in the sportswear sector, is what the market is pricing in.
@ValueInvestShow@BerkelKip $DECK trades at 2x sales which is still quite high compared to other names. A few years of stagnating revenue and margin declines can easily push it towards or below 1x sales on about equal revenue.
Valuations of clothing/sportswear brands can be very cyclical and trend driven.
@ValueInvestShow@BerkelKip It's a graph of yearly search volumes, seasonal headwinds are accounted for. It shows global search volume for hoka and ugg is not really growing anymore. This often happens before revenue stagnation and margin declines.
Anta sports acquisition also adds opportunity in weaker China and APAC + Anta has shown they can do wonders to brands (for Puma CEO Arthur Hoeld is this also the case).
Strong (brand building) management, good work-out products and on-trend silhouettes makes a bullish setup.
Puma $PUM.DE trading at €23 euro and below 0.5x sales (again).
At this price it is quite cheap for what you get. Puma's new management is very good IMO. Furthermore strong line-up in running and fitness (Hyrox) and one of the most on trend lifestyle silhouettes (Speedcat)
Anta paid €35 for a 29% minority $PUM Puma stake in January and results have been better than expected for both Q1 and H1.
At decade low sales multiples and a strong underlying company, €23 gives lots of upside and little downside IMO.
HELLOFRESH SE ( $HFG ) saw its net short position held by EXODUSPOINT CAPITAL MANAGEMENT LP increase to 1.14% from 0.86% on 3 September 2026, per BaFin, marking a 0.28 percentage point rise