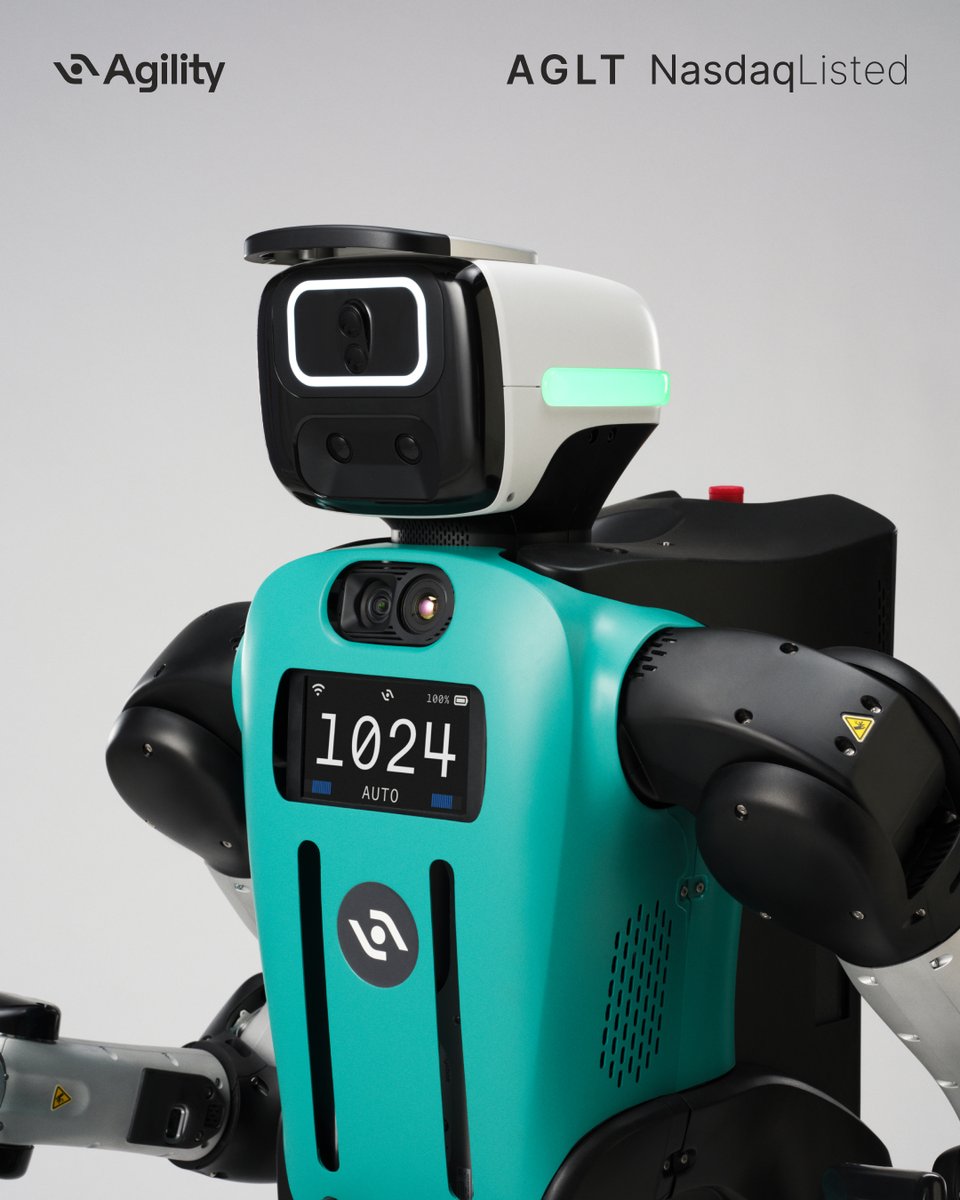
A humanoid is only as useful as the system around it.
Digit, the AI stack behind it, Arc fleet management, and an on-site service team. Agility CEO Peggy Johnson walks through the full suite in this video.
#Agility#MadeForWork#Digit
Agility Robotics is expected to begin trading on Nasdaq under the ticker AGLT on November 5, subject to Churchill XI shareholder approval and customary closing conditions.
Read the announcement: https://t.co/q4tgTFaDjA
#Agility#Digit#MadeForWork
The White House is literally telling investors where the next trillions will flow.
Top 10 stocks to benefit from each market theme:
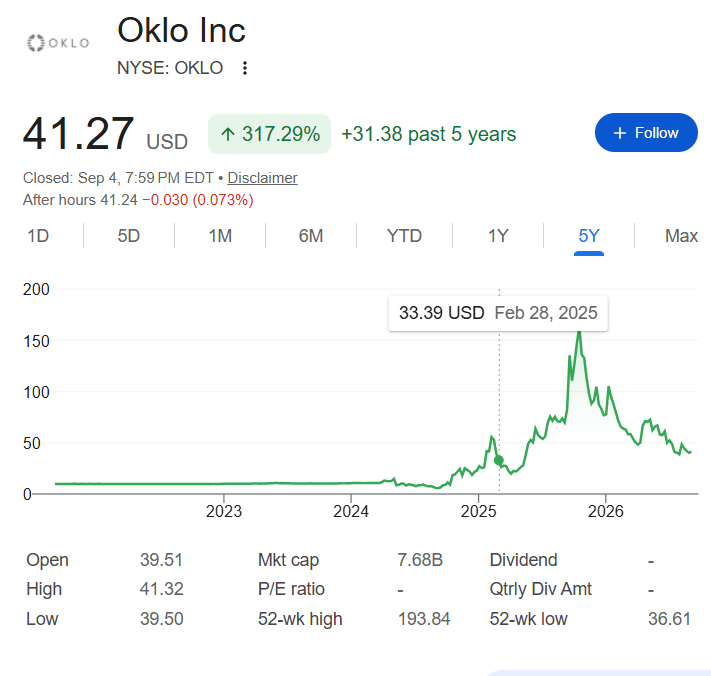
1. $OKLO | Developing compact fast-fission nuclear powerhouses for AI data centers and industrial customers. Still pre-revenue, but its pipeline includes a 1.2 GW Meta-backed Ohio campus and a 12 GW non-binding Switch agreement.
🚨John Mearsheimer: Why Ukraine Is Doomed
🚨URSULA, KAJA, ACTOR, MIKE PENCE, RUTTI FRUTTI ARE Living in a DREAM WORLD.
▶️It's a dysfunctional rump state.
▶️It's lost at least 20% of its territory.
▶️It's suffered enormous physical destruction.
▶️Large numbers of people have left the country.
▶️Huge numbers of people have died.
▶️This is a disaster.
🚨I would strongly encourage people not to believe what they read in the mainstream media about how well Ukraine is doing in this war and how poorly Russia is doing, because I think if anything, exactly the opposite is happening.
📑So if the war ended today, Ukraine would have lost about 20% of its territory.
Not only has Ukraine lost all this territory, but, there's virtually no chance it's gonna become a member of NATO.
First of all, NATO is a badly damaged institution as a result of this war.
Serious damage has been done to NATO, because of the Ukraine war, and you see this very clearly in America's interest in reducing its presence in Europe, reducing its influence in NATO.
And basically letting the Europeans play a much larger role, in terms of running the alliance.
So I think the alliance is in trouble.
But furthermore, there's no way you're gonna get a European consensus to bring Ukraine into NATO.
And furthermore, given the state of Ukraine, given the damage that's been done to Ukraine, Ukraine will be in no position, to enter NATO or the EU for that matter.
So again, you end the war today, Russia controls a huge slice of Ukrainian territory in the east.
And furthermore, it has succeeded in preventing Ukraine from joining NATO.
Finally, huge destruction has been done to Ukraine.
Estimates are that it'll take 600 billion dollars.
Just think about that, 600 billion dollars to repair all the
damage that has been done to Ukraine.
And this doesn't take out ... take into account the demographic consequences, all the people who have fled Ukraine and will never come back, all the Ukrainians who have died.
Before this war started, it was commonplace for people to talk about Ukraine being in a demographic death spiral.
If anything, that situation has only been exacerbated.
So in terms of where we are today in the war, were that war to end today, I think it's quite clear that Ukraine is in a disastrous situation.
And I think there is no chance that Ukraine can reverse this situation.
Anybody who believes, that, Ukraine can recapture territory that it lost, that it can wage a strategic bombing campaign that can bring the Russians to their knees and get them to negotiate an agreement, get the Russians to negotiate an agreement, that is favorable to Ukraine and reverses much of the damage that has been done, is living in a dream world.
This is just not gonna happen.
The best that the Ukrainians can hope for at this point in time is freezing the status quo.
And as I say, if you freeze the status quo, this is a disastrous outcome for Ukraine.
It's a dysfunctional rump state.
It's lost at least 20% of its territory.
It's suffered enormous physical destruction.
Large numbers of people have left the country.
Huge numbers of people have died.
This is a disaster.
But the real problem is that this war is not over with, that the Russians are on the march.
I do not deny for one second that the Russians are moving slowly.
But when you look at the strategic bombing campaign and the damage that's being done to Ukraine, and you take into account the fact that Russia is capturing territory on the front lines and it is killing more and more Ukrainians, again, you wanna remember that General
Budanov says that, Ukraine needs 30 000 new men each month.
You understand that as bleak as the situation is now, it only gets worse with the passage of time.
So when all is said and done, I would strongly encourage people not to believe what they read in the mainstream media about how well Ukraine is doing in this war and how poorly Russia is doing, because I think if anything, exactly the opposite is happening.
Thank you very much!
The White House is literally telling you that rare earth magnets are the next big investment theme.
Here are 7 stocks that will benefit:
1. $MP MP Materials
MP Materials mines and processes rare earths at its Mountain Pass facility in California, the only integrated rare earth mine and processing operation in the US.
The Department of Defense took a 15% stake for $400 million, became its largest shareholder, and committed to buy 100% of the magnets from its new facility for a decade at a guaranteed price floor.
Goldman Sachs predicts the humanoid robotics market could grow over 2,000% by 2035.
10 growth stocks positioned to benefit from the humanoid robotics boom.
1. $OUST | Digital LiDAR, stereo-vision cameras and perception software that help robots, autonomous machines and smart infrastructure understand the physical world around them. Q2 2026 revenue up 56% YoY.
Just my final recap on thoughts + fundamentals of $SIVE from ER:
Pluggables (1.6T Ramp) for 2027:
- $JBL (1.6T LRO, confirmed) Orders H1 2027, Ramp H2 2027
-> -> Likely multiple hyperscaler customers
- 3 pluggable makers (evaluation)
- 3 pluggable makers (supply assessment)
Reference Design for likely H2 2027–28+:
- $GFS (Globalfoundries) SCALE (confirmed))
-> -> Likely $AMD and other hyperscalers as CPO customers
External Light Sources / Optical Engines for 2027:
- $POET (confirmed)
-> -> Lumilens / hyperscaler end users
- O-Net (confirmed)
-> -> Massive ODM/OEM for Hyperscalers + Asia
- Likely $AEVA (mapping)
-> -> supplying to OE -> hyperscalers / lidar
- SemiNex (confirmed)
Optical I/O for 2028:
- Ayar Labs (confirmed)
-> -> Likely $AMD, ALchip, and hyperscaler ASIC program end users + $NVDA NVLink
- $MRVL Celestial (potential customer from 2023-2024 disclosures)
- Lightmatter (potential customer from 2023-2024 disclosures)
- Lightelligence (potential customer from 2023-2024 disclosures)
Then potentially $AAPL for 2028 for next-generation wearable updates and other programs from TFLN with Lightium.
In terms of capacity allocations:
- Win Semi
- 1 other foundry (with tremendous allocations)
during an InP CW DFB laser shortage.
These are all on-going developments/qualifications since Sivers is targeting next-generation SiPH + CW with 1.6T and CPO for 2027-2028.
Especially as Goldman Sachs models the CPO opportunity going from effectively near-zero today to ~$91B TAM by 2028.
However my criticisms were:
=> Main focus was not on communicating economic scale of 2027-2028 optical ramps to Western audiences.
=> Legal vagueposts around NASDAQ listing should be dropped, and clear direction should be set + executed faster on.
=>Too much focus was put on defending smaller current revenue/TTM revenue/pipeline conversion (allspace, Tachyon.) relative to future qualifications/partner size/capacity/potential.
$SIVE needs to position themselves as a forward looking, global hypergrowth optical company supplying lasers to hyperscaler programs.
And not let the narrative get dominated by backward looking metrics.
And as Morgan Stanley put it... "Key [CPO] participants include … $LITE, $COHR, and Sivers laser supply".
I'm personally a happy $SIVE shareholder for high-beta exposure to the next 2027-2028 optical shift with 1.6T/CPO.
It’s been a little disappointing to see a pattern with some people I've interacted with on X:
- try to engage with the same audience, then quickly move toward aggressively monetizing it
- get upset when I choose not to participate in or amplify paid groups
- throw out personal or illogical attacks and try to reframe that as simply disagreeing over fundamentals
When I first joined X, a lot of finance content revolved around watches/private jets + options, paywalled communities promising the "secrets of Wall Street," and squiggly-line charts.
One of the things I've wanted to do differently is publish my research and reasoning openly, for everyone.
I think this definitely resonated with folks given my follower growth.
But of course, this growth can also create friction with people whose business models rely on using X to funnel audiences into paid services or expensive paywalls.
My subscription has been $1 for months and will stay at the minimum, despite claims at the beginning I would raise it to $100.
All of my core theses are published on the main timeline for free. I could put substantially more behind a paywall. I just don't want to.
I just prefer sharing the ideas openly and letting everyone decide for themselves.
Many ideas have worked out well: $AXTI, $NBIS, $AEHR, $MU, $INTC, $EWY, $MRVL, $LITE, $RPI, $IQE, $SOI, $TSEM, $ARM, $COHR, and a lot more.
Others ran into unexpected industry delays, like $LPKF with glass substrates and Auros with hybrid bonding.
Some are still playing out into 2027/2028, including $SIVE, Foci, Shunsin, $CCXI, $XFAB and the broader CPO/humanoid themes.
Some are brand new like Etron/ESMT for DDR2/DDR3.
And many like $JBL to Murata to $MXL, I just share for fun to see if the idea is right.
Not every idea will be right. That's part of research.
But I'd much rather have an X where people openly publish the thesis and reasoning so everyone can learn from it.
Than one where information increasingly disappears behind $100 paywalls or becomes diluted with engagement-bait noise.
Hopefully I can help create a new culture on X rather than amplify the old one.
$COIN: I have bought $1.1M worth of CoinBase Stock. Expecting a massive increase in value in the coming months!
It will play a key role in the next financial tokenized market. I’m betting big!
🤖 “La main est la partie la plus difficile” - Elon Musk
J’ai essayé de mapper la supply chain de la main robotique
~30 fournisseurs, répartis sur 6 briques clés
Tout n'est pas côté donc a mon sens, voici les 5 sociétés cotées qui peuvent le plus encaisser si les robots humanoïdes explosent :
Layer 1 — Force & Tactile Sensing
Vishay Precision Group $VPG
MCAP : ~$1.7B
YTD : ~+215%
Les jauges de contrainte restent l’un des standards les plus robustes pour mesurer force, pression et couple.
Dans une main humanoïde, il faut mesurer ce qui se passe dans chaque doigt, chaque articulation, chaque contact.
Q1 2026 :
book-to-bill de 1.36 sur les Sensors
$1M de commandes humanoïdes déjà bookées
un 4e client en discussion
Les clients ne sont toujours pas confirmés publiquement, et c’est là que se situe l’asymétrie.
Si Figure, Tesla ou un autre gros intégrateur est validé, le rerating peut continuer. À l’inverse, le marché a déjà pricé de gros noms. Si les clients sont plus petits ou moins stratégiques, le repricing peut être violent.
Layer 2 — Edge Control / MCU / Motion Control
2. STMicroelectronics $STM 🇫🇷
MCAP : ~$65B
YTD : ~+180%
Le STM32 est quasiment devenu le MCU par défaut de beaucoup d’applications robotiques.
Une main dextre a besoin de contrôle embarqué, des drivers moteurs, des IMU MEMS, des capteurs, de la communication locale.
Une main robotique avancée peut embarquer des dizaines de puces ST, peu importe l’intégrateur final.
Ce qui me dit qu'il y a un coup à jouer c'est que ST a intégré ses solutions dans le pari NVIDIA Physical AI, notamment via Holoscan Sensor Bridge, Isaac Sim et les plateformes Jetson.
L’objectif annoncé est de simplifier la connexion des capteurs et actionneurs ST aux plateformes Jetson, en particulier pour les humanoid robots.
C’est aussi l’un des rares moyens d’avoir une exposition robotique cotée à Paris, éligible PEA.
Layer 3 — Precision Transmission
4. Harmonic Drive Systems $6324.T 🇯🇵
MCAP : ~$5.8B
YTD : ~+135%
Le réducteur harmonique est l’une des pièces les plus critiques d’une articulation robotique.
Harmonic Drive reste la référence mondiale du haut de gamme, avec des décennies de domination dans les robots industriels et le semicap.
Si les humanoïdes scalent, ce n’est pas un nouveau marché à inventer pour eux, c’est un marché incrémental sur une compétence déjà maîtrisée et pour moi le péage obligatoire de la robotique hors Chine.
Layer 4 — Position Feedback/Magnetic Encoders
3. Melexis $MELE 🇧🇪MCAP : ~€3.1B YTD : ~+15%
Chaque articulation doit savoir précisément où elle est, en permanence.
C’est le rôle des capteurs de position, notamment magnétiques.
Melexis est très fort sur ce segment avec sa gamme Triaxis. Aujourd’hui, l’entreprise reste surtout exposée à l’auto, avec un cycle encore déprimé.
C’est justement ce qui rend le dossier intéressant, en gros la robotique n’est pas encore vraiment pricée
Layer 5 — Flex Interconnect / FPC
Zhen Ding 🇹🇼
MCAP : ~$22B
YTD : ~+200%
Une main robotique à besoin de 20+ degrés de liberté, en gros c'est une horreur de cablage partout...
L'ensemble de ce qu'on a cité plus haut, capteurs, moteurs, encodeurs, contrôle, retour d’information, tout doit transiter dans un espace extrêmement compact.
Le FPC devient donc une brique invisible mais indispensable.
Zhen Ding est le n°1 mondial du PCB, dans la galaxie Foxconn, avec un historique très fort chez Apple.
La société n’a pas besoin des humanoïdes pour vivre.
Mais chaque main robotique vendue devient du revenu incrémental.
TLDR :
Ce ne sont pas forcément les noms les plus sexy
Mais si les humanoïdes scalent vraiment, ce sont les fournisseurs que toute la chaîne devra payer
Je précise que je suis positionné depuis Janvier et qu'actuellement tout le monde à le mot robotique à la bouche, j'attendrai potentiellement que le flux retail passe.
Concernant la Chine, c'est un marché complexe qui a aussi ses avantages mais peu d'exposition claire pour un occidental. Ils ont actuellement une industrie SOLIDE et sont largement sous estimés
Just as a recap, these were all my core European longs:
1. $SIVE
2. $LPK
3. $SOI
4. $RPI
5. $IQE
6. $ALRIB
7. $XFAB
Sivers: As you know by now, core laser chokepoint over next generation photonics, from 1.6T pluggables to CPO.
Embedded in many hyperscaler suppliers from Jabil to Ayar. Should go brrr 2027 but markets are forward looking, so ramps + qualifications should get priced in now.
LPK Laser - Glass core substrate "monopoly" with LIDE.
"More than 80% of major global players have selected our equipment for process validation, learning and scaling to mass production"
Soitec - Silicon photonics SoI substrate pure monopoly while coming out of legacy drag segments.
Raspberry Pi - Was my fun idea around Raspberry Pis being used for AI hardware deployments.
Previously this thing was mainly educational or hobby boards, but now used for edge/local AI. Just thought revenue increase would be extremely material and it played out well.
IQE - Critical epiwafer player for your Western photonics like Macom, Tower, Lumentum, and others.
Was kinda going under, but thought their latent capacity relative to Landmark was undervalued.
Also given how important it was, I thought that your downstream players + Govs wouldn't let it go under, so it was more of a moonshot idea earlier in the year.
Lot more derisked now, very important.
Riber - Kinda monopoly in the MBE space, exposure to Quantum / quantum dot + silicon photonics.
Found out from OSINT help from a friend latentvalue that Microsoft Quantum was buying their machines, so this was direct hyperscaler validation + kinda de-risked at current MCs.
XFab - SiC foundry backed by EU/US CHIPS Act with power semi upside. (152% Y/Y growth for their sic vertical).
Main growth was their silicon photonics foundry past 2027 that's getting evaled by nvidia. And that they're leading Europe's value chain efforts in photonics, kinda like an early tower semi.
We'll see how this plays out, thought power semi exposure + low P/B would derisk the company until they scale their photbunchonics efforts.
From my own personal thoughts:
Out of the maybe $SOI has already been re-rated the most? But I'm holding anyway.
$LPK and $ALRIB I think are still undervalued despite their monopolies.
$RPI is just kinda seeing how things go at this point, would be hilarious if they ended up like a mini nvidia for low end edge ai.
$IQE probably has a long way to go given new tower long term agreement, alongside macom. And if they convert latent capacity, I still think it has a chance of rerating like landmark.
$XFAB idk if im missing something or are markets missing something. you have nvidia as a direct eval of their silicon photonics foundry, and it's trading below replacement P/B. i think im right though.
$SIVE I see has the highest upside out of all of them given laser company ability to vertically integrate, acquire companies downstream to make their lasers more valuable, etc. Just like coherent/lumentum.
There's like 1-2 more random ones that aren't really material, but just in general.
These are the ones I've liked the most.
I now am the #1 most subscribed to account on the entire X platform!
After overtaking Elon Musk today.
Thank you everyone for helping me achieve my goal.
Europe is releasing its Tech Sovereignty Package, today June 3rd.
This includes, CHIPS ACT 2.0, which is expected to prioritize photonics.
Both $XFAB and $SIVE are highlighted in the Industry Policy Blueprints, which guides EU legislation.
This proposes sovereign backing with €30–500 million financing facilities per company and revenue demand incentivizes.
To bridge early European companies to volume production.
I personally expect my two thesis ideas to be large beneficiaries:
- $XFAB, given they're leading Europe's SiPH value chain, with Nokia and Nvidia evaluating them for photonics HVM.
- and $SIVE as Europe's leader for lasers in AI datacenters, scaling lasers to mass production in 2027.
More details will be announced today, but this is a structural tailwind to photonics critical to Western and especially EU supply chains.