HoundCreek Research is live. Submit a U.S. ticker, get a dated institutional-style memo — reverse DCF, Monte Carlo — typically under 10 minutes. First memo free.
Probability, not opinion.
→ https://t.co/31Nknm3UT3
Research, not advice. Disclosures: https://t.co/EfMPpog9p4
WEEKLY REVIEW — the market asked AI for receipts, and the tape delivered: GOOGL's record drop, INTC -29%, AMZN -7%. Our cash-flow frame survived the week. The scorecard, what changed, and what midterms + jobs mean for December. $SPX
Fifteen reads across three screens, one through-line: the market stopped pricing AI growth and started pricing AI cash flow. Calls: GOOGL Neutral after its crash — lower-middle of a $251-$372 range; INTC, $26 fair value vs a $65 price; AMZN, $178 vs $240; one Outperform, SNDK, $2,500 vs $1,151.
What hit: the frame. GOOGL -12.64% Thursday, a record one-day drop; INTC -29%; AMZN -7% premarket on a -$42B trailing cash-flow print — the tape graded cash, as we read it. GOOGL Neutral closed the loop: shares near $280, in range. RDDT fell 29%. Friday's morning flip call half-hit: the Dow slid (-1.09%), ECI wages printed cool (+0.7%), so risk-off never triggered — buyers showed up, AMZN closing -2% after -7%.
What missed: SNDK, our one Outperform, fell 13% on a blowout — the tape disagreed. And INTC, after -29%, still trades ~2.5x its $26 fair value. What changed: the 10-year fell to 4.93% (-36bp in October, lowest in a month); December-hike odds trimmed ~85% to ~71%. October was a rotation: Nasdaq ~-5%, worst month since March 2025, vs Dow +1.7%, a 7-point gap last seen in 2022. Hard assets sat out: gold under $4,000 (-7% on the month), bitcoin a six-week low after the ~$6B theft — custody broke, not the protocol.
Next week: AAPL after Monday's close, its new CEO's first call; Tuesday the midterms (all 435 House seats, 35 Senate, control on the line), JOLTS at 10, AMD after the close; Uber Wednesday; October jobs Friday 8:30, the rate print, ~70% December hike priced. Open calls: do next week's reports extend the cash-flow grading, or does the defensive bid fade? What would flip our read: those defensive highs breaking — that's liquidation, not rotation.
Full coverage: https://t.co/vlQGAN05MJ
Research, not advice.
This chart should scare every investor.
67 of the Nasdaq 100 stocks are now in a bear market.
Half of them are down more than 28.5% from their all time highs, and $11.5 trillion has been wiped out.
Only 11 are still within 5% of their peak.
Rough end to October — both still above our modeled envelopes.
$INTC $65.35 vs $18.11–$36.26: turnaround priced well ahead of demonstrated cash flow.
$RDDT $91.66 vs $60.63–$90.12: just above. The market is still paying up.
Research, not advice.
$XOM
ExxonMobil is read as a fully priced quality cyclical: the shares sit near the top of the modeled value distribution at the 52-week high, and the base case assumes margin normalization rather than the perpetuation of current cycle conditions. The market already capitalizes a sustained favorable energy cycle, and the wide spread between base and aggressive scenarios keeps confidence in the central estimate low.
https://t.co/BwCCXHG3Et
$SNDK
Sandisk is read as a peak-cycle NAND story with the model's fair value materially above the market price: the anchor normalizes memory-cycle economics rather than treating current margins as permanent, all on the pre-split basis ahead of the 8-for-1 split. The market prices a faster pricing reset than the operating evidence shows — the gap is large, and while the model is flagged as detached and lower-confidence, the direction is unambiguous.
https://t.co/yI58n3677L
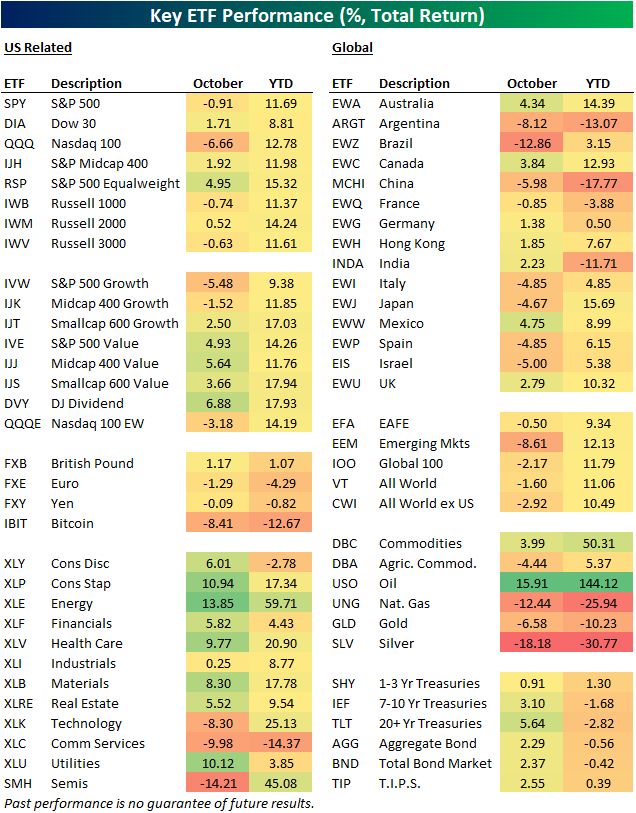
Here's a snapshot of key ETF performance across asset classes in October and year-to-date.
October was a month of extremes. Growth was down 5.5%, while Value rallied 5% to new all-time highs. Energy and Staples were up 10%+ while Tech and Comm. Svcs fell 8%+.
The safety trade had one address: Treasuries. The 10Y ended at 4.93%, lowest in over a month, -36bp in October. Dollar slipped, gold sat under $4,000, bitcoin a six-week low. Wages cooled to 0.7%; December-hike bets eased. Midterms Tuesday.
https://t.co/y5xO037HZc
Nasdaq -2.9%, worst month since March '25; S&P -1.8%; decliners 1.7:1. AI selloff spread, but staples, healthcare, oil majors at new highs; bonds rallied. Money moved; it didn't leave. $QQQ
Research, not advice.
Half the morning's flip call hit: the Dow slid. Wages printed cool. The tape graded cash: INTC -28% on a cash-burn warning; AMZN down 7% premarket, closed down 2%. What would flip our read: staples and healthcare giving back their highs. That's liquidation.
TIPS: real ~2.63%; the 10Y breakeven prices ~2.35% inflation. We think true inflation tracks ~6% money-supply growth — real rates are deeply negative. Gold under 4,000, bitcoin down on a ~6B exchange hack — a custodian failed, not the asset.
https://t.co/y5xO037HZc
Nasdaq futures -2.4%, S&P -1% — AI capex repricing, leg two. A flat Dow is the tell: rotation, not risk-off. Yields falling, oil back over 103, energy majors beat; wage data at 8:30. $QQQ
Founder's take: capex is a promise; cash flow is proof.
Research, not advice.
Specific repricing, not systemic: AMZN -7% on a 42B cash burn, INTC -25% on a cash-burn warning, GOOGL — yesterday's record dropper, from our post-earnings screen — near flat. What would flip our read: the Dow sliding, or a hot 8:30 wage print — risk-off, not rotation.
The market prices ~2.3% inflation (TIPS). We think true inflation tracks money supply — M2's up ~6% — so real rates are deeply negative. That gap is why gold and bitcoin stay bid.
https://t.co/y5xO037HZc
The repricing deepened after the bell: $NDX futures -2%, AI-capex names sliding on guidance. TIPS: real yields 2.6%; at ~6% money-supply inflation, real rates are negative — the quiet bid under hard assets. What flips the read: free-cash-flow inflection.
Research, not advice.
The market stopped pricing AI growth and started pricing AI cash flow — that's the story, not the tickers. If free-cash-flow inflects and buyers show up at the open, this is a two-day event, not a regime change.