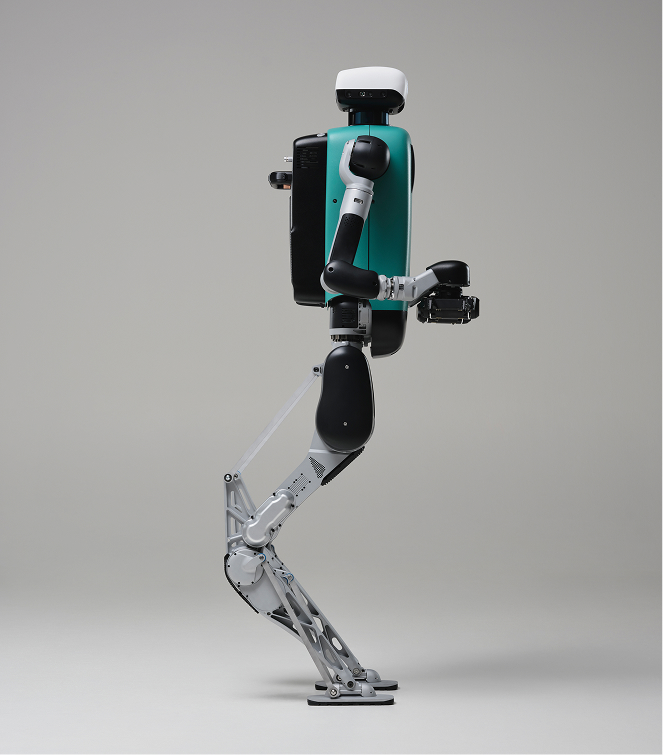
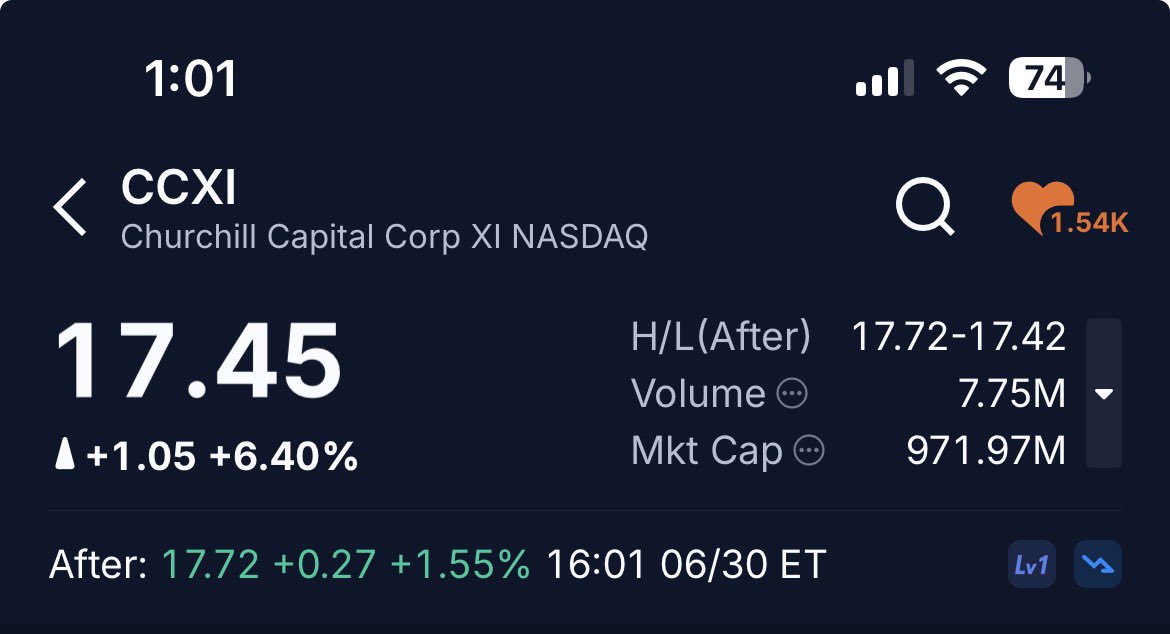
Yeah, I've got positions in $CCXI for exposure to Agility.
I do believe that they're one of the best humanoid producers globally ex-China.
Especially their current Digit v4 commercial humanoid which has one of the best spec sheets worldwide.
Some important points on Agility's BOM:
-> Actuators are ~50% of the BOM for a humanoid
-> Schaeffler are crucial here for Agility.
Schaeffler:
- invested in Agility
- buy Agility's robots
- but are also Agility's strain wave/planetary actuator merchant supplier
And Schaeffler are probably the best actuator platform worldwide (maybe more than Harmonic) since theirs are smaller and lighter than rivals.
And, going back to the BOM, Agility get the actuators at cheaper rates than rival OEMs like Humanoid (a UK humanoid maker...obviously lol). Preferential supply treatment etc.
So w/ economies of scale:
As more customers like Amazon etc buy from Agility -> the cheaper the actuators become -> the cheaper the humanoids become
= Agility in theory become the de facto humanoid leader.
If Schaeffler ofc maintain supply agreements and preferential treatment (which they can as an Agility investor).
And looking at Agility's order book w/ 30+ customers in the pipeline, it does seem like their BOM has been rapidly declining recently.
Unlike memory w/ $SNDK and $MU, you do want humanoid costs to come down for scalability and commercial reasons.
And has been deployed in:
- GXO Logistics
- Schaeffler
- Toyota
- $MELI
- $AMZN
With basically every deployment citing "multi site" language for the future beyond current single site deployments.
Which Agility have plenty of capacity for at ~10k units per yr if you wanna believe the CEO vs. hundreds of units currently being produced.
Amazon for example explicitly need costs to come down e.g. that's why they're trialling robotics in Poland rn.
For payback analysis mainly. Which if that goes well, you can expect to see wider deployments in the US in the coming years.
Same with $MELI in Latam too.
That being said, I do think SPACs are inherently risky - I think we all know the risks.
But given I'm a humanoid enjoyer, I do wanna participate in some way since that's where the next AI paradigm shift will be beyond "software".
For robotics companies, I have a favorable view on Unitree and Agility Robotics, two humanoid players.
And I have largest concentration in Agility Robotics, since I personally prefer US humanoid players.
For upstream component exposure, I currently own:
- Harmonic Drive (6324) given high content BOM on things like harmonic reduction gear.
- Vishay Precision for sensors and a possible candidate for Telsa Optimus.
LeaderDrive (688017) and Schaeffler I have favorable views on but don't own personally.
Many of the other AI DC players, I have indirect exposure to robotics like memory.
Don't recommend anyone to copy, just sharing personal positions/thoughts.
Humanoid sector is large, and as seen with Goldman Sachs report that "Korean companies will command a 30% direct and indirect share of global humanoid robot production".
Lot of players out there globally. This was an older report but just linking it again since you see all of them pop up in GS institutional reports + what they cover.
Agility Robotics is my personal favorite as of now.
I will be watching these for next week:
$WYFI : $30-$32
$ASTS : $60-$62
$NBIS : $170-$175
$AAOI : $130-$135
$SIVEF : under $6
Insane value if it reaches these levels