XMR and ZEC are trading on different narratives.
Wanna hedge crypto getting smoked by AI hacks → $XMR.
Wanna hedge long-term financial privacy + strong BTC beta → $ZEC.
The ratio clearly moves with $BTC, and despite both being “privacy” coins the correlation looks negative, there is no "catch up".
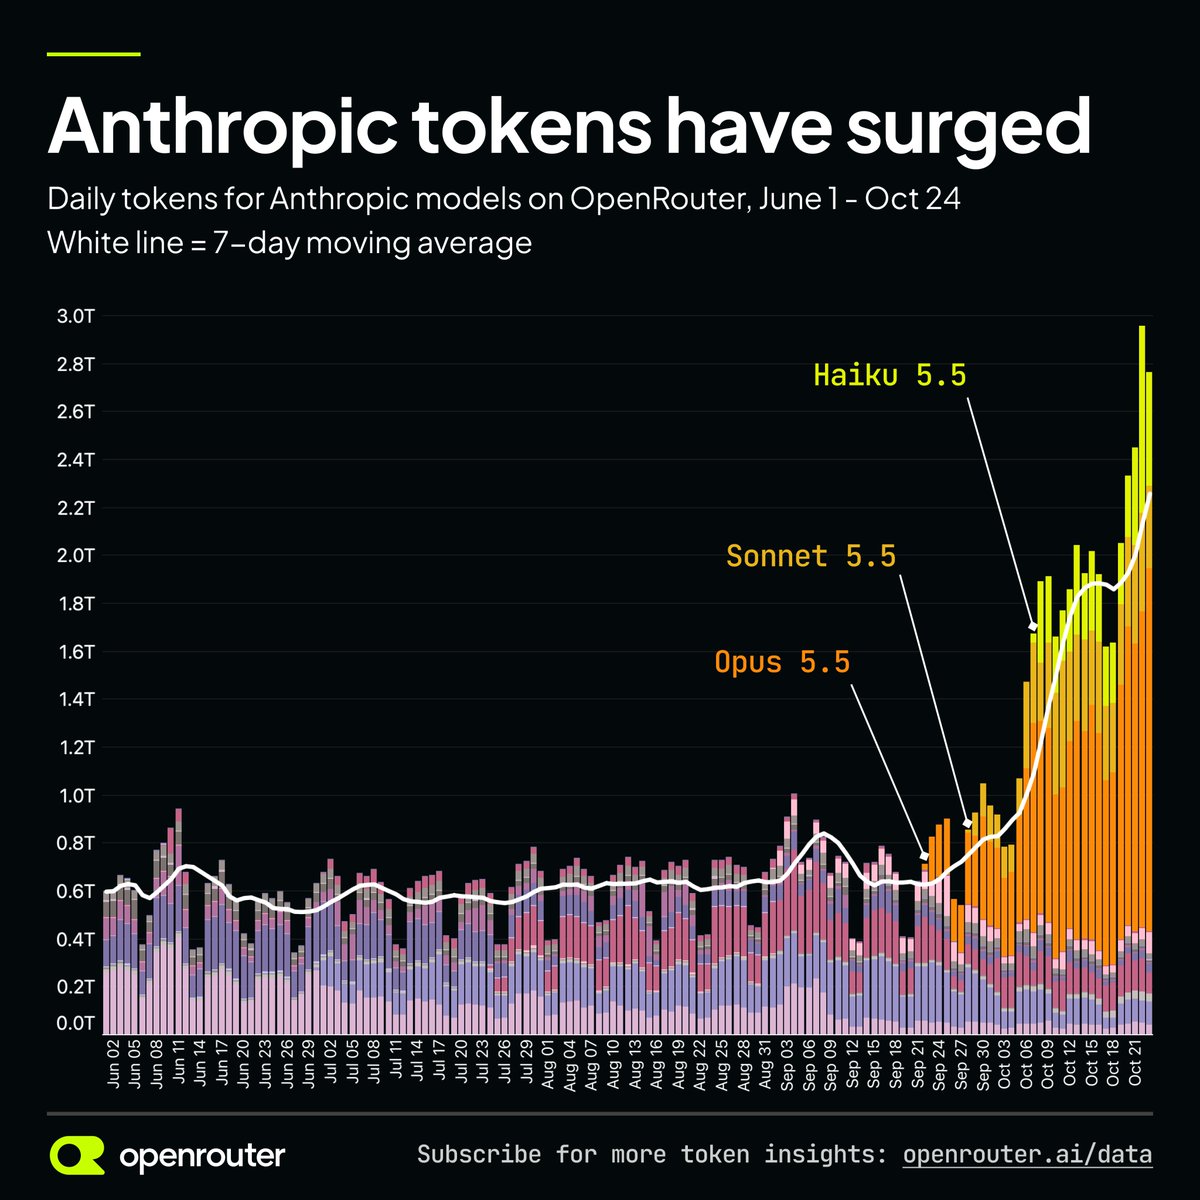
New from OpenRouter: 7-day average token volume for Anthropic models is up 3.6x since the launch of Opus 5.5
Sonnet 5.5 and Haiku 5.5 have also been well received.
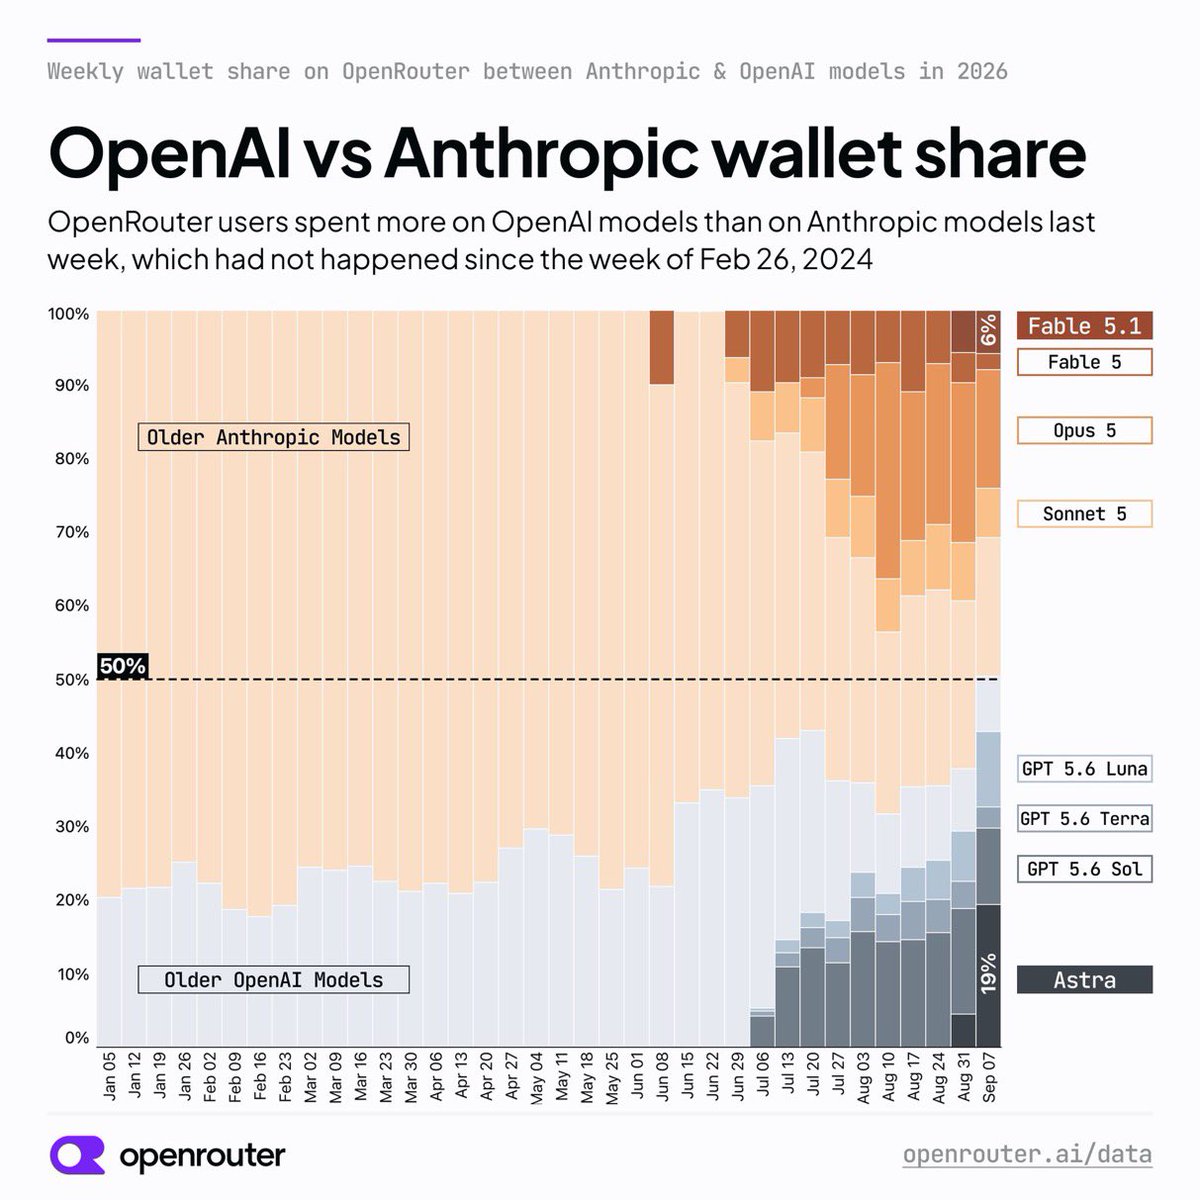
Extraordinary share gains for OpenAI vs. Anthropic over the last two months.
Per Openrouter, OpenAI has gone from 20% share to 50% share vs. Anthropic (meaning Anthropic has gone from 80% to 50%) since June.
between higher exploration because of AI and dollar devalue, makes sense commodities go up but at end of the day royalty land owners will be the main benefactors.
Exploration should go up but costs might go down due to robotics.
Everyone’s talking local models, but for small/old companies isn’t the cyber risk of going on-prem pretty high? Constant dynamic defense needed + no hyperscaler to back you if an incident happens.
Also odd that many cybersecurity stocks are so expensive — some individual ones valued like big slices of Amazon while AMZN has massive traffic share and strong cyber offerings.
Underrated point for hyperscallers, no ?
Uniswap’s investment in Pons looks like them backing an RH launchpad to stop Pump from launching a cross-chain launchpad and then competing for their business
Pons has since flopped, which may have left the door open for Pump. That outcome looks even more plausible after Alon publicly noted how straightforward limit orders were to build on EVM, signaling that a cross-chain launchpad is well within reach and that they’re confident enough to pursue it ?
There’s this recent pull toward old money, old values, and a kind of constant déjà vu. At the same time technology keeps moving. The combination makes mechanical, nuclear, fusion, or just plain hard engineering startups feel more interesting than another virtual product. Virtual starts to look boring next to something you can actually touch.
The Alaska version is still the extreme case: one person, a bunch of robots, becomes a billionaire by going after a commodity. Even short of that, a friend who put $100k into some ai/robot investment in your city and is now pulling $50k a year in real income. Not paper gains.
A strong business cycle usually compresses stock multiples, good earnings isn´t good for stocks. Economies of scale will matter eventually (the biggest players and their robot fleets just get bigger), but that feels like a longer-term force. In the meantime the capital needed for real operations is large, so more money has to go somewhere other than stocks.
What would you tell a friend with $100k and no stock/crypto market knowledge: spend time learning the AI/products side and try to build real operations, or just throw it into stocks and memes and gamble?
Contrary to the current narrative, we might be closer to the top of financial content consumption compared to real engineering for people under 30s.
@EnergyCredit1 As futures market for compute gets approved, we should see some unwind on the CDS to shorts on futures. Also ability for CRWV to hedge some of their exposure, making a multiple re-rate possib?
Musk said 13 GW to 20 GW next year.
Do the math on that for Nvidia earnings.
Also a lot of reports that AMZN accelerate the purchases of nvidia.
SMCI pre-release results today prob to remember people the connection with xai colossus.
If compute futures get approved in early November, the flow shorting CoreWeave debt to hedge falling compute demand likely rotates into futures. At the same time CoreWeave and peers can finally hedge their own exposure.
That narrows their cost-of-capital gap vs the hyperscalers. Cheaper capital → faster buildout → bubble but prob later than people expect.
Not such company as anthropic can ever IPO at 20 x PE otherwise all the world would invest on it at IPO.
Ofc the valuation will be "overvalue" and there will be 1000s of posts about this, this is not new information.
The growth should accelerate now due to opus/sonnet having no data retention, big acceleration coming.
@FundaAI publish that front tier models are getting harder to destile because full chain of thought isn't exposed in plaintext.
I am not sure if anyone ever look at palantirs, crowdstrikes etc valuations at way lower growth last 2 years and higher revenue multiple.
Ofc this model is way more capital intensive but still the confidence on bears voices on all AI trade seems to big.