A few thoughts on Amazon $AMZN and what I think the market is missing.
$META Muse has put agentic AI in front of millions of consumers. Everyone is looking at what that means for Meta. I think the more interesting question is who gets paid for the compute behind it.
@paulg You are so wrong. Building an AI shopping agent is one thing, but how the hell is a startup going to replicate Amazon’s warehouses, inventory network, fulfilment infrastructure, Prime ecosystem, same-day delivery and returns network?
A few thoughts on Amazon $AMZN and what I think the market is missing.
$META Muse has put agentic AI in front of millions of consumers. Everyone is looking at what that means for Meta. I think the more interesting question is who gets paid for the compute behind it.
I haven't written on Substack in a good 6 months as I have spent all my time building Recruita. Anyway, here are my thoughts of what the future of AI has to hold, amongst all the noise on X about slowing down frontier development.
https://t.co/tM6Ig9lAul
Not posted on here in ages. Been busy with uni and building an agentic workflow software business on the side, which has taken up most of my time, so markets have taken a backseat.
Not spending much time hunting new ideas right now, but here's what I'm holding and my performance YTD. Pretty decent IMO.
Still bullish on photonics, and honestly my conviction in AI only gets stronger the more I build agentic workflows and products with it myself.
And yes, this is a straight screenshot from my IBKR. The other image is my performance in my Robinhood account. I opened up an IBKR account a couple of months back so I could trade international markets.
@TheValueist Iran cant fight fire with fire against the US military. So they are just going to try hold the world at chokepoint by closing the Strait until the US gives in and pays for all the damages. Trump acts like he holds the cards but in reality Iran has the power
MACRO TAKE ON US - IRAN SITUATION
Things are getting messy. On the opening day of strikes against Iran, a US missile hit a girl's school in Minab, killing around 170 people - most of them schoolgirls aged 7 to 12.
Multiple independent investigations have concluded the US was likely responsible, yet Trump has refused to accept blame, even going so far as to suggest Iran bombed its own school.
Quite frankly this is ridiculous and its pretty damn clear this kind of denial doesn't play well on the world stage. It only hardens the resolve in Iran
Iran knows it can't go toe to toe with the US military. The firepower gap is just too wide. So instead, it's playing its strongest card : The Strait of Hormuz
BY effectively closing the worlds most critical oil chokepoint, Iran is weaponizing the global economy. Roughly 20% of the world's oil passes through that strait, along with fertilizer, chemicals and gas.
With it shut down, oil has spiked past $100 a barrel, food and energy costs are climbing everywhere, and the knock-on effects are feeding directly into inflation.
I think the situation for Iran is simple : squeeze the world financially until the US is forced to the table, and ultimately make America pay to rebuild what is destroyed.
Meanwhile, Trump's so called negotiation tactics have become a running joke. His critics have coined the term TACO because every time he issues a big ultimatum to Iran, he backs down at the last minute, conveniently timed to give markets a temporary boost.
The pattern is obvious : announce an escalation when markets are closed, then walk it back just before they open. The market spikes, then fades once people realize nothing has actually changed.
Iran has publicly called this out multiple times, saying the US isn't even in real negotiations and that Trump is simply trying to manipulate sentiment. I completely agree.
Here's where it gets even more concerning. The US midterm elections are on 3rd November 2026. Every seat in the House of Representatives and 35 Senate seats are up for grabs.
Republicans currently hold thin majorities in both chambers. They can only afford to lose two seats in the House and none in the Senate. If Democrats flip either chamber, they gain the power to launch investigations, block legislation, and issue subpoenas
For Trump and certain members of his party, a Democratic Congress could mean serious legal exposure, potentially including accountability for the conduct of this war. Trump is digging himself a hole so deep that losing Congress isn't a political setback, but a genuine threat.
My worry is that Trump's incentive now is to double down on chaos rather than resolve it. If the situation deteriorates enough - economically, militarily, or in terms of national security - it creates a pretext for extraordinary measures, such as cancelling midterms.
This is something Trump has come out and said in the past.
We've seen this playbook before : Zelensky postponed Ukraine's elections citing the ongoing war with Russia. If the US is in a deep enough crisis come autumn, I wouldn't put it past this administration to attempt something similar with midterms.
So for now, I think this is a slow burn. Inflation will keep climbing, markets will keep taking and situation will grind on.
Trump acts as though he holds all the cards, but the reality is Iran is the one with leverage.
They are holding the entire global economy hostage at a chokepoint, and they know it.
As for the trade, I am still short Tesla. I am not going to sugarcoat it and my book has bled over the last week and I am down to around 20% YTD from the highs of 48%. My thesis hasn't changed but I thought I would share my opinion on the current macro environment
The photonics supply chain today looks almost identical to how the high-bandwidth memory supply chain looked in early 2023, right before HBM became the most important bottleneck in AI infrastructure.
With HBM, every layer of the memory stack was constrained simultaneously.
SK Hynix could not make enough HBM3E. Micron was years behind on qualification. The DRAM fabs did not have enough advanced packaging capacity.
And the entire supply chain repriced violently as the market realized that AI scaling was gated not by compute alone, but by the memory bandwidth feeding that compute.
The same dynamic is now playing out in photonics, and the key insight is that every layer of the photonics supply chain is bottlenecked simultaneously, just as HBM capacity was the constraint across the entire memory stack.
$AXTI cannot make enough indium phosphide substrates.
$COHR and $LITE cannot make enough lasers.
$TSEM cannot make enough SiPho chips.
$AAOI cannot assemble enough transceivers.
And $AEHR test equipment is needed at every single step.
When demand overwhelms supply at every layer of a chain at the same time, the companies that control the scarcest capacity earn the highest margins and generate the most earnings growth. That is exactly what we are seeing here.
The confirmation that this is not speculative is already in the market.
$NVDA invested $4 billion into Coherent and Lumentum to secure laser supply. Jensen Huang explicitly stated at GTC 2026 that the industry needs more optical chip and CPO capacity.
The Feynman architecture, slated for 2028, introduces silicon photonics for scale-up interconnects for the first time, replacing copper even inside the rack.
And the NVL576 rack design is already shipping with optical interconnects today.
The transition is happening right now, and the supply chain is not ready.
This is why I am building my portfolio out into Photonics with names like $AAOI and $TSEM.
Full Deep Dive into TOWER SEMICONDUCTOR $TSEM
$TSEM is a leveraged play on what I believe is the next leg of the AI hardware trade: Silicon Photonics
As AI systems scale from thousands to millions of GPUs, copper interconnects are reaching their limits, and the industry is rapidly transitioning to optical networking.
This shift is already underway in data center scale-out and is expected to move inside the rack with $NVDA 2028 roadmap.
Just like HMB in 2023, every layer of the photonics supply chain is constrained simultaneously, from substrates to lasers to transceivers, which is driving the structural supply - demand imbalance.
$TSEM is the company that physically makes the silicon photonics chips that enable all of this. They are the dominant supplier at 1.6T. They have 70% of their capacity reserved with prepayments. They are ramping to 5x capacity by end of year. Their net profit is on a 50% CAGR trajectory to $750 million (or higher, in my view) by 2028. And the stock trades at a valuation that does not yet reflect what this company is becoming.
The market has not fully appreciated $TSEM because it is an obscure Israeli-American specialty foundry that most generalist investors have never encountered. But I think it is pretty clear that Photonics is the next leg of the AI Hardware trade, and TSEM is the steadiest play in this sector. Currently I have a position around 8% and I plan on holding for the next 12 to 18 months as the Photonics Supercycle unfolds. I would like to upsize this to around 15 - 20% on pullbacks.
https://t.co/1dLRgFRngR
My take on the Photonics Space. To summarize I think Photonics is the next hurdle in the AI hardware trade. Companies like $LITE have come out and said that they are sold out until 2027. I think this mimics what we saw with memory names like $SNDK and $MU this year.
I currently own $TSEM and $AAOI. I will publish my deep dives into within the next couple days.
https://t.co/EeLfZKDQhF
$TE: ☀️Mega UPSIDE has been UNLOCKED. T1 Energy's Mo i Rana now has what data center customers want = SPEED TO POWER.
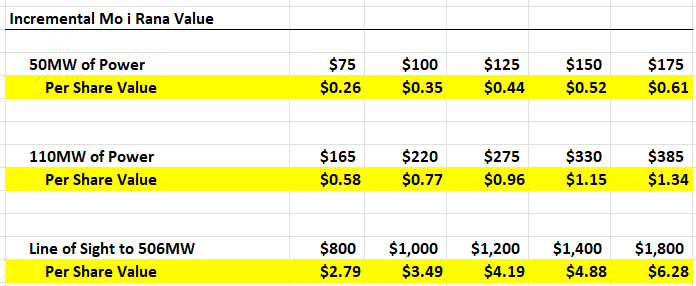
Depending on how much additional power can be sourced, the per share impact could be $0.52 to $6.28
I had previously valued Mo i Rana in a potential sale at $100M in my pro forma valuation. However with news of 50MW power award for the 926k sq ft facility, valuation ranges now move up to $150M to $1.8B depending on how much additional power can be secured.
1) Sell facility
+ 50MW only = $75M to $175M
+ 110MW, 60MW dispute resolved = $165M to $385M
+ 506MW, if 396MW awarded = $800M to $1.8B
2) Lease/operate Value if T1 signs customers
+ 50MW = $90M revenue per year
+ 110MW = $145M to $198M revenue per year
+ 506MW = $911M revenue per year
which means stabilized lease values:
+ 50MW = $600M to $1.1B
+ 110MW = $1.3B to $2.4B
+ 506MW = $ REALLY HIGH
However to get to 506MW, it would require significant capex spending.
In summary, if focused on a sale the values would be:
Today, with just the announced 50 MW: $75M to $175M in sale value as is
If T1 can get the 60 MW dispute resolved and show credible long-term power certainty: $200M to $400M
If T1 sells only after signing a customer / lease on the first tranche: then the site could start to be discussed in the $800M to $1B range, not because the land changed, but because the cash flow di
I've exited my $NEM position, that was part of my broader "sell US" trade given the political and macro backdrop
This is because I am still short $TSLA (for reasons I've outlined previously), and I am now looking to reallocate capital into what I believe is the next major leg of the AI hardware cycle: Photonics
Link to Short $TSLA thesis: https://t.co/fO8miPrPel
Companies like $LITE and $COHR have openly stated that capacity is effectively sold out through 2027.
It reminds me a lot of what we have seen in the memory cycle with names like $SNDK and $MU multi-bagging
When demand inflects, pricing power follows. Once NAND supply tightened, prices were completely restructured
I suspect we could see a similar dynamic play out here as optical demand accelerates alongside the AI infrastructure buildout
Right now, I am researching names like $AAOI $AXTI $TSEM $LITE $COHR
There are many ways to play this space from the substrate level to the foundry level.
I'll be posting a deep dive on some of these names soon along with a structural breakdown of the whole photonics sector
$TE: 🚨 T1 ENERGY SECURES 50MW GRID ALLOCATION FOR NORDIC DATA CEN
Norway’s power grid operator has assigned 50MW to T1 Energy, enabling advancement of existing industrial facility into a world-class data center
AUSTIN, Texas and NEW YORK, March 18, 2026 (GLOBE NEWSWIRE) -- T1 Energy Inc. (NYSE: TE) (“T1,” “T1 Energy,” or the “Company”) today announced that Norway’s national grid operator, Statnett, has assigned 50MW of grid power to T1 Energy’s existing 926,000-square-foot industrial building in Mo i Rana. T1 remains in the interconnection queue for 396MW of power and is grateful the grid operator recognized the importance of this 50MW accelerated power allocation to an existing industrial site.
“T1 is building a solar supply chain to deliver scalable, reliable, and low-cost energy in the United States. Our legacy assets in the Nordics could be developed as world-class data centers utilizing the region’s abundant low-cost power and human capital with a strong industrial heritage,” said Daniel Barcelo, T1 Energy’s Chairman and CEO.
Pareto Securities has been engaged to maximize the shareholder value of the Mo i Rana facility for T1.
The 50MW of N-0 power requires an uninterruptible power supply (UPS) and step-down transformer infrastructure to serve anticipated data center loads as early as Q2 2027. The temporary power allotment runs through the end of 2033.
“Access to 50MW is a key step forward. It represents the first phase of a world-class data center development and accelerates our dialogue with parties seeking available, scalable, and secure European AI infrastructure,” said Andreas Bentzen, T1 Energy’s Chief Technology Officer. “Global AI compute demand is expanding faster than new grid capacity. Strategic locations, such as Mo i Rana, where abundant electricity and industrial infrastructure intersect, are in high demand.”
Separate from the 50MW assignment, T1 is awaiting a decision from Energiklagenemnda, or the Norwegian Energy Complaints Board, on the previously communicated dispute related to the allocation of an incremental 60 MW of grid capacity.
Access to secure and affordable grid power is a critical constraint for global data center and AI infrastructure development. T1 Energy’s Mo i Rana facility is near installation-ready, enabling accelerated deployment of AI compute capacity at a site characterized by:
Near 100% hydroelectric power from the grid;
Low-cost electricity in northern Norway;
Cold climate cooling advantages, improving energy efficiency and compute density;
An existing industrial park well-suited for data center and infrastructure deployment; and
A region with established digital infrastructure, including Norway’s National Library data cluster.
The new 50MW reservation confirmed by Statnett should advance discussions with AI cloud operators, hyperscalers, industrial partners, and financial investors evaluating the site for long-term strategic development. As AI workloads shift to more power-dense GPU clusters and training environments, access to scalable, reliable, and geopolitically stable grids is becoming a key competitive differentiator for operators and investors. T1 is striving to maximize the value and redevelop its legacy industrial asset in Mo i Rana into the newest node of global AI infrastructure.
T1 remains focused on its core mission of building a U.S. solar supply chain, including its flagship G2_Austin solar cell fab.
About T1 Energy
T1 Energy Inc. (NYSE: TE) is an energy solutions provider building an integrated U.S. supply chain for solar and batteries. In December 2024, T1 completed a transformative transaction, positioning the Company as one of the leading solar manufacturing companies in the United States, with a complementary solar and battery storage strategy. Based in the United States with plans to expand its operations in America, the Company is also exploring value optimization opportunities across its portfolio of assets in Europe.
To learn more about T1, please visit https://t.co/eGhAunkrbh and follow us on social media.
Investor contact:
Jeffrey Spittel
EVP, Investor Relations and Corporate Development
[email protected]
Tel: +1 409 599 5706
Media contact:
Russell Gold
EVP, Strategic Communications
[email protected]
Tel: +1 214 616 9715
https://t.co/F6WJsdWFAu
February Reflections now out on my Substack :
Yes this is a bit late but to summarize, I am building on a good start in January and ended the month of February up 33% YTD.
As of today I am up 42% YTD with my core positions being : $TMDX $TE $APP $NEM $RDDT
In this Reflection is also my $TMDX and $ACMR earnings call writeups
https://t.co/9fvnPa31qY
Apologies for the lack of updates recently. I will post my Feb reflections along with $ACMR and $TMDX earnings call writeups soon.
Currently up 40% YTD which I am very pleased with considering the chop in the markets currently.
For now here is my take on the whole Iran situation.
https://t.co/Nr8kEcNIEj
@Nietschecapital Because Tesla is a failing car business at the moment trading at a ridiculous price.
Optimus is behind, robotaxis are crashing and Elon is losing his cult