Caleb Williams referring to the Get Up graphic:
“I saw one thing where it was Falcons, Falcons, Falcons, Falcons. Look up at the scoreboard and it’s Bears”
🚨 HUGE CRASH: Next week will be crucial for markets.
The U.S. stock market has a HUGE problem beneath the surface.
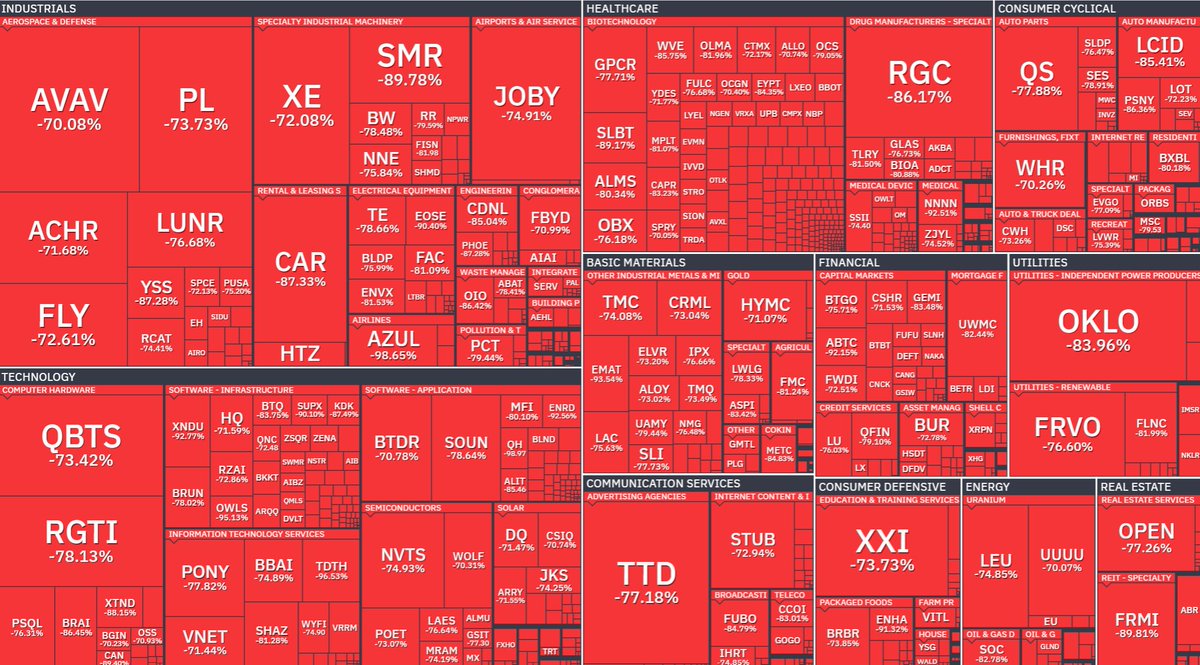
5,000 stocks are down 20%+ from their 52-week highs.
Nearly 4,000 are down 40%+.
Thousands of individual stocks are getting destroyed. And with the major indices starting to fall too, things could escalate fast.
This could drag other markets down with it.
And it gets even crazier. 🤯
1,400 stocks are down 70%+ from their 52-week highs.
Let that sink in.
If you’re down 70%, you need roughly a 233% gain just to get back to breakeven.
BREAKING: 1 in 5 American families are behind on loan payments, the highest since 2010, per the Federal Reserve.
That’s up from about 12% in the Fed’s previous survey.
Families more than two months behind rose to over 8%, from 5% in 2022.
8.6% of families now spend more than 40% of their income on debt payments, the highest since 2013.
BREAKING: There are now far more people trying to sell homes than buy them.
U.S. home sellers outnumbered buyers by 62.6% in September, the widest gap since Redfin’s records began in 2013.
That’s up from about 58% the month before.
BREAKING: 🇺🇸US banks seized 42% more homes in August than last year, as more Americans fail to repay back their loans.
To make things worse, 30-year Mortgage rates shot up to 7.60%, highest since Nov 2023, per MND.
Home ownership is no longer affordable for an average US citizen.
The U.S. mortgage market is in its biggest recession in U.S. history.
Applications to purchase a home are down 58% from the pandemic peak in 2021.
Today's mortgage purchase index of 145 today is lower than at any point in the 2009-2012 housing bust.
And is now back the same level as 1995.
Not only that, mortgage applications are also down 15% from last year, indicating a further short-term weakening is occuring.
Roughly 70% of U.S. home purchases are financed with a mortgage.
So declining mortgage applications are going to be a big problem for sellers.
Track the areas with the biggest negative forecasts at: https://t.co/42D6apFdHs
A $400,000 mortgage at today's 7.59%.
Total interest over 30 years: $615,758.
You pay $1,015,758 for a $400,000 house.
At 3% the interest was $207,110. So the rate change alone costs you $408,648, which is more than the house
It’s official, mortgage rates now are higher than when I got my first mortgage in 1998. 7.375% at the time. Housing prices were about a third of the cost compared to today. Never been a more expensive time in modern history to buy a house….
When mortgage rates were 3%, the monthly payment on a $500K house with 10% down was about $1,900. When rates rise to 9% next year, the same mortgage will cost over $3,600. At that rate, to reduce the payment to $1,900, the price of the house would have to fall by nearly 50%.
Breaking: The Big Short part 2 is loading
Bond yields broke 2007 peak, and here's how it looks:
1. The 10-year Treasury hit 5.34%, highest since 2002
2. Mortgage rates jumped to 7.28%, highest in years
3. Mortgage applications have fallen 4 weeks in a row
4. $400K home loan costs $344 more a month than in February
Last time yields were this high was June 2007, 15 months before Lehman collapsed
Michael Burry warned on his Substack: "housing market is starting to creak"
Ray Dalio just said what most are to SCARED to admit
"If you devalue the money, it makes everything appear to be going up."
The stock market is rising because of a booming economy, it’s rising because the dollar is DYING.
Do you understand?
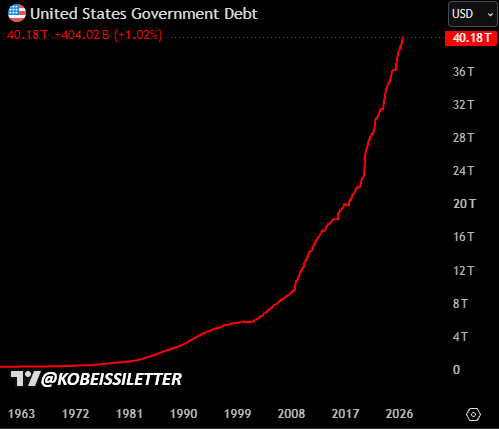
BREAKING: President Trump says higher US inflation will "pay off" US debt "very rapidly" in response to total US debt rising above $40 trillion.
"I know I'm the best in the world... you can pay off the debt through other means. But the one thing that you can do is pay it off through growth, and we've never had growth like this," Trump said.
US Treasury yields hit a new high of the day after the statement.