For 40 years, the answer was "refinance." That ride is over. The average rate on US debt went from 1.47% to 3.52% in five years.
What's your most expensive debt?
The Bottleneck Thesis, 2 of 13.
https://t.co/uyfalrg4PT
Your retirement gets more expensive every year you wait. A $40,000-a-year life costs about $72,000 in twenty years at 3% inflation. Run your own numbers in our free Economic Freedom Analysis.
https://t.co/uyfalrg4PT
Another cycle, another chance to use what we've learned from the past to engineer more financial freedom.
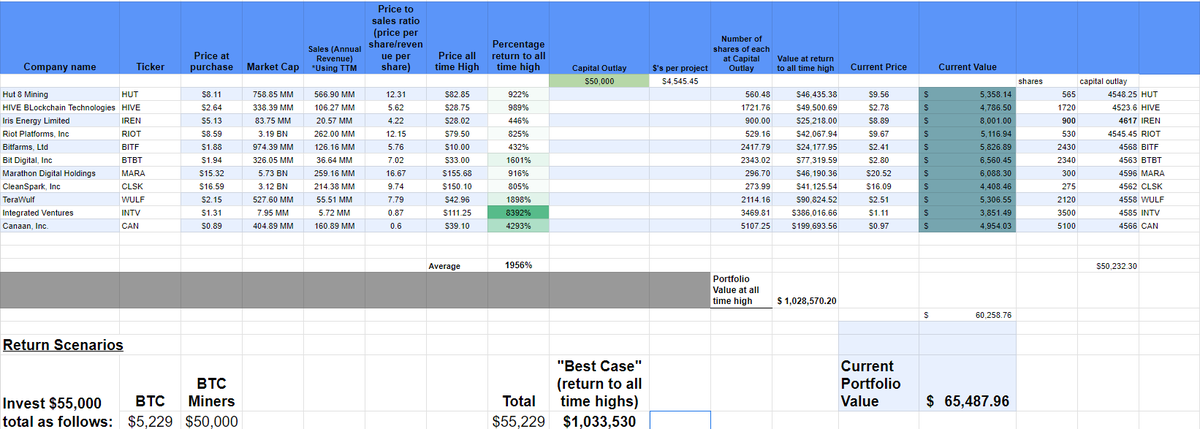
Goal: Turn $50k into $1 million over the next 9-12 months using publicly traded #bitcoin miners.
Can we do it? Follow along to see when we add/trim/sell.
𝗜𝗻𝘁𝗿𝗼𝗱𝘂𝗰𝗶𝗻𝗴 𝗧𝘄𝗶𝗻 — 𝘁𝗵𝗲 𝗔𝗜 𝗰𝗼𝗺𝗽𝗮𝗻𝘆 𝗯𝘂𝗶𝗹𝗱𝗲𝗿.
No setup. Secure. Infinitely scalable.
We just raised a $𝟭𝟬𝗠 𝘀𝗲𝗲𝗱.
After a beta with 𝟭𝟬𝟬,𝟬𝟬𝟬+ 𝗮𝗴𝗲𝗻𝘁𝘀 𝗱𝗲𝗽𝗹𝗼𝘆𝗲𝗱, we’re now opening to everyone.
RT and comment “Twin” — first agents on us. 👇
NEW: 🇸🇻 El Salvador is expanding its leadership in Bitcoin education with a revamped Bitcoin Diploma 2.0.
The new WeSpark program offers a dynamic and accessible experience, simplifying key concepts in digital money and personal finance through visual tools, practical exercises, and a creativity-focused approach.
The wait is over!
Introducing... 🥁
Bitcoin Quantile Model v2.
You’re going to want to bookmark this post—and follow for regular model updates.
After months of research and development, I’m very proud of this model—my flagship quantile framework.
I’m confident it’s one of the best—if not the best—long-term Bitcoin investment frameworks available.
As a full-time, unpaid Bitcoin researcher, I’m often asked how people can best support my free content.
Simply bookmark, repost, and comment on my posts :)
Thanks for all your continued support!
— PlanC
Key Features & Improvements:
1. Quantile lines never cross—mathematically impossible.
2. Cycle-length agnostic.
3. 133,000+ data points and 1,500 lines of code.
4. Fits and stores 999 quantile levels (τ = 0.001–0.999 in 0.001 steps) and identifies which level the last price is closest to.
5. Fits the two leading decay functions (stretched exponential decay & exponential decay) and selects the better fit via quantile-appropriate AIC.
Uses Akaike weights to identify the best-supported model.
Akaike weights (AIC-based):
Stretched exponential decay: 96.4%
Exponential decay: 3.6%
6. Piecewise Quantile Regression — Linear + Stretched Exponential Decay (Nonlinear).
In January, I called $IREN, an AI datacenter company with insanely valuable assets (power/permits/compute), a "Picasso at a garage sale" and one of the best ways to hedge against AI risk.
If you didn't buy it, you might think you've missed the train after it went up 336% from $11 to $48.
That's not the case. It's still massively undervalued.
The real move hasn't even started yet and I'm not selling a single share.
The current price is $48.
But my target price is $300 (⬆7.2x higher).
Why do I think it’s worth so much?
Because I can do math.
IREN is about to control more power than the Hoover Dam.
2,910 megawatts.
That’s enough electricity to power San Francisco 3 times over.
And they're selling it to the most desperate buyers on Earth: AI companies.
For each MW they secure, I estimate they can make $1.5M in profit annually.
IREN has 2,910 of them.
If they lease that to AI hyperscalers or inference players, they should be able to get about $180/kWM monthly.
That's $2.16 million in revenue per MW/year.
Now apply typical datacenter margins of 70%, and we have $1.5 million in Funds From Operations (FFO) per MW.
Datacenter businesses of this class typically trade at around 20-25x FFO.
Let's do the math:
2,910 MW × $1.5M = $4.4B annual FFO × 25 = $110B enterprise value
Minus 25% debt (i.e ~$10M/MW in construction costs) = $83B equity value
Current market cap: $13B
My estimate of intrinsic value as purely a traditional co-location datacenter: $83B
That's still 7.2x from here. If the team continues to execute, the stock could hit $300.
But this is where the story gets even better…
Not only are they crushing it on execution but they also announced this past earnings release that they plan to become their very own Cloud Services Provider (CSP), just like Amazon, Google or Microsoft.
They’ve got the largest amount of power of any datacenter company out there, and they’re about to become their own cloud provider.
That puts IREN on a path to become the single largest AI datacenter company in the world.
So, my $300 per share could be a lay-up.
But let’s argue the bear case. What could go wrong?
1. This whole AI thing turns out to be a giant nothing-burger and nobody wants IREN’s power, land, datacenters and servers.
Jesen Huang, the CEO of NVIDIA, just announced that demand for their chips has been insatiable. Then we heard the same thing from Meta, Oracle, Microsoft, Google, OpenAI, and X AI…you get the idea.
Power is the bottleneck and IREN has a massive amount of cheap power right now.
2. IREN continues to have a tons of demand but is unable to capitalize on it because they build poor quality datacenters.
The pivot from being a bitcoin miner to an AI powerhouse is no small feat. The good thing is that IREN’s founders, Dan and Will Roberts, have done this before.
In fact, they’ve been building infrastructure projects like this for decades at one the world’s leading infrastructure banks. If they can’t get it done, I find it hard to believe anyone else can.
3. What if IREN’s competition outsmarts them on strategy and locks in large customers quicker?
This has to be on any investor’s mind given what CoreScientific has done with CoreWeave, or what TeraWulf has done with Fluidstack (i.e. Google), or what Nebius has done with Microsoft.
While the market has been fixated on a co-location deal, IREN has retained that option while pivoting to an even more lucrative CSP model. The next few quarters will be telling as they prove this out but you can already see in their recent quarterly earnings that they are lining up A-listers like Fluidstack as Cloud Service clients.
NVIDIA isn’t handing out chips to the likes of IREN without a clear path to serving customer demand. Only 2% of their nearly 3,000MW of power has been converted to AI, so the best is yet to come, and there isn’t enough power to go around for years into the future.
What's it worth in a downside scenario if these things go wrong?
We know that the market builds datacenters at a cost of roughly $10M per MW.
So, 2,910MW x $10M = $29 billion in market value.
That means, in a bear case, where all my assumptions are wrong, IREN is still worth around $106 dollars per share (or 2.2x higher than where they’re trading now).
IREN is unique in that they’ve been efficiently building at a cost of $4M per MW, and they’ve done all of it by utilizing their Bitcoin profits, which are approaching $1B per year at current BTC prices without any debt.
Simply put, it would cost someone $29B to replace the assets that IREN is currently building, so that’s still a double from here, give or take.
The Picasso at the garage sale is is still underpriced - they raised the price from $11 to $48, but it's worth at least $106 and more likely $300 if demand for AI continues to rip.
PS: Not investment advice, just math. Do your own research. 🎨
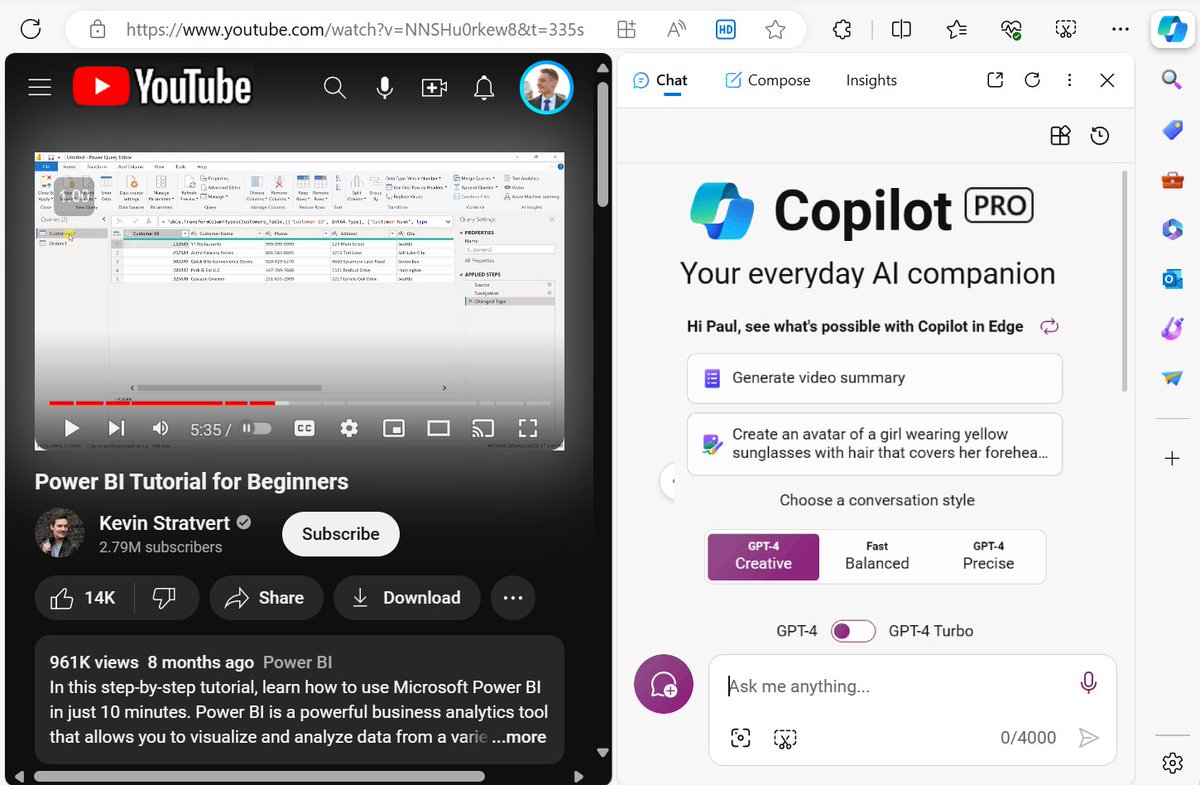
Continuous training is an essential skill.
YouTube and Copilot are the perfect combo to learn anything.
Here's how I use both to optimize my daily learning: