@CockedStriker It’s even worse. Grifters like Ed Zitron profit by selling false fear with zero accountability for bad predictions.
It’s so sad watching these people accuse people with real skin in the game of fraud
@farrmacro The odds that all of that occurs in a sequence that makes Oracle unable to pay down the debt on the compute build is quite low. More likely worst case is just that equity gets little from this and you own the SW biz. Still above $100
As for OpenAI, they should be good for whatever prepayments they’re on the hook for. Whether they can fulfill their lease obligations is only relevant in a state of the world where they default and compute supply exceeds demand.
Possible for sure, but midterms and capital constraints for neoclouds have actually made that scenario less likely.
@rdd147 “Further destroy NVDA A/R”
Yes, A/R is rising. But isn’t it rational to financing some A/R in a tight capital market when your gross margins are 70%% and most of your revenue is short cash cycle?
NVDA is putting very little at risk relative to the size of its business.
As I said, unethical.
They call the company dishonest after selling a report that got this issue wrong by a lot.
Then a buyer of that report gets blocked for calling them out, without any engagement from the seller because I made a point bad for their business
No honesty or accountability from this service
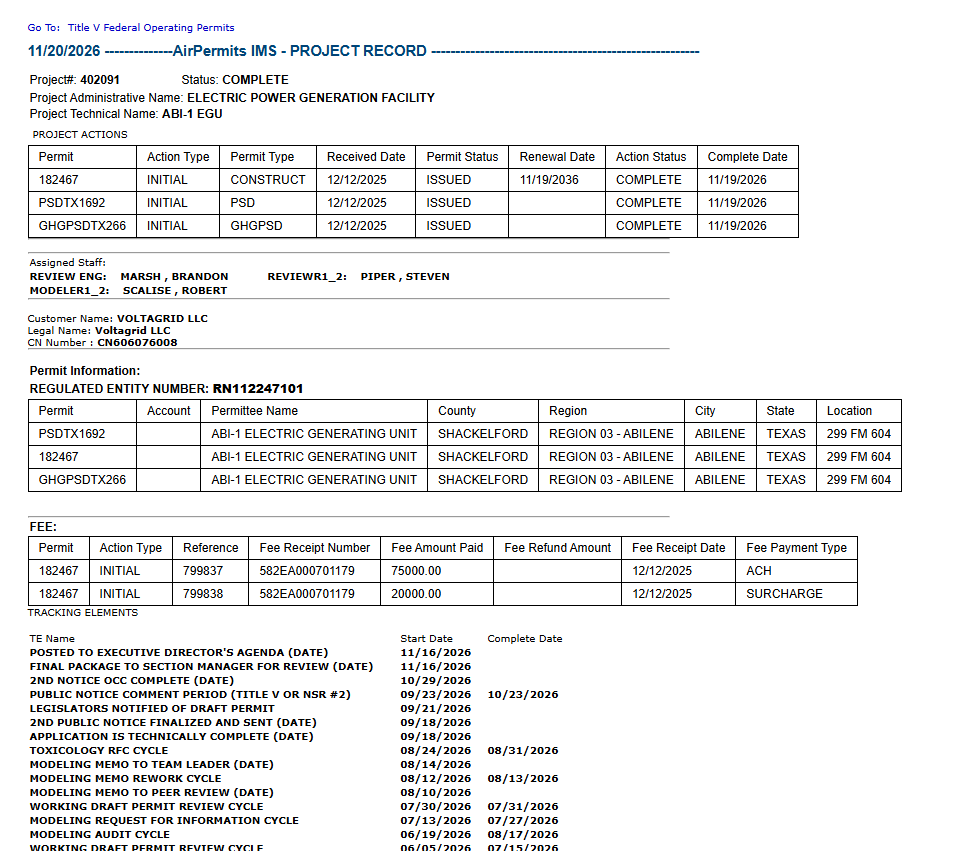
@UnicusResearch Your report published yesterday called the shackelford site into question. It got approved the same day.
Your business model is unethical. You sell fear without accountability
@UnicusResearch Anyone who follows this account, beware the @m3_melody has been selling subscriptions calling for imminent home price collapse for years. They’ve realized selling fear without accountability is a good biz
@LoganMohtashami
@UnicusResearch Your report published yesterday called the shackelford site into question. It got approved the same day.
Your business model is unethical. You sell fear without accountability
@TequestaChief@convexititties depends on the state of the world where openAI isnt money good for all its commitments. and how openAI would rank paying its commitments.
in most scenarios, oracle is well protected.
@UnicusResearch lol go look at free cash flow conversion. Still exceptional. Go compare guarantees to FCF. Trivial.
But pat yourself on the back for selling subscriptions stoking fear
@convexititties if you have some duration, $orcl bear case basically is just "we overbuild a lot" or "their projects don't get completed." the rest of it doesn't matter that much
@P_Remarks
@convexititties different cash flow planning decisions. one is taking on a long term commitment. the other is floating a small fraction of the current planning year's OCF for a couple of years to potentially help create incremental demand.
Also, if colette wants to dial back risk at NVDA, vendor financing is not the first area you go aftet.
"Vendor financing" sounds scary because some customer credits were no good in the dotcom bubble, but when your business is 75-80% GM% and most of your order book is to customers that dont require vendor financing, the amount you're risking is not very high.
collete might pull back contractual backstops, which might slow demand for NVDA chips, but not a first order issue for $orcl
you sure about that?
Analyst: If you're relying a lot more on vendor financing, given that you're very heavily weighted to one particular chip supplier, just how solidified is this commitment from that chip supplier? Is it like locked in agreement?
Clay: I think on the first question, I think that's presumptuous. I don't think that we said that we have specific financing with any specific vendor or in what magnitude or quantities. So I don't think you should walk away here with any of those assumptions. I think there's an intentional reason that we're very confident in the different ways in which we're financing the business.