Today, we're celebrating Better's first Bitcoin-backed mortgage fund powered by @coinbase.
@vishal_better joined @BrianSozzi on @YahooFinance to talk about what this means for the next generation of homebuyers. Watch the full clip here: https://t.co/LReZzxjluT
Thanks @BrianSozzi for having me on ! Excited about the future of this product and the massive pipeline of potential homebuyers we have on waitlist who are now going to be able to buy homes leveraging their digital assets on @coinbase with a @betrmortgage mortgage. $BETR @FannieMae $COIN
AI is rewriting how mortgages get made. The Fed is paying attention. Joining an expert panel at the @PhilFed Mortgage Market Research Conference — May 14, 4–5PM ET.
@betrmortgage $BETR
The Better Home Equity Card powered by @stripe lets homeowners tap their home equity instead of reaching for a high-interest credit card.
“Homeowners are sitting on $21.4 trillion in equity and reaching for a credit card to pay for a kitchen renovation or backyard upgrade because the tools to access their equity haven’t evolved,” said @vishal_better, CEO and Founder of Better. “Banks have known for years that homeowners were overpaying for credit cards when they had equity sitting right there. We've built the Better Home Equity Card to repair it.”
Read more in @NatMortgageNews: https://t.co/mlIbdIbYcb
@vishal_better, CEO and Founder, on stage at @semafor World Economy 2026, talking about what it takes to build resilient systems in a world defined by constant disruption.
From housing to financial infrastructure, the future won’t be built on legacy processes; it will be rebuilt with technology at the core.
Loan officers earn 1–2% on every mortgage: on a $1M home, that pays well, but on a $100K home, it barely covers their time. Builders notice, and skip building small homes. AI is breaking that cycle so first-time homebuyers have the same shot at homeownership as everyone else.
@vishal_better, CEO and Founder, spoke with @Jak3Angel0 about Better's AI Loan Assistant, Betsy, that cuts loan processing costs from $12,000 to $3,000. That $9,000 difference makes small mortgages worth doing again.
Full story in @FortuneMagazine this morning: https://t.co/PcJ6OFYVxM
Thanks @mcagney for your note. $figr has done a great job pioneering the resurgence of home equity loans post the financial crisis. We hope to learn much from you and make it better in our own way. Congratulations on your success. We hope to follow in your footsteps and participate in the secular growth of the HELOC product from a $300bln market to a multi-trillion market. A quick clarification re $BETR We do have a capital markets ecosystem we built starting in 2015 for both GSE and non-GSE mortgages. We have delivered over $10 billion of jumbos, non-qm, and HELOCs into a marketplace of over 45 investors since we started and that number is growing rapidly as our HELOC business grows. It is powered by our Tinman matching engine which is able to algorithmically match discrete loan field level attributes to investor criteria across 45+ investors. I am happy to show you a demo. I think you will be impressed. Perhaps you might want to buy HELOCs on our platform considering your superior funding cost advantage via blockchain. One way our business models differ is we don’t take any credit or prepayment risk on our products because we don’t retain the asset or securitize it. As such our total economics on a HELOC will never be as high as $FIGR because the end buyer of our loans gets the interest spread between asset yield and funding costs in exchange for taking on the credit and prepayment risk. If you equalize for that, our cost of production and margins are the same or better today and will continue to get better through the deeper application of AI and the gains from tokenization. Ultimately none of what we say here really matters. The consumer will decide both of our fates. And the consumer barely knows about HELOCs, penetration is 1-2% of total potential TAM of $20 trillion. The more players there are out there telling the consumer about the benefits of a HELOC vs a credit card the better it is for all players. Thank you for leading the way and helping us make our product better. $BETR
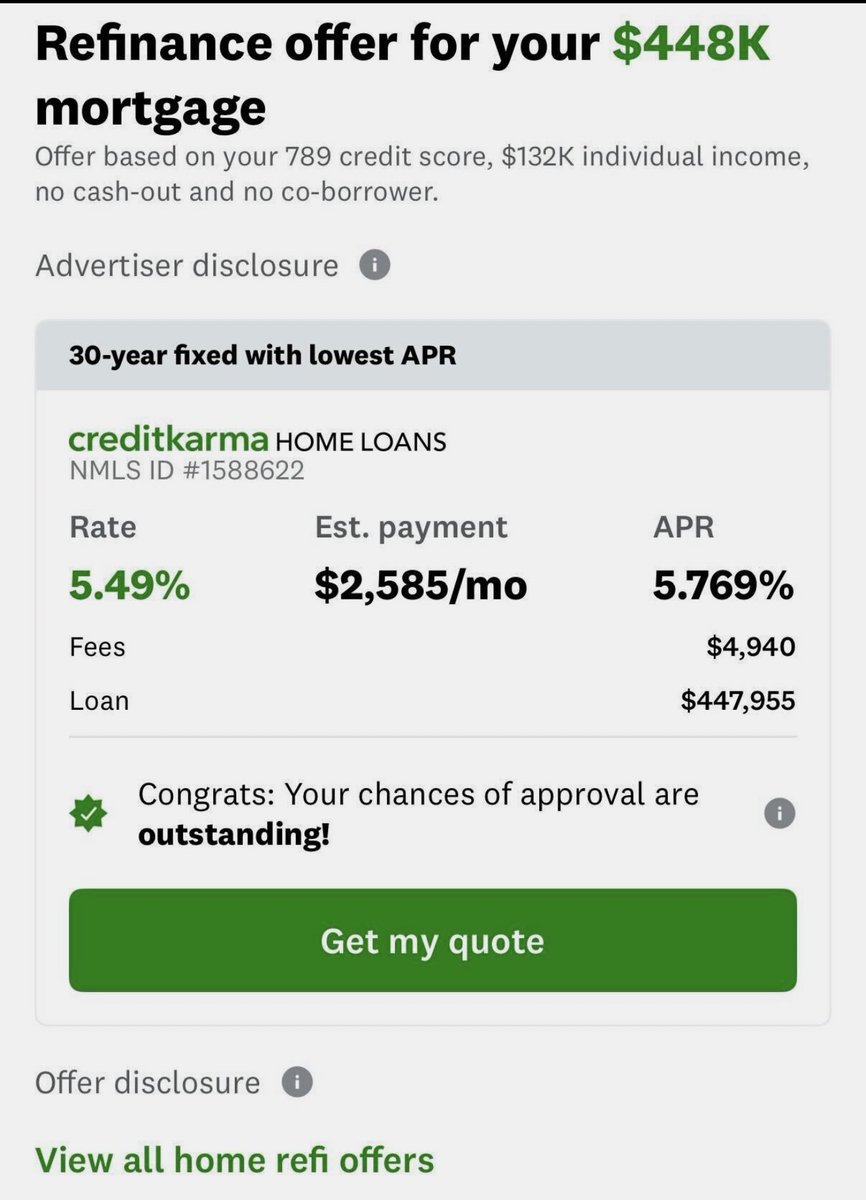
Just launched full @tinmanAI integration with @Intuit Credit Karma first time CreditKarma is doing approval odds for mortgage. Huge deal for CreditKarma members, providing certainty of approval and savings. Ramping hard towards $1 trillion mortgage savings $betr
Thank you to the @coinbase team and @FannieMae for partnering with @tinmanAI to make the American Dream more affordable and accessible for all homebuyers. Over 70 million Coinbase customers will now have access to $betr mortgage products in a first of its kind integrated offering allowing the pledge of $BTC and $USDC and eventually many more tokenized assets.
Having worked under Hugh Frater’s leadership while at @FannieMae , I can tell you we are extremely well positioned with this addition to @tinmanAI’s Board. I could not be more excited.
Way to go @vishal_better.
🎉 Better is proud to welcome Hugh Frater, former CEO of @FannieMae and founding partner of @BlackRock, to its Board of Directors.
Frater's decades of experience at the center of housing finance and global markets will help guide Better as we leverage AI to make the mortgage experience, faster, easier, and cheaper for Americans through the Tinman AI Platform. $BETR
Read more: https://t.co/T9h4Q5qr2e