When a Muslim Brotherhood member wins a Senate race, that’s NOT DEMOCRACY; that’s USEFUL IDIOTS hating their own country. When the mullahs in Iran took over, socialists helped them, and later, the Islamists killed them all. This is the most dangerous moment for Western civilization. GOD BLESS AMERICA.
U.S. Senate candidate Abdul El-Sayed is a dark chapter in this great nation’s history.
And as the Bible warns:
“For whatsoever a man soweth, that shall he also reap.” — Galatians 6:7 (KJV)
Be careful what you plant in the name of democracy. You may not enjoy the harvest.
For the second year in a row Ambrus won Volatility hedge fund of the year!!!!
Super grateful for all of our investors that continue to trust us and allow us to perform the way we do as a vol hedge fund that specializes in carry-neutral tail risk hedging.
When we started this business 6 years ago, our goal was to bridge the gap between the art of tail risk hedging and good volatility trading. Truly humbling to reflect on how far we have come as a firm.
Lots of more work to do, and we will continue to keep our heads down and do it.
@DeepInference@TradableAstro Doubling down when you’re quite obviously wrong is comical. Wonder how many people got sucked into a 500/month sub just to have their shit pushed in
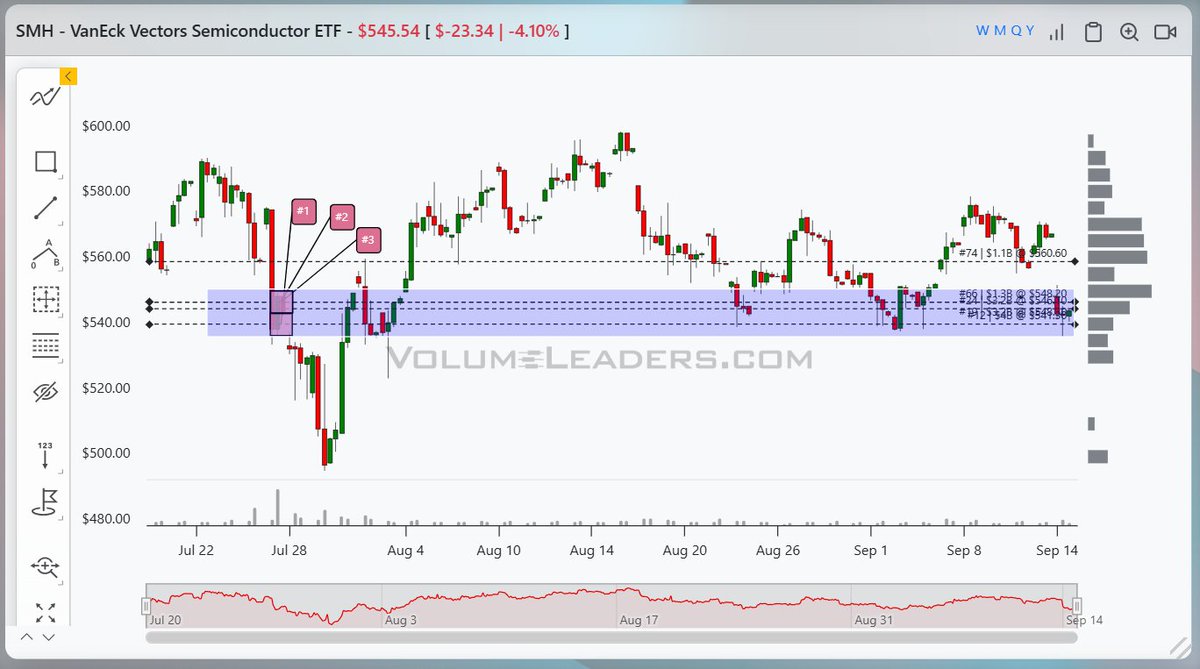
We call this region the Leopold Liquidation Zone (LLZ™️) **.
$SMH $541-$549 where the three largest clusters since inception reside. Clusters (in pink) are now chartable as individual units.
**Phrase coined by VL resident AI super hater @LeveragedOver.
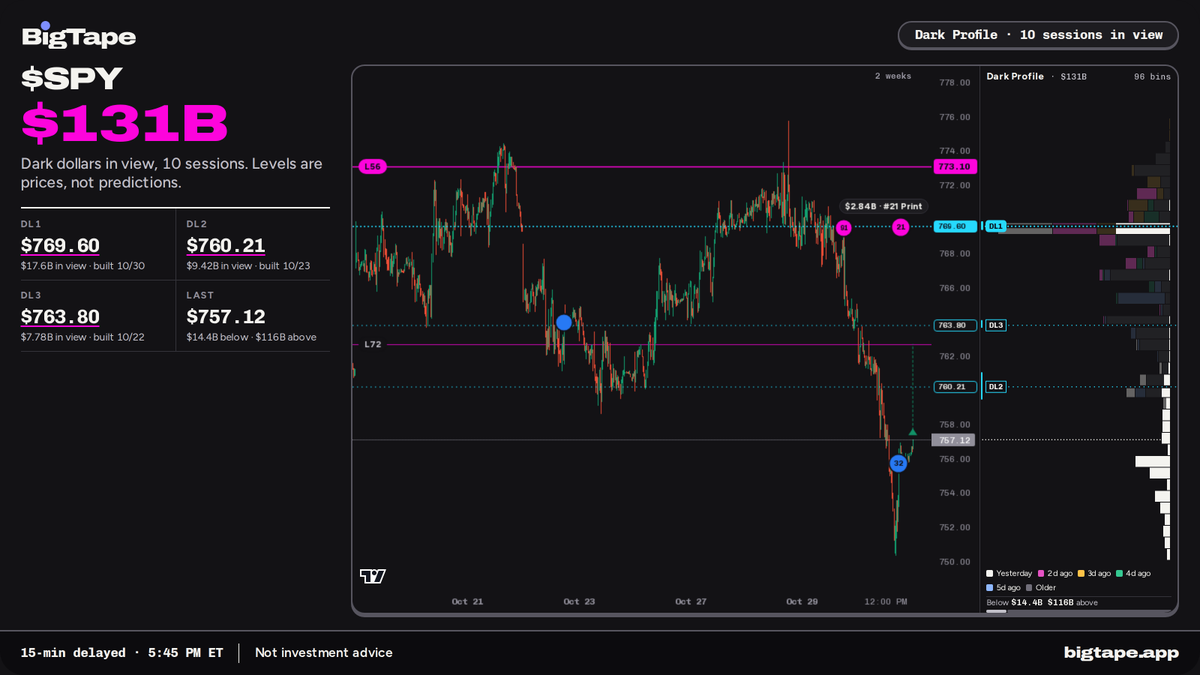
I used to work in iShares Capital Markets at BlackRock, and yesterday’s ominous $SPY print has a much more boring explanation than people are giving it.
It’s a pension fund rotating out of SPY into $IVV — a basic asset transfer that the iShares capital markets team gets paid to win.
IVV is a much better product for long-term holders: lower fees, better tracking, and a more tax-efficient structure.
The economics are simple. SPY charges 9.5 bps, IVV charges 3 bps, and on a $5B mandate that 6 bp gap is roughly $32M a year saved — every year, forever.
On top of that, SPY is structured as a Unit Investment Trust, which means it legally cannot lend securities and cannot reinvest dividends — the cash sits in a non-interest-bearing account from ex-date until the quarterly distribution, creating a small but persistent drag. IVV is a standard ‘40 Act open-end fund, so it does both. For a buy-and-hold pension matching long-dated liabilities, IVV wins on every dimension that matters except intraday options liquidity — which a pension doesn’t need.
Here’s why the dark pools matter. The actual rotation happens in the primary market between the Authorized Participant (AP) and the 2 fund sponsors: the AP redeems SPY shares with St. Street in exchange for the underlying S&P 500 basket, then delivers that same basket into BLK for new IVV shares. None of that prints anywhere — in-kind creation/redemption flows through NSCC’s CNS clearing system and is invisible to the tape.
What you do see on the tape is the AP’s secondary-market activity around those primary-market legs: sourcing the SPY shares they need to deliver into the redemption, sourcing or hedging the basket leg of the IVV creation, and squaring up residual basis between their execution prices and the day’s NAV strike.
They do this in dark pools because the size is too big for the lit book without moving the market against them, the flow is informationless (it’s mechanical, not directional), and ATSs are purpose-built for exactly this kind of non-toxic block liquidity. Those prints get reported to the consolidated tape within seconds under Reg NMS, which is why Volume Leaders caught them. The dark pool prints are not the trade itself — they’re the AP’s secondary-market activity wrapped around it.
The shares-outstanding data confirms it. SPY’s shares outstanding fell from 1,055.5M on Friday to 1,053.5M on Monday to 1,049.4M on Tuesday — a net redemption of 6.1M shares, or about $4.6B across the two days. IVV created 8.8M shares on Tuesday worth roughly $6.6B at the day’s NAV of $751.63. (Ignore Monday’s IVV share-count dip — that was the ex-dividend round-trip from holders avoiding the $1.9957 distribution, and it reversed Tuesday.)
The rotation spread across two trading days because SEC Rule 6c-11 and tax-efficiency best practice require a T+1 lapse between an in-kind redemption basket and the corresponding creation — so the AP redeems SPY for the basket on Day 1, then delivers that same basket into IVV on Day 2. That’s also why Tuesday afternoon’s 4:10–4:30 PM print cluster was the largest single tranche — the AP was finishing the secondary-market work ahead of the IVV creation cutoff.
This is exactly what an iShares cap markets win looks like on the tape. The team pitches a pension, wins the mandate, and the client moves the position via in-kind creation/redemption at NAV — no market impact, no spread, T+1 settle. The AP handles both legs in parallel, sources and hedges in dark pools to stay out of the way of the lit book, and the share counts catch up the next morning when settlement clears.
The fact that it’s happening near all-time highs is a non-issue. Pensions don’t time markets — they rebalance to policy weights and they change vehicles when procurement approves a cheaper one. The directional read here is neutral.
Credit to Volume Leaders for surfacing the print and pushing the conversation — their data is exactly what makes this kind of forensics possible.
@KASM_Capital Very helpful and really explained in great detail. There is a ton of discussion on these large ETF prints, and I’ve always felt they never helped me form a directional bias for reasons like the one you awesomely explained.