30+ EXCELLENT SME COMPANIES TO STUDY & TRACK 🔥🔥🔥
▪️ Yash Highvoltage
▪️ Shree Refrigerations
▪️ Merritronix
▪️ Millworks Technologies
▪️ Airfloa Rail Technology
▪️ KRM Ayurveda
▪️ Q-Line Biotech
▪️ Avience Biomedicals
▪️ Hemant Surgical
▪️ Devson Catalyst
▪️ Neetu Yoshi
▪️ E to E Transportation
▪️ Afcom Holdings
▪️ Aimtron Electronics
▪️ Remus Pharmaceuticals
▪️ Sunlite Recycling
▪️ Indo SMC
▪️ FlySBS Aviation
▪️ CFF Fluid Control
▪️ OBSC Perfection
▪️ Prizor Viztech
▪️ Apsis Aerocom
▪️ Taurian MPS
▪️ Poojaa Precision Engg
▪️ Concord Control
▪️ Accent Microcell
▪️ Unihealth Hospitals
▪️ Digilogic Systems
▪️ Systematic Industries
These are some interesting SME names worth keeping on the radar across different sectors. The objective is not to chase every stock, but to study the business, track execution, monitor fundamentals and understand the price structure before making any decision.
SME stocks can offer significant opportunities, but they can also carry higher volatility, lower liquidity and greater execution risk, so proper research and position sizing are extremely important.
Study. Track. Research.
Disclaimer:
No buy/sell recommendation. This is only a research and tracking list. Please do your own research (DYOR) before investing.
Quality Power Electrical Equipments - FY26 Annual Report Key Takeaways
• FY26 was a strong growth year: consolidated income rose 157% YoY to ₹1,007 Cr, while PAT increased 85% to ₹186 Cr. However, reported growth also benefited from the full-year consolidation of subsidiaries acquired in the previous year.
• The balance sheet strengthened significantly, with net debt down 77% and cash & bank balances at ₹248 Cr. Standalone debt-equity remained extremely low at 0.03x, giving the company room to fund its expansion.
�� Business mix: Power Products contributed 56% of revenue, while Power Electronics contributed 43%. The growing power-electronics exposure provides diversification beyond traditional high-voltage equipment.
• The biggest structural opportunity is the energy-transition + grid-modernisation cycle. HVDC and FACTS are key focus areas, supported by renewable integration, AI/data-centre demand and electrification of transport.
• Order-book quality: The company entered FY27 with an order book of ₹1,400+ Cr, increasingly weighted toward HVDC, FACTS and power-quality projects. These are technology-intensive projects with potentially higher value-add.
• Capacity expansion is aggressive: the new Sangli facility is expected to increase production capacity nearly 9x by Q2 FY27, while Cochin manufacturing capacity is being doubled. This creates significant operating-leverage potential if utilisation ramps up as planned.
• The company is moving up the technology curve. GIS is being positioned as the next major technology pillar, backed by its collaboration with Hyosung. BESS is another growth adjacency through Endoks.
• Technology differentiation: Successful type-testing of the world's largest three-phase MSR and HVDC converter reactors highlights the company's focus on specialised engineering and technology-led products.
• Mehru Electricals is an interesting turnaround: margins reached ~15% for FY26 and 20% in Q4, following operational integration. This provides an early indication that management is extracting value from acquisitions.
• Backward integration: The Sukrut JV provides access to critical transformer components and accessories, potentially strengthening supply-chain control as the business scales.
• International diversification: Quality Power serves customers across 120+ countries, with new contracts across Europe, the Middle East and Southeast Asia and growing presence in Scandinavia. This expands the addressable market, while also increasing FX and execution complexity.
• Capital allocation: IPO proceeds were deployed primarily toward the Mehru acquisition, capex and inorganic growth, with ₹17.5 Cr still unutilised at year-end. How effectively management deploys this capital will be important for future returns.
• Capex is already visible in the cash flow: ₹129 Cr spent on PPE/CWIP, resulting in negative investing cash flow of ~₹95 Cr. Capital commitments stood at ₹68 Cr, reflecting the ongoing expansion cycle.
• Cash conversion deserves attention: CFO was ~₹80 Cr versus PAT of ~₹186 Cr. As the expansion phase progresses, improvement in operating cash conversion will be an important indicator of earnings quality.
• Working capital will be worth watching: consolidated borrowings increased to ~₹35.5 Cr from ~₹8.7 Cr, primarily to fund working capital at the larger operating scale.
• ROCE improved from 12% to 19%. Management says the lower ROE is partly “optical” because post-IPO funds are still awaiting deployment into growth projects.
• Dividend discipline: the company recommended ₹1/share, while promoters holding 73.91% waived their dividend entitlement, signalling a preference to conserve capital for growth.
• Audit-sensitive areas: revenue recognition and contract assets were identified as Key Audit Matters because long-duration engineered projects involve significant estimates around project costs, completion and recoverability.
Quality Power is positioning itself for a multi-year power-grid investment cycle, with HVDC/FACTS, GIS, BESS, capacity expansion and acquisitions forming the growth playbook.
🔗 Full annual report link is in the thread for reference.
Disclaimer: This is not a buy/sell recommendation.
#QualityPower #AnnualReport #FY26
🚀 Big Bet. High Conviction.
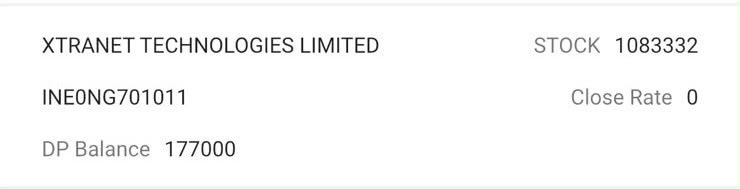
Excited to share my latest investment in XtraNet Technologies Ltd.
✅ Data Centres
✅ CBS Banking Solutions
✅ Digital Signature Solutions
📈 PAT: ₹10 Cr → ₹40 Cr in just 2 years (100% CAGR)
💪 ROCE: 35%
Accumulated 10,83,332 shares today.
In my family office “Mittal Growth Partners LLp”
This is one of those businesses that has the ingredients to create serious long-term wealth—strong execution, capital-efficient growth, and promoters with a clear vision.
The journey is just getting started. 🔥
#XtraNetTechnologies #Investing #SmallCaps #Multibagger #DataCenters #DigitalIndia
I had always said, what you make out and how much positive you make out from what you read makes the difference...that will decide whether u will be able to hold LT or sell for 10-20% profit!!
👇👇👇
Sister has a message for all my friends who eat broiler chicken from local shops.
I think food is a personal choice, but we can all source our food better. Even vegetables and fruits are Adulterated these days. We need to be cautious. This applies to Vegetarian and Non Vegetarian food as well 💪
Share this Widely and let us source our Food Well ❤️ Our Regulator needs to Crack Down on Anyone who Plays with Health.
#FI
Dear Gen Z,
This Brother speaks his Heart Out to You. Please Listen & then share to those who need to hear this !!!
Jai Bharat. Jai Jawan. Jai Hind 🇮🇳
#FI
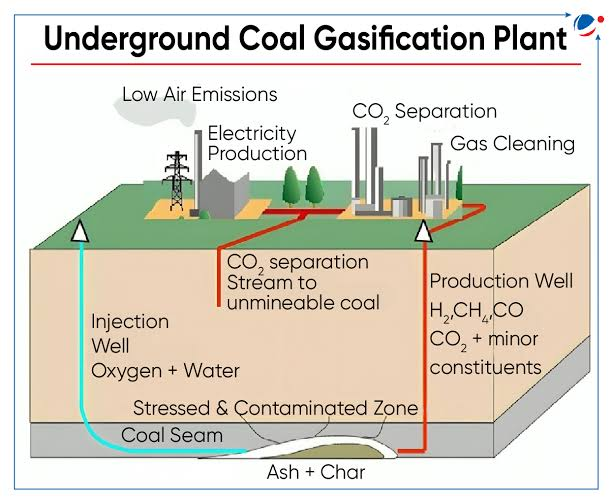
🧵 India's Coal Gasification Value Chain – Listed Stocks Ranked from Feedstock to Chemicals
1. Coal gasification = Coal/Lignite → Syngas → Methanol/Ammonia/H₂ → Chemicals/Fertilizers/Industrial Products.
The biggest winners may not be miners, but companies controlling engineering, conversion & downstream chemicals.
2. NMDC
Primarily a mining giant. No direct coal gasification role today, but could participate in future mineral and industrial ecosystem expansion. Low direct exposure.
3. GMDC
One of the strongest lignite-linked plays. If lignite gasification scales in Gujarat, GMDC becomes a key feedstock supplier.
4. NLC India
Among the most direct beneficiaries. Focused on lignite resources and actively evaluating lignite gasification opportunities.
5. NTPC
Potential future coal-to-syngas, coal-to-hydrogen and coal-to-chemicals operator. One of the highest-conviction long-term plays.
6. Sarda Energy & Minerals
Could become a syngas/hydrogen consumer in steel and ferro-alloy operations. Indirect beneficiary.
7. Godawari Power & Ispat
Industrial consumer angle. Benefits if domestic syngas, hydrogen or ammonia-based inputs become cheaper.
8. Jindal Stainless
Future user of hydrogen/syngas solutions for decarbonization and energy efficiency. Downstream beneficiary.
9. South West Pinnacle Exploration
Coal drilling, exploration and resource development. Benefits if new coal blocks and underground gasification projects expand. Jharkhand coal block allotment in 2027.
10. Asian Energy Services
Field services, exploration and energy infrastructure support. Indirect beneficiary through higher resource development activity.
11. Deep Industries
Gas handling and energy services. Possible supporting role but not a core gasification beneficiary.
12. Prabha Energy
Potential EPC/service participant. Limited direct coal gasification exposure currently.
13. Engineers India (EIL)
One of the most important names in the chain. Feasibility studies, engineering design, FEED and project management.
14. Larsen & Toubro (L&T)
Likely builder of large coal gasification complexes. EPC execution powerhouse.
15. Power Mech Projects
Construction, erection and commissioning opportunities from large gasification projects.
16. SEPC
Potential balance-of-plant construction participant. Smaller exposure versus L&T or Power Mech.
17. Thermax
Utilities, boilers, steam systems, waste heat recovery and environmental solutions. Strong supporting beneficiary.
18. BHEL
India's flagship gasifier and technology player. One of the most important coal gasification stocks overall.
19. JNK India
Process heaters and thermal equipment. Niche equipment supplier to chemical and gasification projects.
20/ Kirloskar Pneumatic
Compressors and gas-handling equipment. Essential supporting equipment supplier.
21/ Elecon Engineering
Coal handling, material movement and conveying systems. Infrastructure beneficiary.
22. IFGL Refractories
High-temperature refractory materials used in gasification and chemical plants.
23. Vesuvius India
Advanced refractory and thermal solutions for high-temperature industrial operations.
24. MSTC
Possible role in coal/resource auctions but negligible direct earnings linkage to gasification.
25. Refex Industries
Very limited direct connection. More of a peripheral energy/environment play.
26. Sustainable Energy Infra Trust
No major direct coal gasification linkage identified currently.
27. Hi-Green Carbon
Focused on recovered carbon black/pyrolysis. Adjacent circular economy theme, not coal gasification.
28. Rashtriya Chemicals & Fertilizers
Major ammonia and fertilizer beneficiary if coal-derived ammonia scales in India.
29. Deepak Fertilisers
Strong downstream ammonia, nitric acid and ammonium nitrate linkage. One of the best chemical beneficiaries.
30. Alkyl Amines and Balaji Amines(Chemical Winners)
Coal → Syngas → Methanol → Amines. Among the most attractive downstream value-add beneficiaries. Long-term winner if India becomes self-sufficient in methanol.
31. Linde India Limited and INOX Air Products
Gasification consumes huge amounts of oxygen. Many Chinese Big coal gasification plants have dedicated oxygen units.
🏆 My Coal Gasification Watchlist:
Balaji Amines | NTPC | NLC India | Engineers India | L&T | Thermax | Deepak Fertilisers | Alkyl Amines | GMDC | BHEL | RCF | South West Pinnacle Exploration Ltd
Indirect Beneficiaries
-Aegis Logistics Limited
-Linde India Limited
-GAIL (India) Limited
These benefit if volumes rise.
Fertilizers theme become beneficiaries if domestic coal-derived ammonia replaces imports
The biggest wealth creation historically happens in chemicals for future, not mining.
Coal → Syngas → Methanol/Ammonia → Specialty Chemicals is where margins compound.
Not a buy sell recommendation. Not Sebi registered advisor, DYOR before taking any investment decision.
Behari Lal Engineering
Big Bull Investor Madhu Kela backed #IPO#Behari Lal Engineering shares make blockbuster debut, list at 63% premium.
Behari Lal Engineering meets 10% of India's metal rolls demand. Positive long-term outlook due to strong capital efficiency, excellent operating leverage & upcoming capex-led growth.
Behari Lal Engineering Limited Anchor Book : Solid Company Solid Anchors
▪︎ Singularity Equity Fund (Madhusudan Kela)
▪︎Tata AIA Life Flexi Growth Fund
▪︎WhiteOak Capital (Prashant Khemka)
▪︎Bandhan Large & Mid Cap Fund
▪︎360 One Equity Opportunity Fund (Karan Bhagat)
▪︎Dynasif Equity Ex-Top 100 Long Short Fund (Karan Bhagat / 360 ONE Group platform)
▪︎PineBridge India Equity Fund
▪︎Ikigai Small Cap Fund
Amicorp Capital (Mauritius) Limited
CMR Green Technologies Limited IPO
Final Verdict
Applying For Reasonable-Big Listing Gains And Long-term
Highlights of the Issue :
Date : 3-5 June
Price Band : 182-192
Size : 631 Crore
(Full OFS)
M.cap : 4,206 Crore
Objects Of The Issue :
▪︎ To carry out the Offer For Sale for Promoters and Existing Investors and achieving the benefits of listing the shares on the exchanges
Key Pointers :
▪︎ CMR is India's Largest Non-Ferrous Metal Recycler, It is India's Largest and World's 6th Largest Secondary Aluminum Recycler, It has an installed capacity ~4 times that of the nearest competitor in the domestic recycled aluminium space
▪︎ CMR has ~17% market share in India's overall Recycling market, It holds ~70% Market Share in India’s Liquid Secondary Aluminum Market, It holds ~45% Market Share in India's Automotive Secondary Aluminum Market, Resembling It's Presence in every one out of two vehicles seen on the roads
▪︎ The Company manufactures recycled aluminium alloys (in ingot and liquid form), zinc alloy ingots, and segregated
furnace-ready scrap of stainless steel, copper, brass, zinc, lead, and magnesium,
among others.
▪︎ The Company primarily supplies its products to Automotive OEMs and Component Players and also few Non-automotive firms
▪︎ CMR's clientele includes Maruti Suzuki, Honda India, Bajaj Auto, Hero MotoCorp,
Royal Enfield, Motherson Sumi, Yamaha Motors, Toyota Corp, Hindalco, Gabriel,
Jindal Stainless, Aurubis GmbH, Rockman,Endurance, Sunbeam Lightweighting, Craftsman Automation, Etc.
▪︎ The Company has three Japanese Joint-ventures with Toyota Corporation, Nikkei MC Aluminum, Nippon Light Metal (In 2025)
▪︎ CMR has a strategic tie-up with Hindalco Industries to supply Non-Ferrous Scrap (It has setted up a used Beverage Can Recycling Plant dedicated for Hindalco
▪︎ The Company is now expanding into Extrusion alloys, Rolled alloys, Billets which have higher margins and more value addition
Financials and Personal Assumptions :
FY23
Revenue : 5,868 Crore
PAT : 104.5 Crore
FY24
Revenue : 5,952 Crore
Adjusted PAT : ~95 Crore
(There's a accounting adjustment of 1,239 Cr on the account of non-cash goodwill account leading to losses)
FY25
Revenue : 6,666.5 Crore
PAT : 155 Crore
9M FY26
Revenue : 6,275.5 Crore
PAT : 162.4 Crore
FY26E
Revenue : 8,950 Crore
PAT : 240 Crore
FY27E
Revenue : 10,500 Crore
PAT : 290 Crore
Valuing CMR at 25× FY27E PAT, Fair Value Comes At 330, Implying An Upside Of 72%
The IPO is being priced at super attractive and juicy Valuations leaving a significant upside on the Table for Retail investors and Institutions
As the Automotive industry is moving from ICE to EV, The aluminium consumption in the EVs is three times than an ICE vehicle, leading to a significant demand for Secondary Aluminum products going forward
CMR has a very strong set of clientele and Long-term relationships with Tier-1 Automotive players and component players which will help to increase its business significantly
The Company is doing a lot of Capex and ramping up Capacities of recently Commenced facilities leading to incremental growth and margin optimization
The Anchor Book was the finest one for a <200 Cr book
The Company is also looking to expand its margins and aspiring to expand its market share from ~17% to 20-25% in next 3 years
CMR has delivered a Revenue CAGR of of ~23% from FY07 to FY25, The Aluminum Recycling Market is set to grow at ~13.5% CAGR from FY26-30E
The Global shift towards environmental sustainability and use of Recycled Metals is acting as a strong Tailwind for CMR
The Promoter Holding Post-IPO at 83%, while the PE fund's Stake comes down to 1% which suggests no hanging sword of future supply
I am definitely looking to add this up in my portfolio if Lists till 30-35% Premium, considering allotment would be super tough (Can look to make a aggressive position around 30% Premium)
Just A Personal View, Only For Educational Purposes
The Power of Systematic Investing explained in under 150 seconds.
@gajendrakothari ji - Hats off for your Consistency.
I want everyone in my audience to watch this and share widely.
Simple. Powerful. Underrated advice.
#FI