BREAKING 🚨: Private Credit
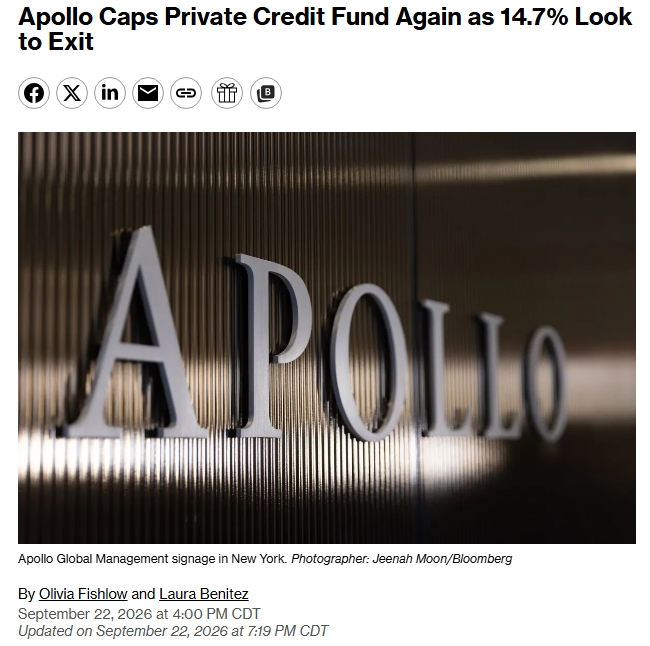
Apollo Global, one of the world's largest money managers, just limited withdrawals from its flagship private credit fund for the 3rd consecutive quarter 🤯 Apollo is capping redemptions at 5%, investors wanted triple that 👀
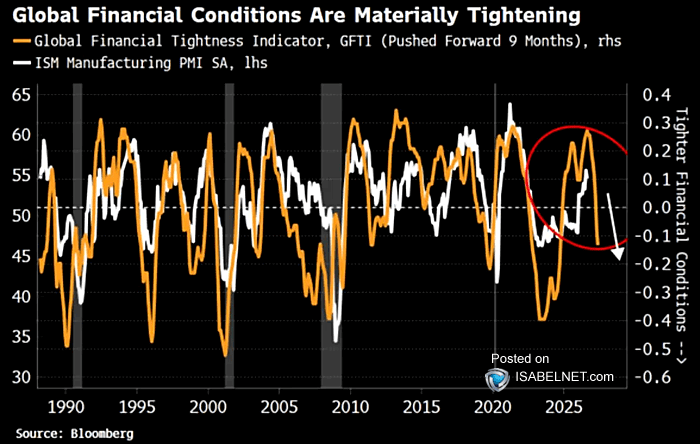
📌 ISM
Tighter financial conditions are starting to hit manufacturing sentiment and order flow. If the squeeze persists, the ISM Manufacturing PMI could weaken further, adding pressure to risk assets
👉https://t.co/blMxcoFA78
@markets $spx #spx#ISM#stocks#equity
The value of the IPOs of SpaceX, Anthropic and OpenAI is expected to surpass $5 trillion. “Now compare that with the entire history of IPOs from 1980 to 2025. The 3,365 tech companies that went public in that period were worth a combined $4.1tn when they started trading."
📌 Capex
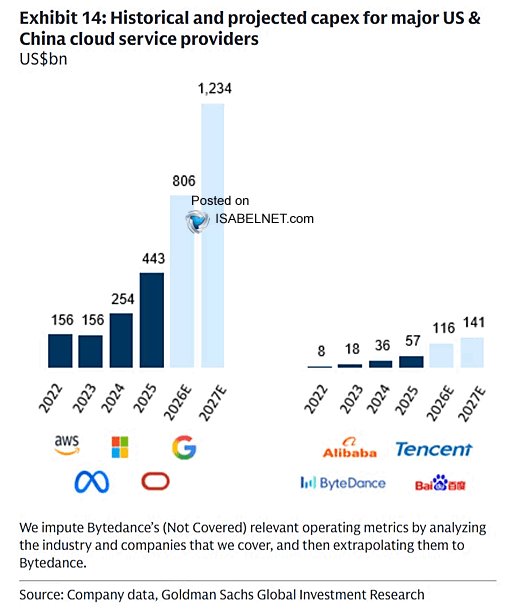
US hyperscalers are on track to spend $806 billion this year, with annual capex projected to reach $1.234 trillion by 2027. That kind of spending points to an AI infrastructure supercycle, not just another phase of cloud growth
👉 https://t.co/blMxcoFA78
@GoldmanSachs
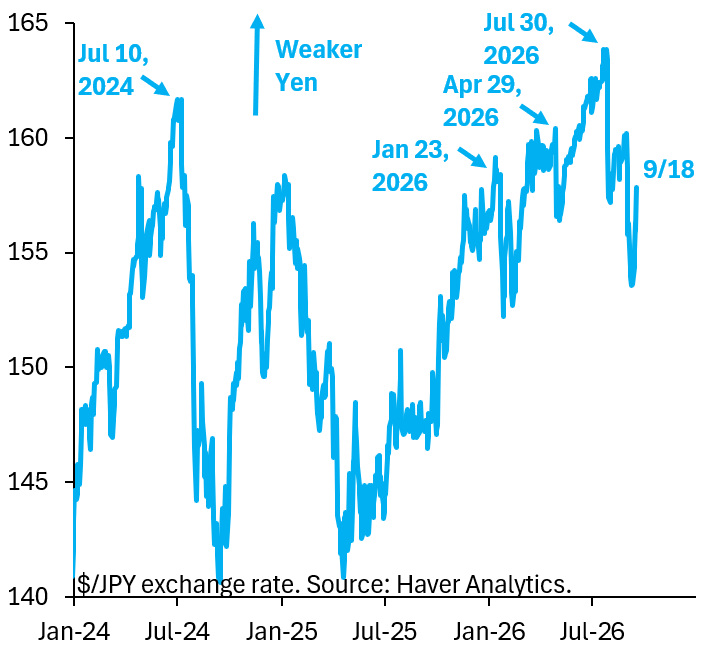
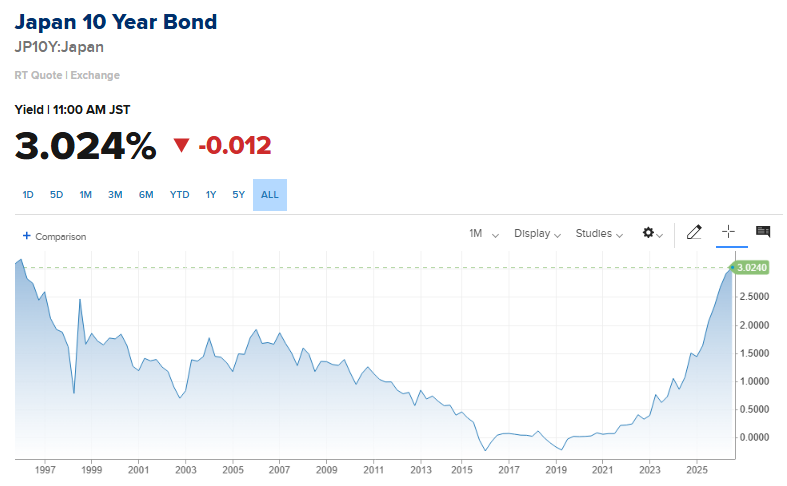
Only the BoJ can save the Yen, not intervention. The timid hike we got overnight just isn't good enough given how low Japanese interest rates and long-term yields are compared to the rest of the G10. Too much debt means the BoJ is stuck. Fiscal dominance.
https://t.co/HkTL5kfLrI
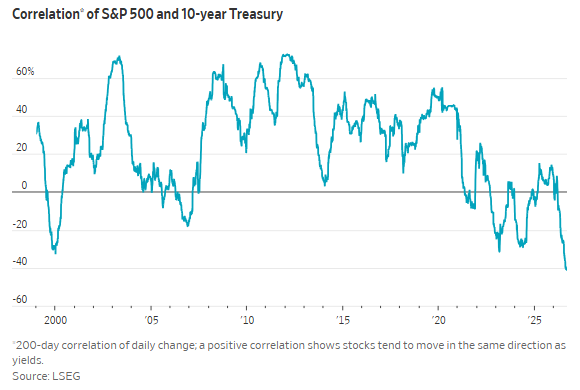
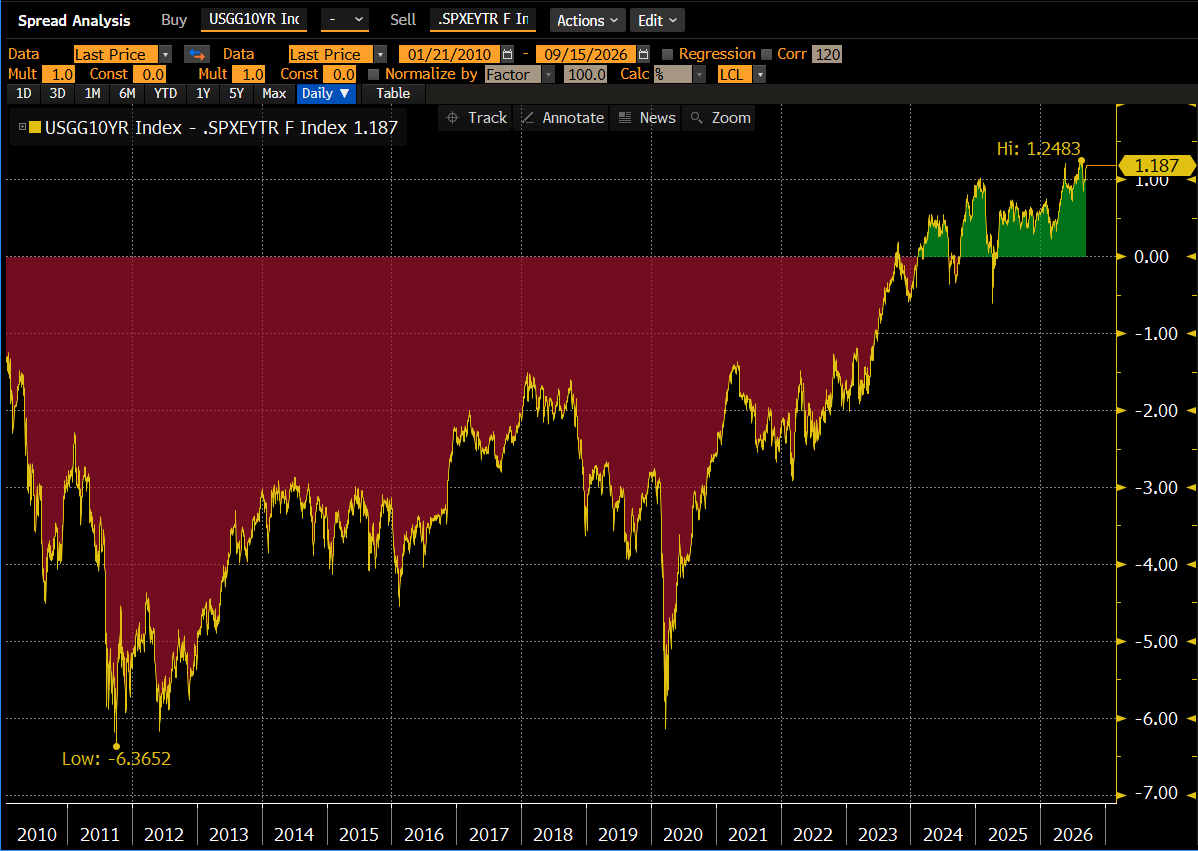
Yields on 10-year Treasuries are about the highest relative to a similar measure on the S&P 500 since 2000. That's still not enough to materially attract multi-asset investors away from stocks. (1/2)
When people say that the rate hike is priced in, they don't take into account this hike is only the 1st rate hike in a series of hikes. Going back to 1990, there was only 1 case of a "one and done" hike. In all other cases the Fed had tightening cycles of at least 175 bps.