I keep coming back to $GLXY because I’m not sure the market fully appreciates what Helios is becoming.
Forget crypto for a second. Do the megawatt math.
Helios: ~1.63 GW ERCOT-approved power
CoreWeave: 800 MW gross → 526 MW critical IT load
Contract economics: $1B+ annual revenue at full ramp
Implied revenue: ~$1.9M per critical MW/year
CoreWeave has effectively absorbed only ~49% of Helios’ CURRENT approved gross power.
If the remaining capacity eventually achieves comparable density/economics, 1.63 GW could theoretically support ~1.07 GW of critical IT load - implying roughly $2B/year of revenue capacity.
And Galaxy has discussed Helios ultimately reaching ~3.5 GW.
Apply the same crude math and you’re talking ~2.3 GW of critical compute and >$4B/year of theoretical revenue capacity.
Obviously, power ≠ compute ≠ contracted revenue. There are enormous capex, construction, financing and execution assumptions between those numbers.
But that’s precisely the point.
In the AI race, GPUs are manufactured.
Gigawatts of interconnected power are much harder to manufacture.
$GLXY started as a crypto company and somehow ended up owning one of the scarcer commodities of the AI era: energized land at scale.
Crypto funded the optionality. Helios may end up being the asset that matters most.
$NXH has roughly 38.8% direct/indirect exposure to tZERO, which owns 100+ issued patents around tokenized securities infrastructure and now has a collaboration with ICE/NYSE.
Meanwhile, Securitize (the competitor to tZERO) has seen public-market price discovery in the multi-billion-dollar range after IPO earlier this year. tZERO is currently in a legal battle with Securitize over patent infringement.
The Fathom transaction effectively values NXH’s contributed digital-asset portfolio at just $130M+. Even assigning all of that to tZERO implies only roughly a ~$335M valuation. Some say this is far too low, and true valuation is yet to be seen.
Securitize clearly has greater current scale, but the valuation gap is hard to ignore if tokenization infrastructure keeps rerating.
If you look at NXH’s market cap, it seems far too low when looking at retail and blockchain assets, alongside improvements in margin on the retail side.
Amazing.
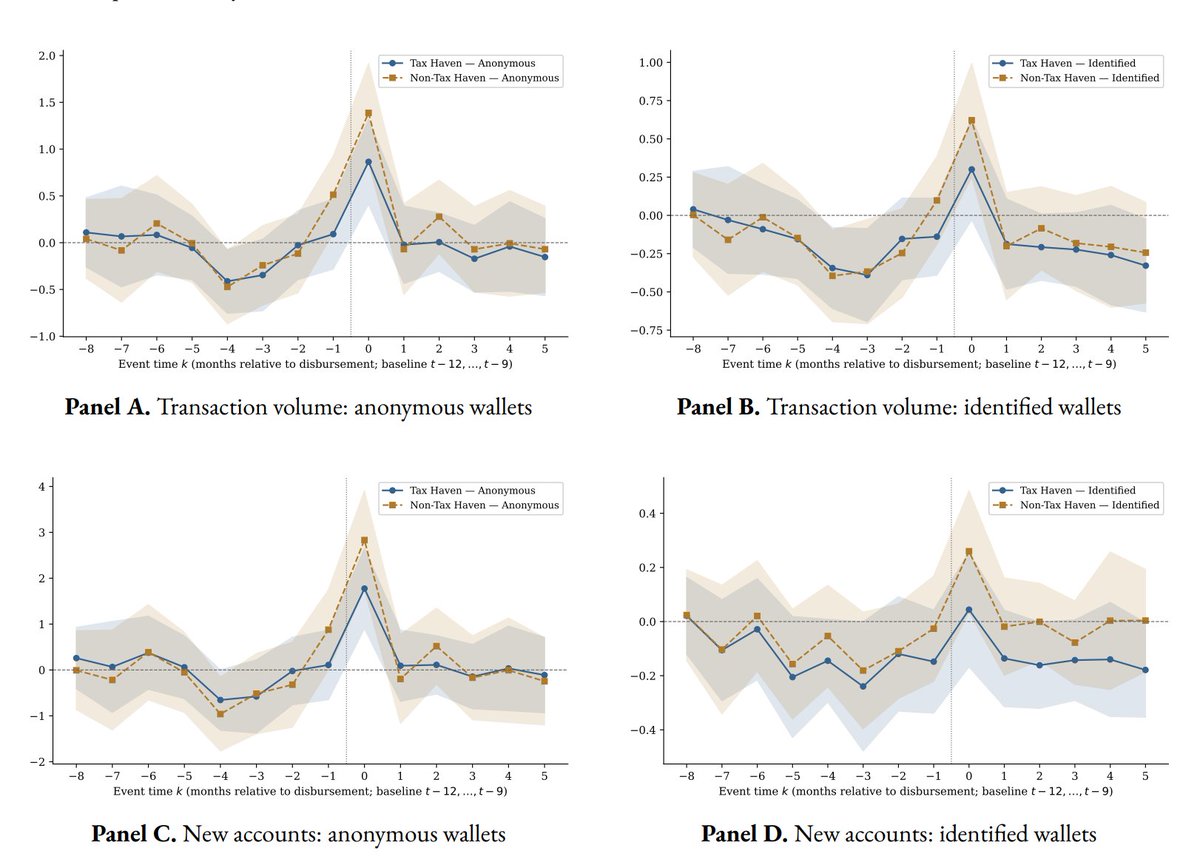
These researchers found that there's a spike in Bitcoin activity around the time foreign aid money goes out.
Somewhere between 2 and 6 cents of every dollar of World Bank foreign aid disbursements got siphoned off into crypto wallets:
I understand the goal is to bring tZERO closer to accessible public markets and allow for better price discovery. My concern is that decoupling the blockchain/tokenization component from $NXH and creating a proxy ownership vehicle through Fathom introduces real risk.
If Fathom rerates, $NXH should benefit. But it also gives investors another way to play the tZERO thesis. As we’re already seeing across X, some investors may simply prefer owning tZERO directly or buying Fathom shares rather than $NXH.
That said, the upside cuts both ways. If Fathom sees anything resembling the type of price discovery we’ve seen with Securitize, $NXH’s underlying exposure could become significantly more valuable and potentially drive a major rerating in $NXH as well.
So it incentivizes shareholders to own both $NXH and $FTHM imo.
Starting to think there may be some real asymmetry developing in $NXH.
$SECZ has ripped ~170% since mid-August as the market suddenly starts pricing the tokenization narrative. It now sits around a $2.8B valuation.
Meanwhile $NXH sits around a $295M market cap despite having ~38.8% direct + indirect economic exposure to tZERO, plus Medici assets and a direct investment in GrainChain.
NXH’s proposed Fathom transaction just assigned at least $130M of value to those digital assets, driven principally by tZERO.
And tZERO isn’t vaporware. It operates regulated ATS/broker-dealer/transfer-agent infrastructure, has a 105-patent IP portfolio, and is actively litigating against Securitize over tokenization-related patents.
Then you have the SEC’s new 5-year Innovation Exemption opening the door for qualifying venues to trade tokenized NMS stocks onchain.
Not saying tZERO deserves a Securitize valuation. It doesn’t have the same scale or execution.
But when one tokenization pure play is getting aggressively rerated and another public company owns a large economic stake in competing regulated infrastructure while barely moving…
That disconnect gets interesting.
$NXH is messy. But messy + overlooked + valuable embedded assets is sometimes where the asymmetry lives.
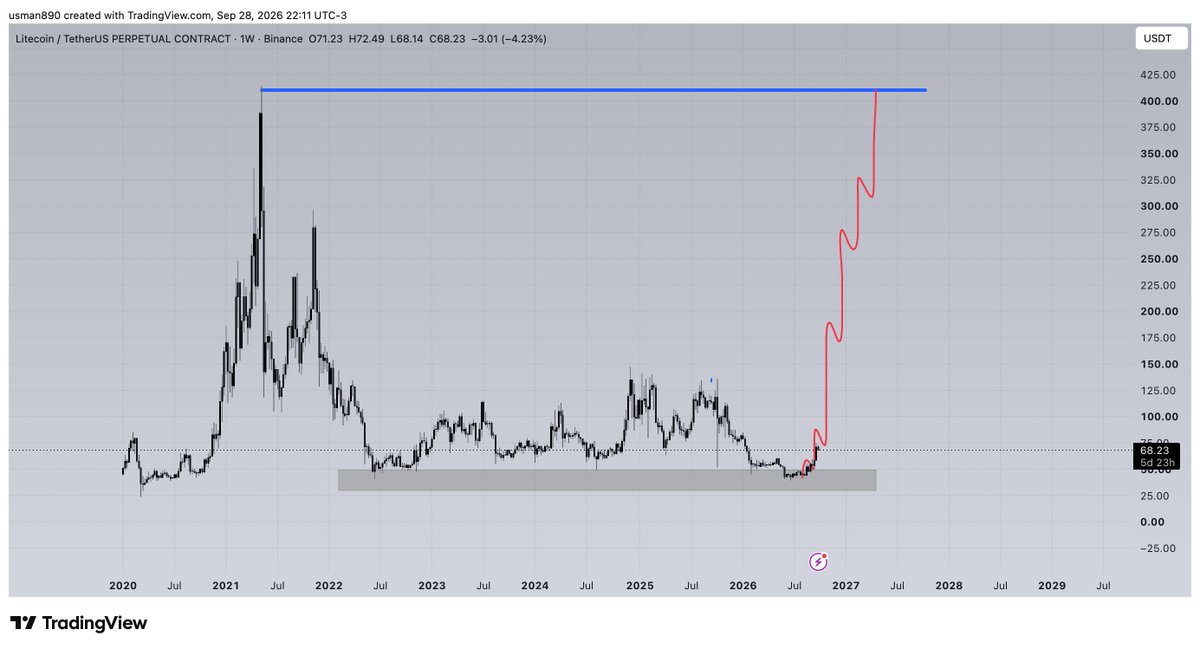
No privacy coins yet compare to $LTC in terms of daily transactions and active addresses. Yet Zcash gets a $27B mc? Make it make sense. A comparable price for Litecoin at that valuation would be $350.
Litecoin:
Price: $71
Transactions/Day: 160,000
Active Addresses: 240,000
Dash:
Price: $64
Transactions/Day: 10,000
Active Addresses: 23,000
Zcash:
Price: $1561
Transactions/Day: 8,000
Active Addresses: 7,000
I think you were just early. Most great investors usually are.
The move in $ZEC is opening a lot of people’s eyes that the market, over last couple cycles, shifted from core tenants like privacy and fungibility to throughput, efficiency, smart contracts and speed.
Beyond immutability and censorship resistance, privacy was one of the foundational ideas behind crypto.
Pendulum always swings back imo.
Can’t you just FEEL it Thomas?
Kidding. I think:
• ‘Zcash 2.0’ re-rating potential via narrative of MWEB/privacy + fungibility. So, I view it as a possible sympathy play
• Canary Litecoin ETF (LTCC) has been live since October 2025, and Grayscale filed a week ago around listing its Litecoin Trust on NYSE Arca as an ETF, giving $LTC a much cleaner path for traditional capital than most alts
• One of the most hated and ignored OG alts, which makes a re-rating more explosive
• Still supported by PayPal/Venmo/Bitpay and widely available across major exchanges
• Real payments utility: fast, cheap, battle-tested PoW network
• 84M hard cap with most supply already mined
• Strong legacy community and long-term holder base
• 2027 halving adds another supply-side catalyst where historically Litecoin has run 6-12 months beforehand
@BryanGreenbaum@Bkclaims Yeah I think I didn’t buy it bc the public float only represented 8% ownership bc of so much insider ownership of the company & $FRMO ownership. If Thomas was still there, I’d prob reconsider.
1) I did not create the $HEISENBERG coin, someone else did it for me. Clearly.
2) This is the CA: 8DwNVMzpcc3mq7Tk4gyWeTkvmFhnXcnDDCLayFFhXvex in case there are people trying to fake the coin.
3) I have zero personal financial gain from this. I told you guys repeatedly whatever I get I will donate back 60% to my followers via X money with receipts. The 40% I will need to make sure how the taxes work.
4) This has been fun for the last hour.