@NonameStephens@tclaugus2 We certainly did - funny bc they aren’t really calling out integration issues… which would mean more downside no? I’m going to wait and see how tomorrow trades , I don’t think these results were awful vs expectations but we shall see
@tclaugus2@NonameStephens FDXF at 5% was first one came to mind. don't know the exact type of RE leases they are operating under also so can't run with that too much but they shouldn't have capex on their purchased transport but it should probably be more than 5% of company vols given the network scale
agreed re capex, something I have been thinking about and did ask them about but probably didn't harp on enough. I had bought in the 4 handle range but added some under 3 - I may nibble a little more here. They don't own their terminals so I think 5% makes sense or a little lower due to half being purchased transport. H&A fleet is a little older than theirs too but good assets from what I gather.
Yeah funnily enough im not worried about the cap structure or liquidity - think market is.. I model 20-30mm per annum capex iirc
@GunDogCapital@NonameStephens@tclaugus2 I strongly ~expect~ that. They kinda sandbagged the synergies. If u want take a look at my writeup I breakdown potential opportunities. The back haul is probably not fully achievable, but R&M, fuel synergies obviously back office stuff is very low hanging fruit.
@NonameStephens@tclaugus2 Yeah tricky thing here is expectations are really low already so mkt could be more fwrd looking I.e. mgmt is going to give more granular guide on synergies, update on repricing, fuel updates… so I could see it go down 25% or up 🤷🏼♂️
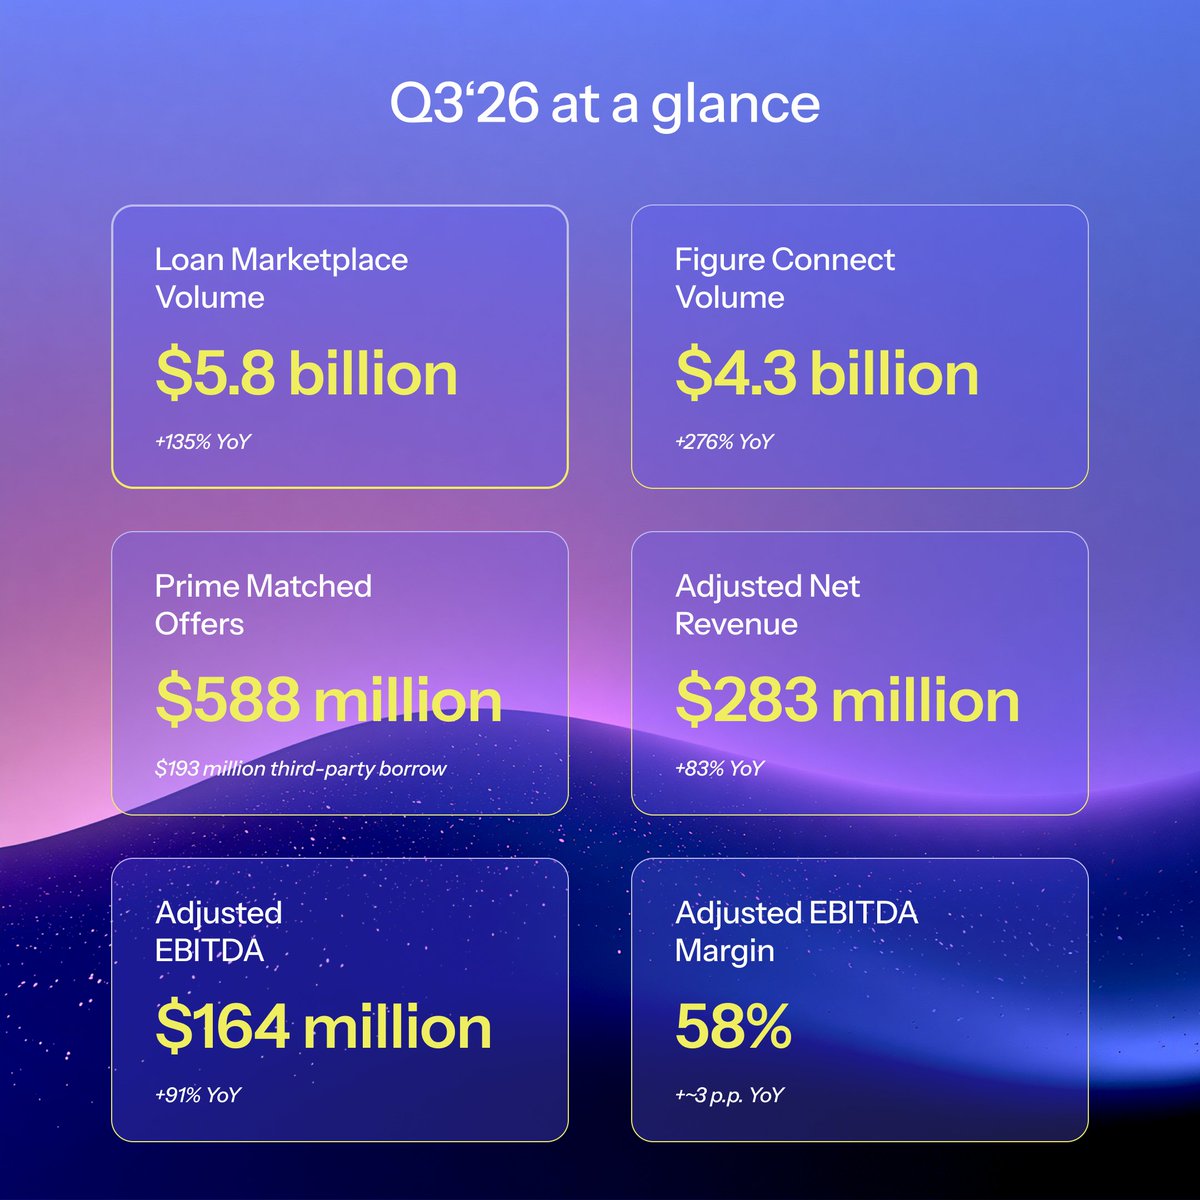
Another record quarter at @Figure.
83% top-line growth, 58% margins, meaning we’re again “Rule of 140” in the “Rule of 40” investor framework. It’s a rare stat to be able to share once, but this is our fourth straight quarter of Rule of 140. It’s rare air + staying power. Really proud of our team.
We added 100+ partners and are now at 612 on our marketplace, and 894 when including broker partners of Kiavi, which we closed on September 1. We’ve also expanded volume more than 40% with partners who have been with us for a year or more.
Much more in our full results here: https://t.co/7hY0aRwDsU
I think that’s fair - and ORLY may just be too far ahead but let’s not forget industry is still pretty fragmented. I do think the biz is improving already so it’s a little more than just hopes, they have executed, but definitely more would to chop.. I will also say there is an argument AAP doesn’t need to exist atp with azo and orly so dominant. 2027 the prob the make or break year
Yeah I hear you, i don’t have a big sample size but same. That said, I believe that can change over time and they are actually adressing the core problems that have caused them to underperform peers for years - supply chain the big one, customer mix, inventory management / stocking.. etc. Execution risk is definitely there but new mgmt is good and has made some solid progress , believe the recent headwinds are largely macro
@ABCTrading12@jeremie0117 Ya agreed - this q I am fairly certain is bad but still free cash +ve so idrc the upside is so massive when/if they survive and integrate. Happy to chat the name hit my dm