Hangzhou's humanoid traffic aides stay out in the wind and rain
Hangzhou rained through China National Day. Deep Robotics treated the holiday as a field window and put a batch of DR02s in the West Lake district:--visitor guidance in the crowds, and directing, order-keeping, and tourist questions at the arterial intersections, backing up traffic police on the road.
>IP66, so they stayed out in the rain. Rated about −20°C to 55°C.
>Gestures follow the signal timing. They shift inside the intersection, yield to people and cars, and move on to the next post when a point is done.
>Vision flags no helmet, overloaded bikes, pedestrians over the line, and cars stopped past the line, then a voice reminder.
At scenic entrances they answer directions in Chinese, English, and more, so officers aren't stuck on the same questions.
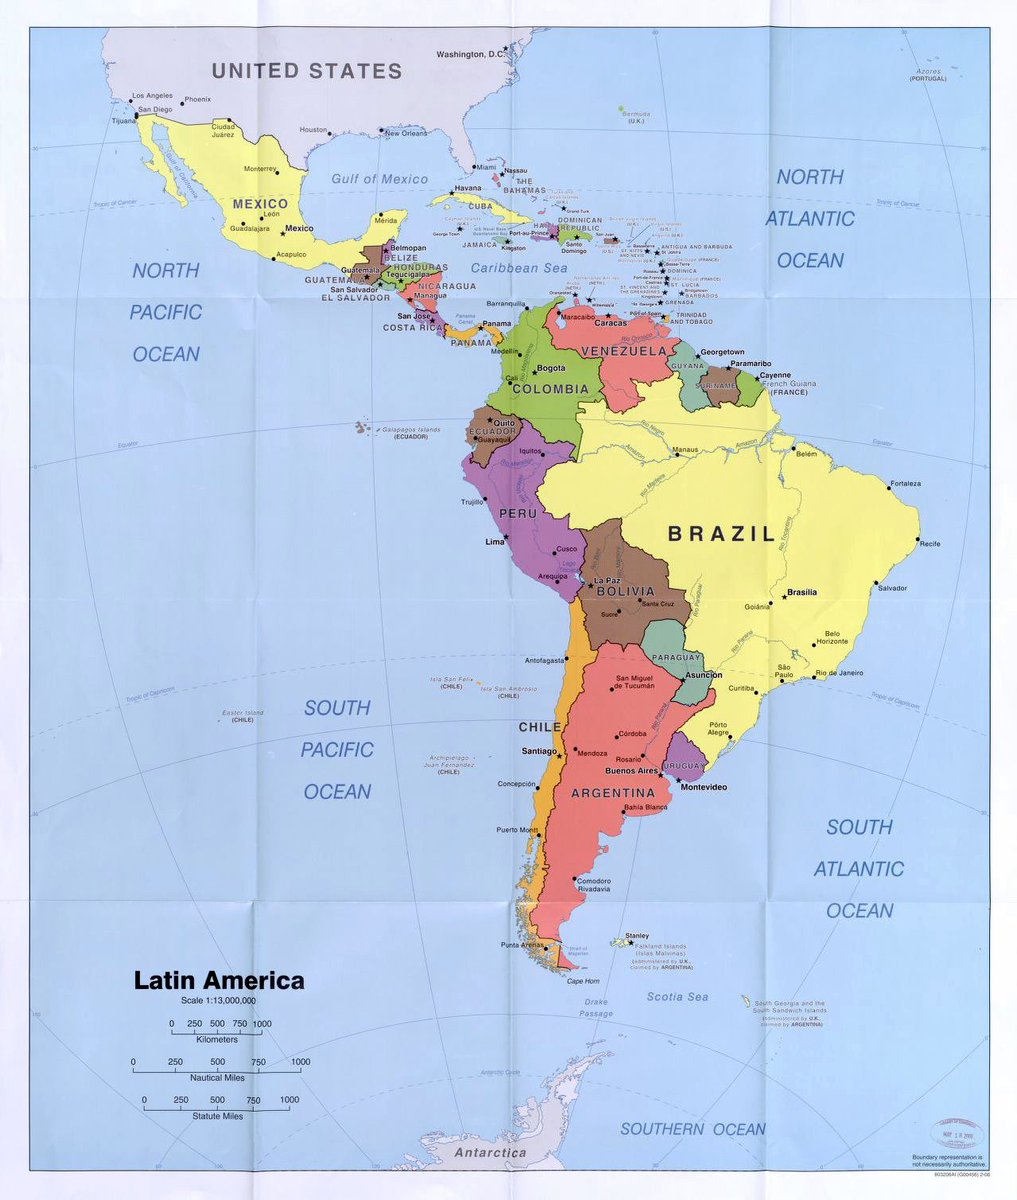
A new Golden Age of Latin America is right around the corner (we'll see what happens after Oct 25).
That's a big economic unlock for the region and the world economy.
Now let's see if Europe falls further behind.
$MELI $NU $DLO
We built this factory twice — once in the digital world, once for real. 💻➡️🏭
Our industrial simulation system verified everything before construction: layout, logistics, production rhythm.
EP.3 of our factory tour series — the smartest part is still ahead. 👀
#UBTECH #HumanoidRobot #DigitalTwin #SmartManufacturing #AI
Equasens
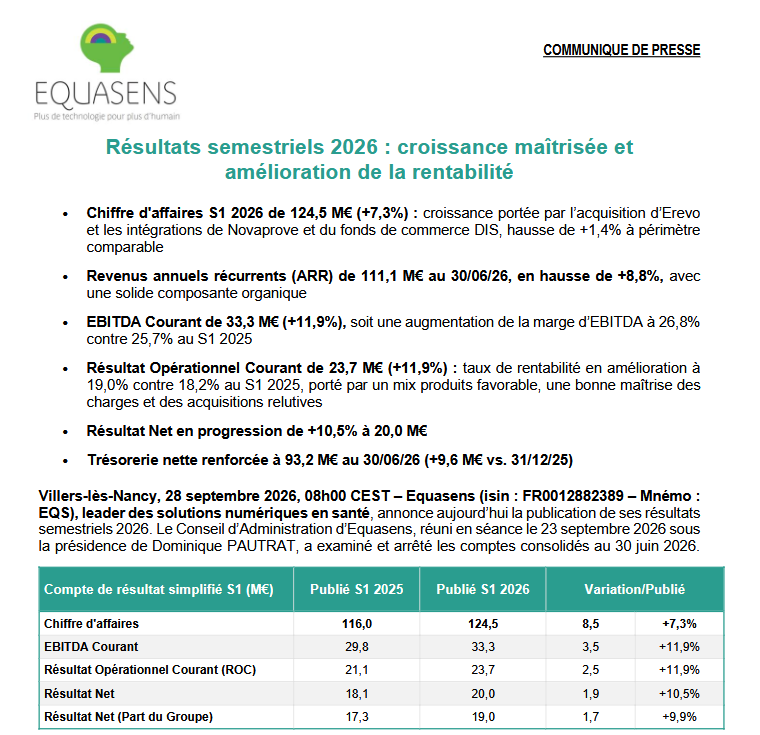
- Si la croissance organique déçoit, les marges restent solides et augmentent nettement plus vite que le CA avec un Ebitda et un bénéfice tous deux en hausse > à 10%
- Un dossier désormais très value : PE retraité du cash x8 et VE/Ebitda < 5
10 small caps under $10 with high potential
$ONDS - Ondas
Ondas is building a fully integrated system of autonomous defense platform that combines hardware, software, AI, robotics, and connectivity across multiple operational domains.
YTD stock performance: -25%
Backlog: $750+ million
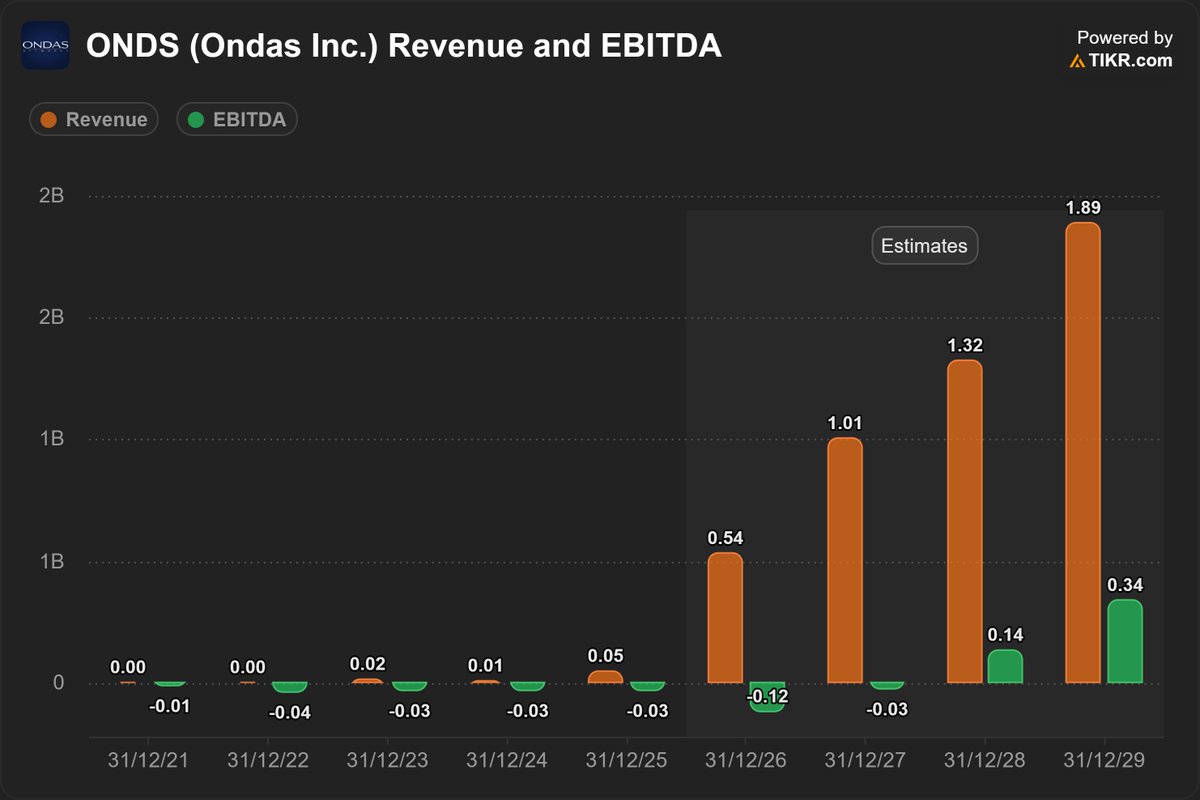
Revenue is expected to grow at a +147% CAGR through 2029. From $50 million in 2025 to over $1.8 billion by 2029
Profit Margin: 49.2% profit margin, the first positive result and an improvement from -270% in 2025.
Gross Margin: 43.7%
ROE: 19.3%
D/E: 0.03x
EBITDA and FCF are expecting to become positive by 2028
Humanoid robots are starting to build humanoid robots.
UBTECH just put a 14,000㎡ humanoid robot factory into operation in Liuzhou, China, with a designed takt time of one humanoid every 10 minutes and planned annual capacity in the tens of thousands.
What’s interesting is that humanoid robots are already part of the production process.
Cruzr Y1 and Y2 handle depalletizing, palletizing, material feeding and transport, using 3D vision to adapt to shifted boxes and changing pallet patterns. On the assembly side, Walker S2 and Cruzr are produced on the same line alongside cobots, autonomous logistics vehicles and assistive manipulators.
The factory also has a 65㎡ automated warehouse capable of storing 112 humanoids, with AGVs, industrial robots and stacker cranes coordinated as one system. Before production, the factory was modeled 1:1 in Siemens Plant Simulation, covering workstations, racks and AGVs. Each robot gets its own SN, with components, batches, assembly parameters and inspection data tracked all the way to delivery.
Humanoid robots are now entering automated manufacturing at the 10,000-unit scale.
The next milestone may be when they can take part in enough of the assembly, testing and production process to truly build robots themselves.
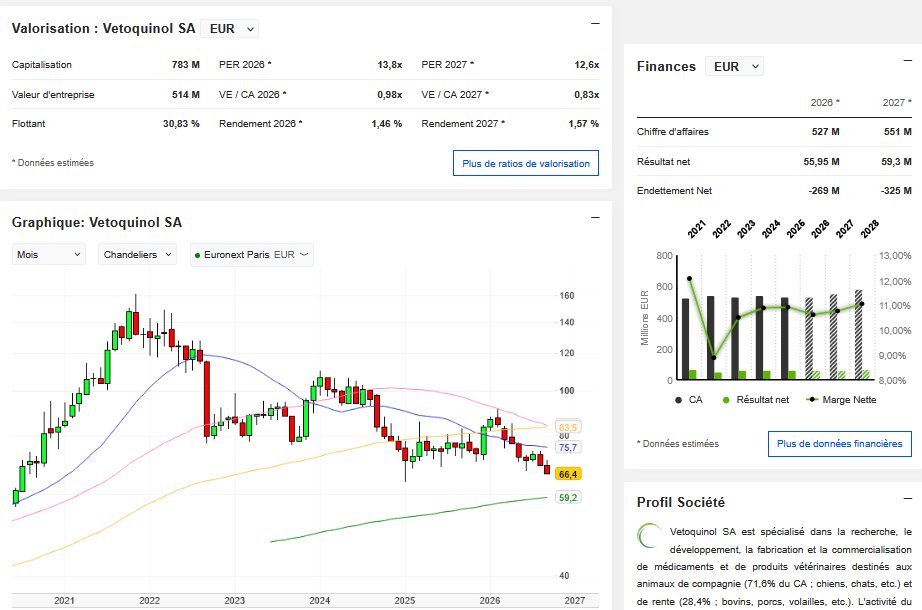
Virbac & Vetoquinol
- Valos déprimées pour des entreprises défensives et de qualité
- PE de 15 pour Virbac qui publie de très bons chiffres de croissance en 2026 (+7.5% au s1)
- PE de 13 pour Vétoquinol qui stagne toujours mais garde une montagne de cash + un très bon FCF yield
Initiating Coverage for US IPO Today: The Biotech Unicorn Hiding in Plain Sight (High cash and already net profit positive)🧬
Clinuvel Pharmaceuticals $CUV $CLVLY $CUVL
Today marks a monumental day for Clinuvel Pharmaceuticals with its ADR Level II Nasdaq uplisting—effectively acting as its US "IPO" day for institutional capital. Here is the deep-dive on why this asset is fundamentally mispriced.
1️⃣ Company Introduction
Clinuvel is an integrated biopharmaceutical company specializing in severe genetic, metabolic, and skin disorders.
Shareholders:
The register is anchored by high-quality institutional capital, featuring JPMorgan (6.96%), BNY Asset Management (6.65%), Ender I (5.14%), Vanguard (2.41%), Dimensional Fund Advisors (1.69%), and Norges Bank (1.10%), with the remainder held tightly by retail and insiders.
From Past to Future:
Over the past two decades, the company evolved from an R&D-heavy biotech into a highly profitable, self-sustaining commercial entity. The future strategy shifts from a single-asset orphan drug model to building a diversified "Melanocortin House" targeting broader CNS and dermal indications.
Technology:
The core tech revolves around melanocortin peptides, primarily afamelanotide. They are pioneering controlled-release formulations (VLRX-L platform) and translating this medical IP into over-the-counter PhotoCosmetics for DNA repair and polychromatic photoprotection.
2️⃣ Product Presentation & Current Developments
SCENESSE (afamelanotide 16mg) is the first approved treatment for Erythropoietic Protoporphyria (EPP), distributed directly to over 120 US specialty centers.
The major value driver now is the Phase III label expansion into Vitiligo, offering a first-in-class systemic, non-immunosuppressive therapy for an unmet clinical need.
Simultaneously, the company is advancing NEURACTHEL (instant and modified-release ACTH) for infantile spasms and multiple sclerosis.
3️⃣ Valuation Snapshot
Tthe Market Cap stands at AUD 496.6M (approx. USD 320M).
Net Debt is incredibly negative; the company carries absolutely zero debt and holds formidable cash reserves of USD 155M as of December 31, 2025.
This brings the Enterprise Value (EV) down to roughly USD 165M.
With TTM EBITDA at approximately USD 38M (AUD 57.2M), the stock trades at an absurdly cheap EV/EBITDA multiple of around 4.3x.
4️⃣ Earnings Snapshot
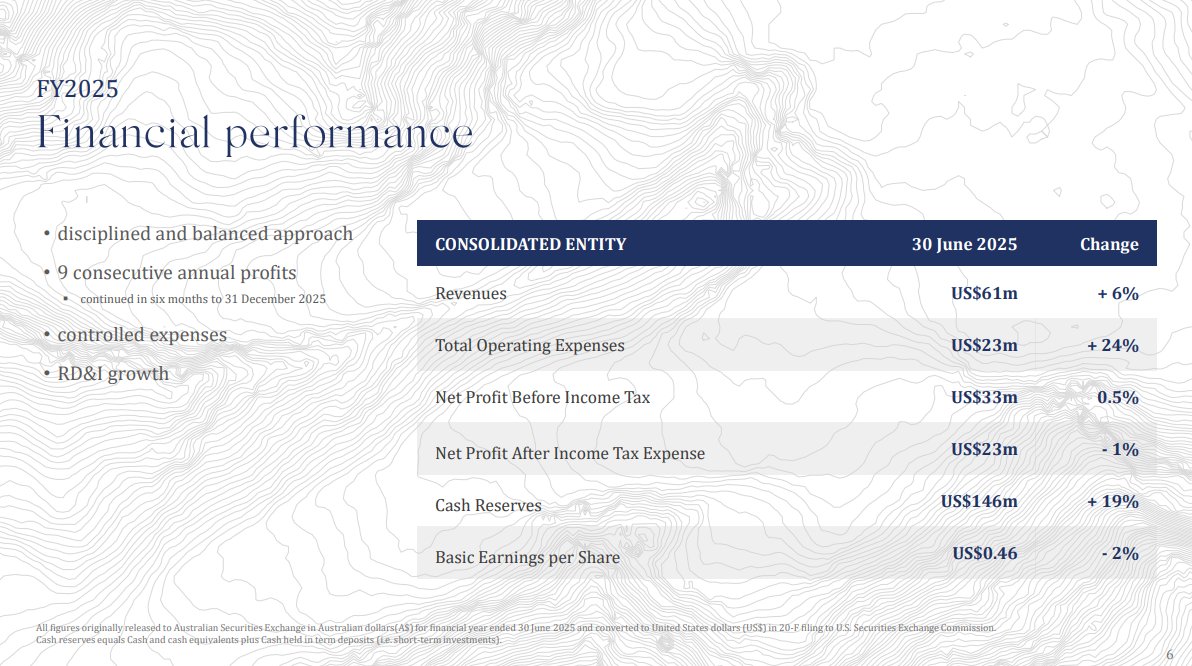
Clinuvel is a cash-generating machine. It has achieved 9.5 consecutive years of profitability.
FY2025 revenues hit USD 61M (+6% YoY) with a net profit after tax of USD 23M. With operating margins effectively north of 30%, they internally fund all R&D without diluting shareholders for the past 10 years.
5️⃣ Peer Group Comparison
Compared to rare-disease peers like Amicus (FOLD), PTC Therapeutics (PTCT), and Mirum (MIRM), Clinuvel is fundamentally superior in financial health.
While peers often rely on debt and dilute equity to survive cash-burning Phase III trials, Clinuvel operates debt-free and generates net margins over 30%. Despite this quality, it trades at a massive valuation discount compared to its peer group.
6️⃣ Forecast 2030 & Valuation
The Vitiligo total addressable market is USD 4.5B, and the PhotoCosmetics TAM is USD 6.2B.
Assuming conservative penetration and regulatory success, 2030 revenues could easily scale beyond USD 250M.
Assuming steady margins, 2030 EBITDA is projected at USD 120M. Applying a conservative 10x EV/EBITDA multiple yields an EV of USD 1.2B.
Adding estimated accumulated cash, a 2030 Market Cap of USD 1.5B+ is highly feasible—a near 5x upside from today.
7️⃣ Acquisition Potential from Outside
Given the pristine balance sheet, zero debt, and high-margin monopoly in EPP, Clinuvel is a prime M&A target.
Big Pharma looking to instantly acquire profitable orphan-drug revenue and a de-risked Vitiligo Phase III pipeline could justify a massive premium over the current valuation.
8️⃣ Catalysts & Milestones (6-12 Months)
Topline results for the Phase III CUV105 Vitiligo trial (H2 2026).
1st EU regulatory filing for NEURACTHEL marketing authorization (H2 2026).
First preclinical results for the VLRX-L liquid controlled-release formulation (H2 2026).
EMA scientific advice and recruitment launch for Phase III CUV107 (H2 2026).
9️⃣ Opportunities & Risks
Opportunities:
Successfully capturing a fraction of the 3.3 million US Vitiligo patient population will exponentially multiply revenues. Expansion into OTC dermocosmetics provides a secondary un-capped growth lever.
Risks:
Regulatory delays from the FDA/EMA for new indications, execution risks in commercializing NEURACTHEL, and potential FX headwinds given global operations.
🔟 Conclusion
Clinuvel offers a highly asymmetric risk/reward profile. With its Nasdaq ADR uplisting serving as a major catalyst for US capital flow, investors are getting a free call option on a Phase III Vitiligo blockbuster, completely backstopped by a highly profitable EPP monopoly and a fortress balance sheet.
Disclaimer: Not a financial advice. Always do your own DD.
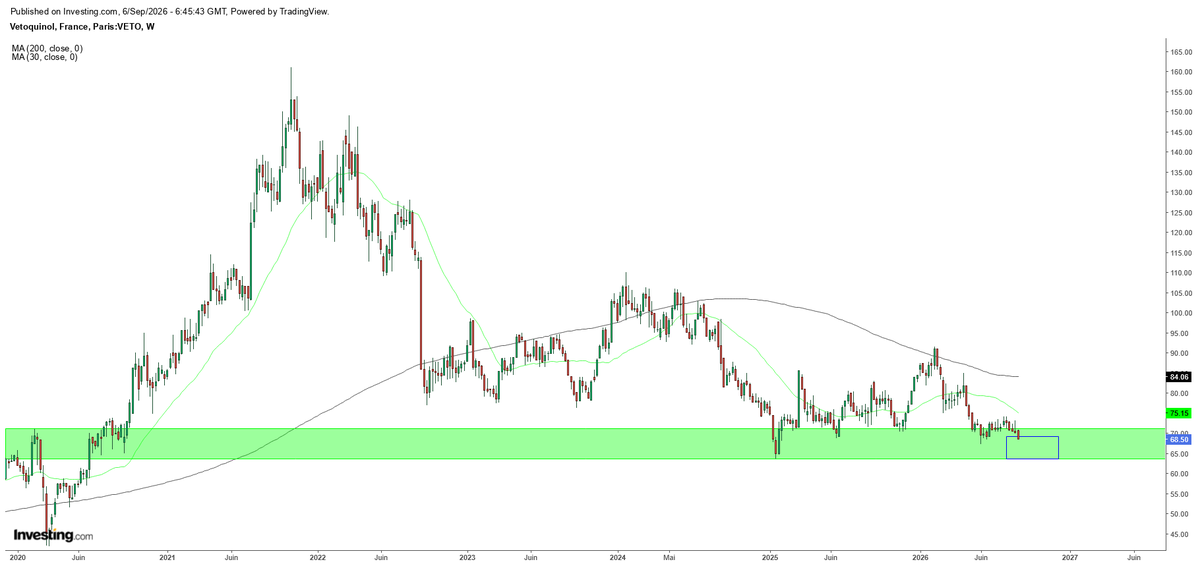
$VETO #VETOQUINOL
"Si tu n'achètes pas VETOQUINOL sur ces niveaux alors n'en achète jamais !"
Voici un magnifique dossier massacré "sans raison" 🤷♂️
Chers abonnés InvestingPRO ou InvestingPRO+, en complément, je vous conseille d'aller jeter un coup d’œil à la partie fondamentale 😜
N'hésitez-pas à discuter avec Warren AI ☺️
On fait le point dans quelques temps 😉
📢 genOway is launching in Australia!
To support the region’s thriving life sciences ecosystem, Fei Yang, PhD, & Nathalie Taquet are bringing our advanced preclinical models closer to local innovators in biotech, pharma, & academia.
Learn more: https://t.co/AJ3wNGzQVM
UBTECH Cruzr S2 wheeled humanoid assembling auto parts at WRC.
Full-size humanoids already make up nearly half of UBTECH’s revenue.
UBTECH's recently released H1 2026 interim: 921 units sold, contributing RMB 590.3M (~USD 87.8M, 46.5% of total revenue) and ~RMB 390M (~USD 58.0M) in gross profit (about 70% of group GP).